Sector Research Observatory
Autos Weekly
October 05, 2026
"Covering the world's top automakers, from Detroit to Shenzhen."
Week in Review
Trump EV Rollback Clashes With China EV Surge
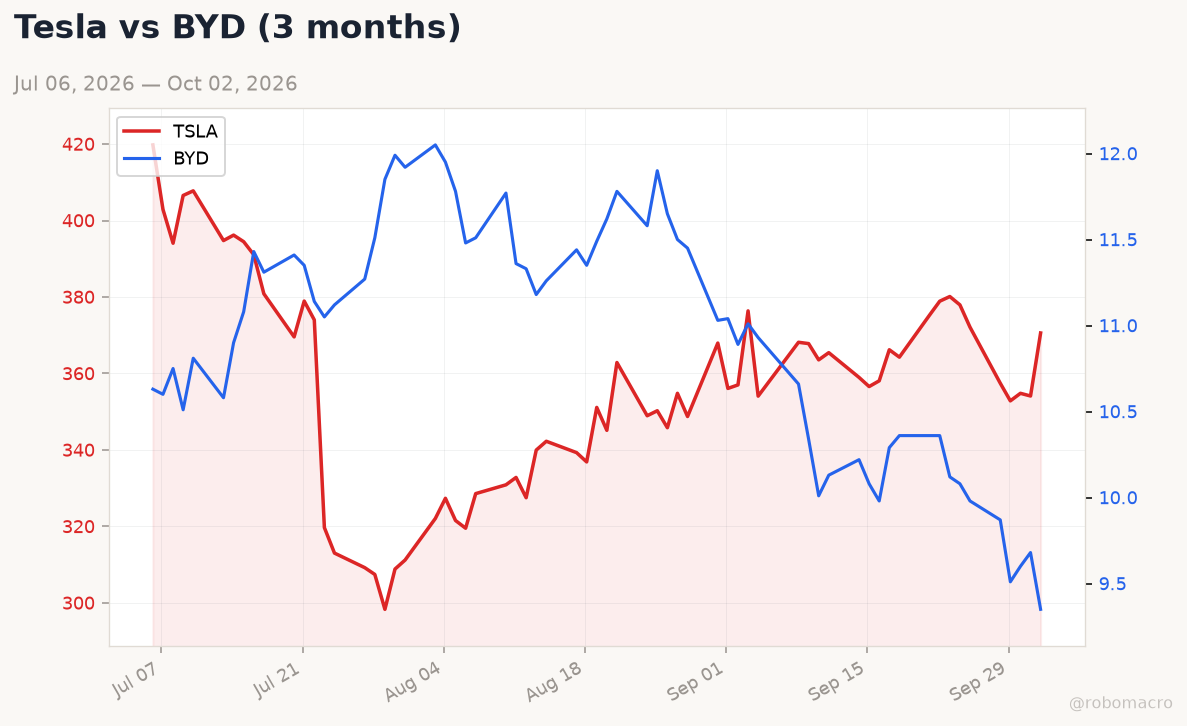
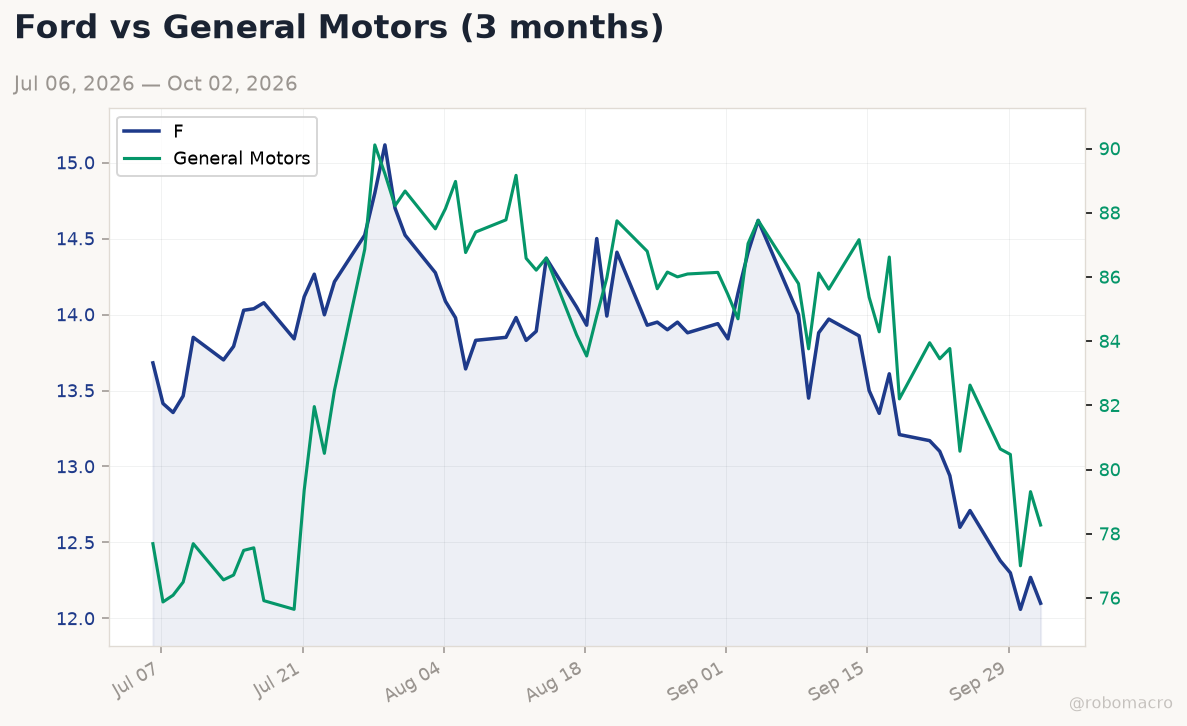
Auto stocks diverged sharply this week as Tesla gained 4.65% to 370.59 while legacy names slid, with Stellantis falling 6.18% to 4.40, Ford dropping 1.39% to 12.10 and GM declining 1.31% to 78.27. The divergence tracked the Trump administration’s finalization of weaker fuel-economy standards, a move that drew immediate lawsuits from environmental groups and prompted warnings that higher long-term fuel consumption would raise costs for consumers. Chinese EV makers continued to pressure margins in key export markets, amplifying the share-price gap between pure-play electrification names and traditional OEMs.
Market Snapshot
Auto Industry Leaders & Key Commodities
| Company / Asset | Level | Change | Ticker |
|---|---|---|---|
| US & European OEMs | |||
| Tesla | 370.59 | +4.65% | $TSLA |
| Ford | 12.10 | -1.39% | $F |
| General Motors | 78.27 | -1.31% | $GM |
| Stellantis | 4.40 | -6.18% | $STLA |
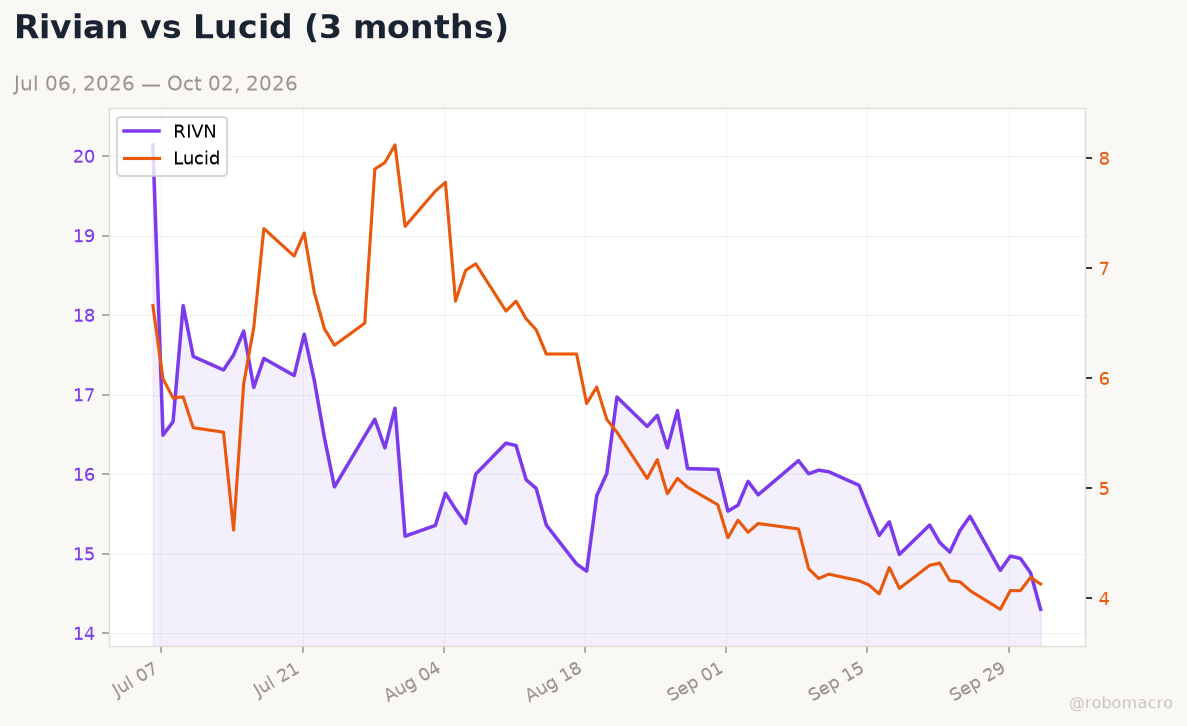
| Rivian | 14.30 | -3.12% | $RIVN |
| Lucid | 4.13 | -1.43% | $LCID |
| Asian OEMs | |||
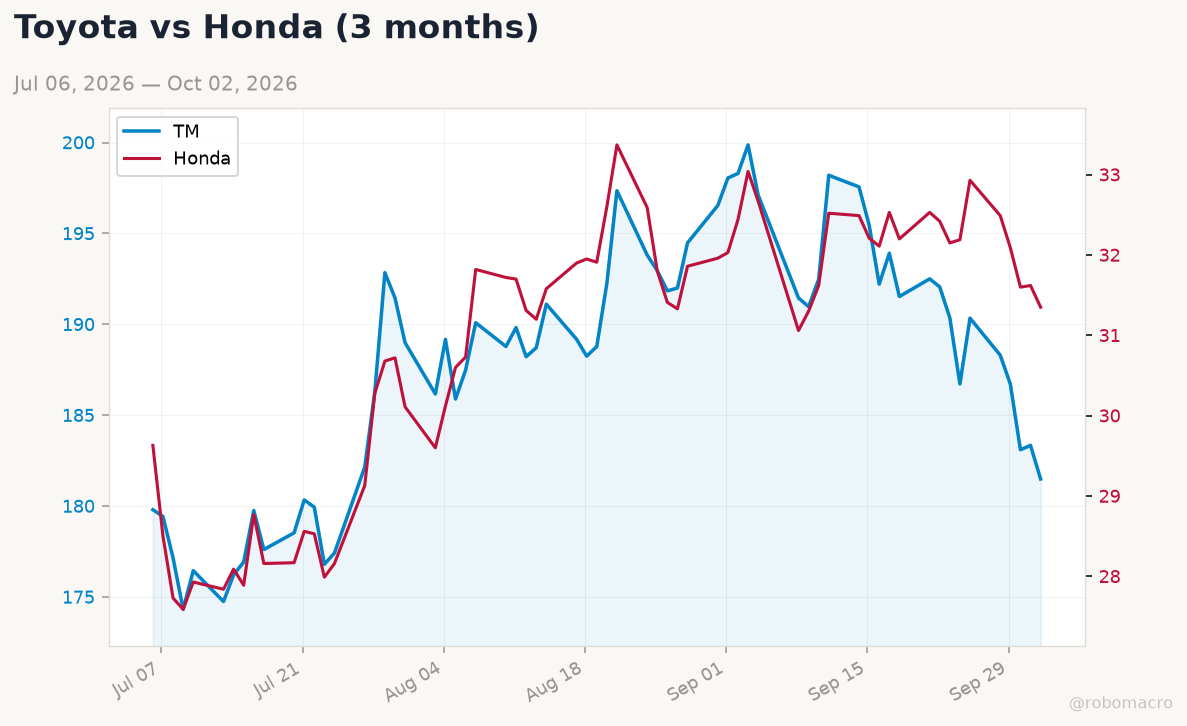
| Toyota | 181.49 | -1.01% | $TM |
| Honda | 31.35 | -0.85% | $HMC |
| BYD | 9.35 | -3.41% | $BYDDY |
| NIO | 3.37 | -0.88% | $NIO |
| XPeng | 9.25 | -1.80% | $XPEV |
| Li Auto | 10.69 | -3.87% | $LI |
| Supply Chain | |||
| Magna International | 64.57 | +0.17% | $MGA |
| Aptiv | 43.54 | -0.98% | $APTV |
| Commodities | |||
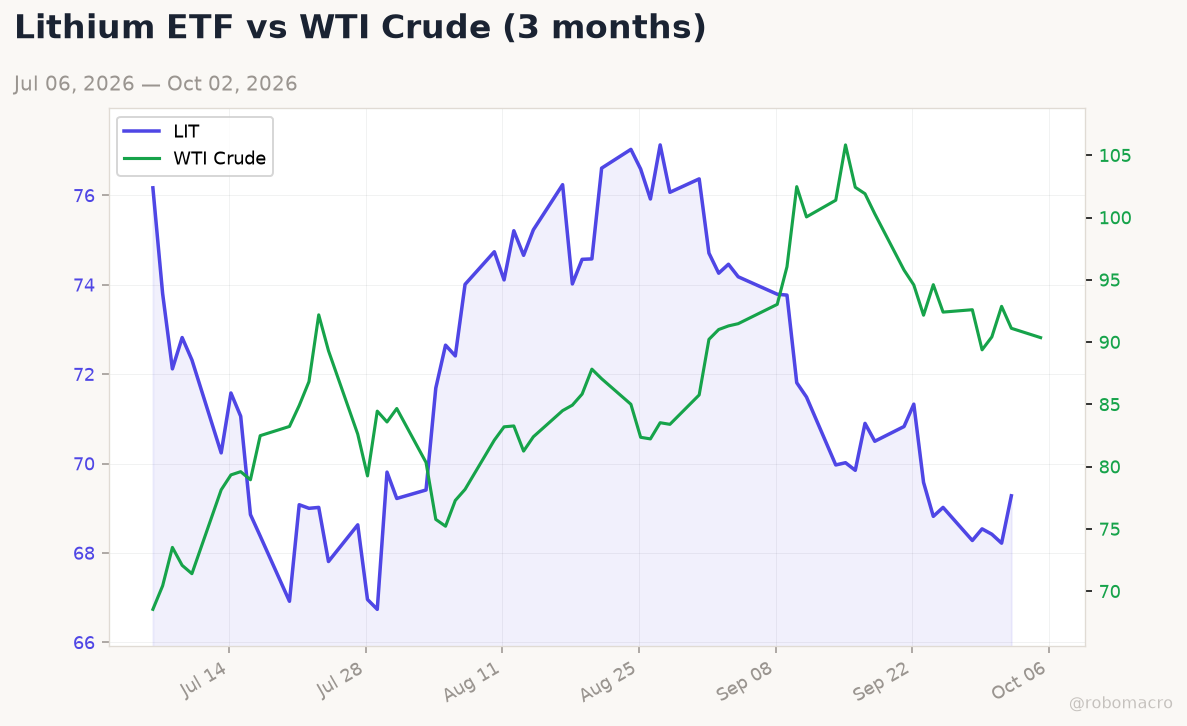
| WTI Crude | 90.40 | -0.78% | — |
| Brent Crude | 102.71 | +0.45% | — |
| Lithium ETF (LIT) | 69.28 | +1.55% | — |
Source: Market data via yfinance as of Oct 05, 2026. Tickers for reference only.
Spotlight Read
Trump Finalizes Weaker Fuel-Economy Rules, Sparking Lawsuits
The Department of Transportation rolled back Biden-era mileage standards, claiming the change will lower new-vehicle prices by about $1,300 and save Americans $138 billion over five years. Environmental groups immediately sued, arguing the policy will increase fuel use 44% and raise pump prices 76 cents per gallon. The decision directly affects GM, Ford and Stellantis planning cycles while giving Chinese exporters additional runway in Europe and Asia.
Latest Industry News
Ford CEO Warns Europe Lost to Chinese EVs
Ford’s chief executive urged Washington to proceed carefully before allowing Chinese vehicles into the U.S., citing rapid share gains by BYD and others in Europe. $F shares fell 1.39%.
Source: Gizmodo.com
2027 Hyundai Tucson Adds 81 km PHEV Variant
Hyundai detailed the fifth-generation Tucson for Korea launch this year and global markets in 2027, including a 292 PS plug-in hybrid. $HYMTF plans broader electrification across its SUV lineup.
Source: Paul Tan's Automotive News
India Festive Season Lifts Automaker Output Plans
Major Indian manufacturers are increasing production and dealer stocks to meet strong bookings during the peak festive period. Domestic names including Tata Motors and JSW Motors are expanding capacity.
Source: Business Standard
EnPower Rebrands as CAMINUS for Volume Output
The Indianapolis lithium-ion cell maker changed its name to CAMINUS as it scales production for defense and industrial customers. The move supports U.S. efforts to reduce reliance on Asian battery supply.
Source: PRNewswire
Auto Stocks Drag Sensex Lower on Oil, Outflows
Indian equities closed lower for a second day as crude prices and foreign selling hit auto names. $TM, $HMC and local OEMs all finished in the red.
Source: BusinessLine
Highway Roop Buys Chamundi Die Cast for IPO Push
Carlyle-backed Highway Roop acquired the precision-casting firm to broaden its automotive components platform ahead of a planned listing. The deal adds scale in India’s supply chain.
Source: Livemint
Hyundai Launches 4-to-18 Tonne Electric Forklifts
Hyundai completed its heavy forklift range with new battery-electric models, giving dealers a full electric counterbalance lineup from 4 to 18 tonnes. The expansion targets European and Asian industrial markets.
Source: Electrek
JSW Motors Sees CAFE-3 Norms as Clear EV Roadmap
The Indian entrant said new CAFE-3 regulations provide regulatory certainty for its upcoming energy-vehicle launches. The rules align with India’s broader push to accelerate electrification.
Source: BusinessLine
EV & Battery Watch
Electric Vehicle & Battery Technology Developments
Chinese EV makers widened their lead in Europe, prompting Ford’s CEO to call for measured U.S. policy on imports. At the same time, Hyundai’s new Tucson PHEV with 81 km electric range illustrates how legacy OEMs are extending range-extender and plug-in strategies to ease consumer range anxiety while battery costs remain elevated. The LIT ETF’s 1.55% gain reflected continued investor interest in lithium supply despite softer EV sales momentum in several markets.
Supply Chain & Trade
Global Supply Chain & Trade Policy
Semiconductor and battery-material sourcing stayed in focus as elevated oil prices and potential tariff shifts raised input costs for North American and European assemblers. Magna and Aptiv reported modest share moves while suppliers monitored cross-border parts flows that cross the U.S.-Canada border multiple times. The Trump trade stance on Canada could lift component prices at Michigan dealerships if tariffs expand.
Data Observatory
Auto Sector Charts
Week Ahead
Key Events for the Auto Sector
Investors will watch U.S. consumer-confidence data and manufacturing PMI releases for signs of demand resilience amid higher energy prices. Any early signals on 2027 model-year pricing from Detroit automakers will be scrutinized after the fuel-economy rollback.
Subscribe to Autos Weekly and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com to log in and manage subscriptions, or use Forgot Password to set a password.
