ANZ Macro Daily(Beta Mode)
RBA Hike Odds Rise Ahead of NZ GDP
Market Snapshot
| Asset | Level | Change |
|---|---|---|
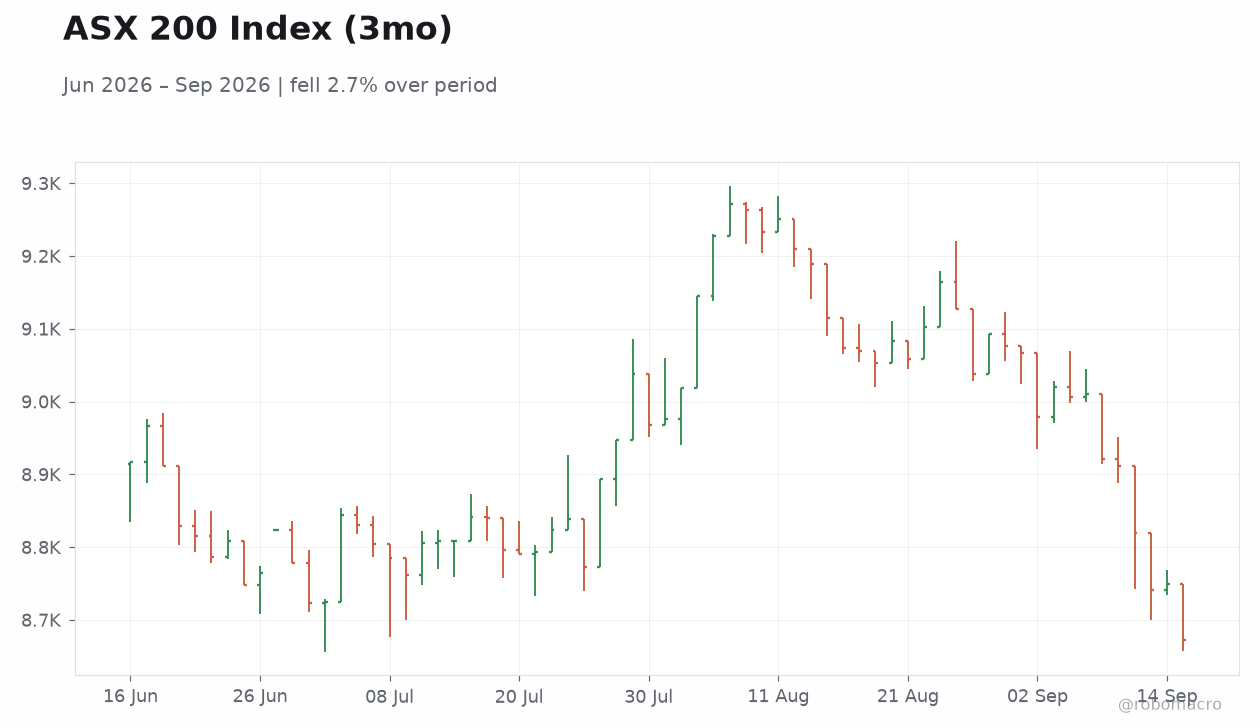
| ASX 200 | 8,672.50 | -0.88% |
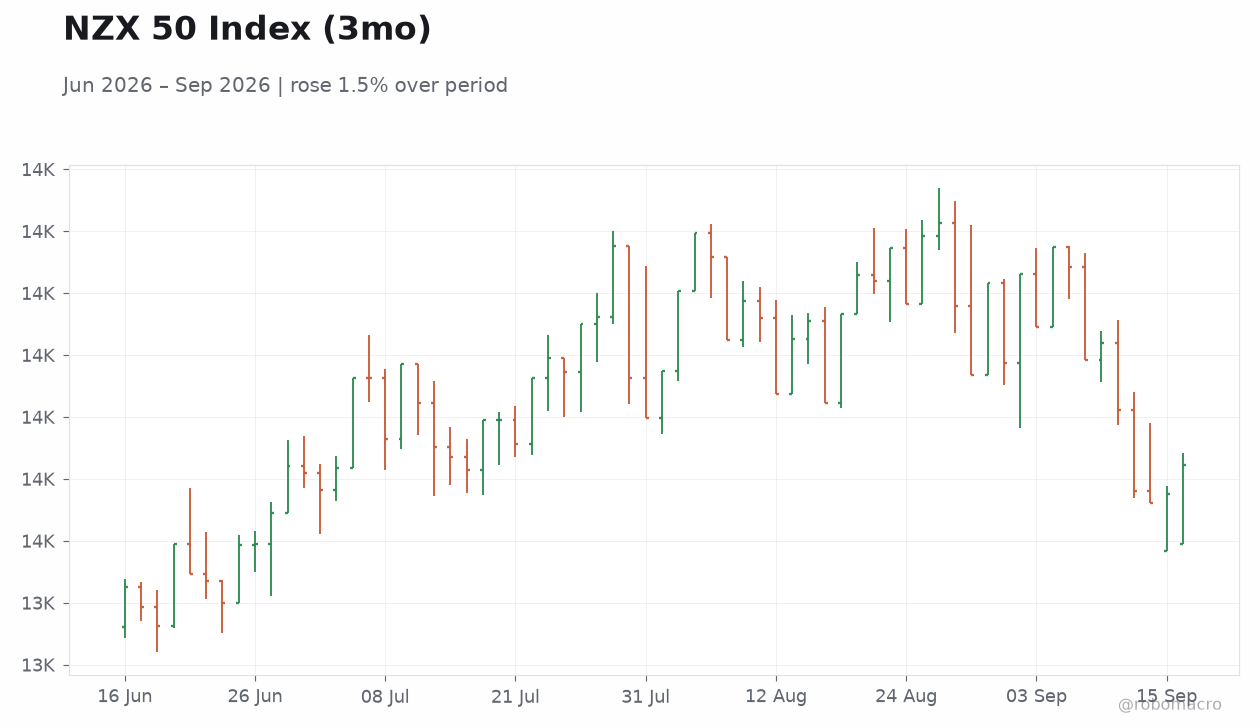
| NZX 50 | 13,622.72 | +0.35% |
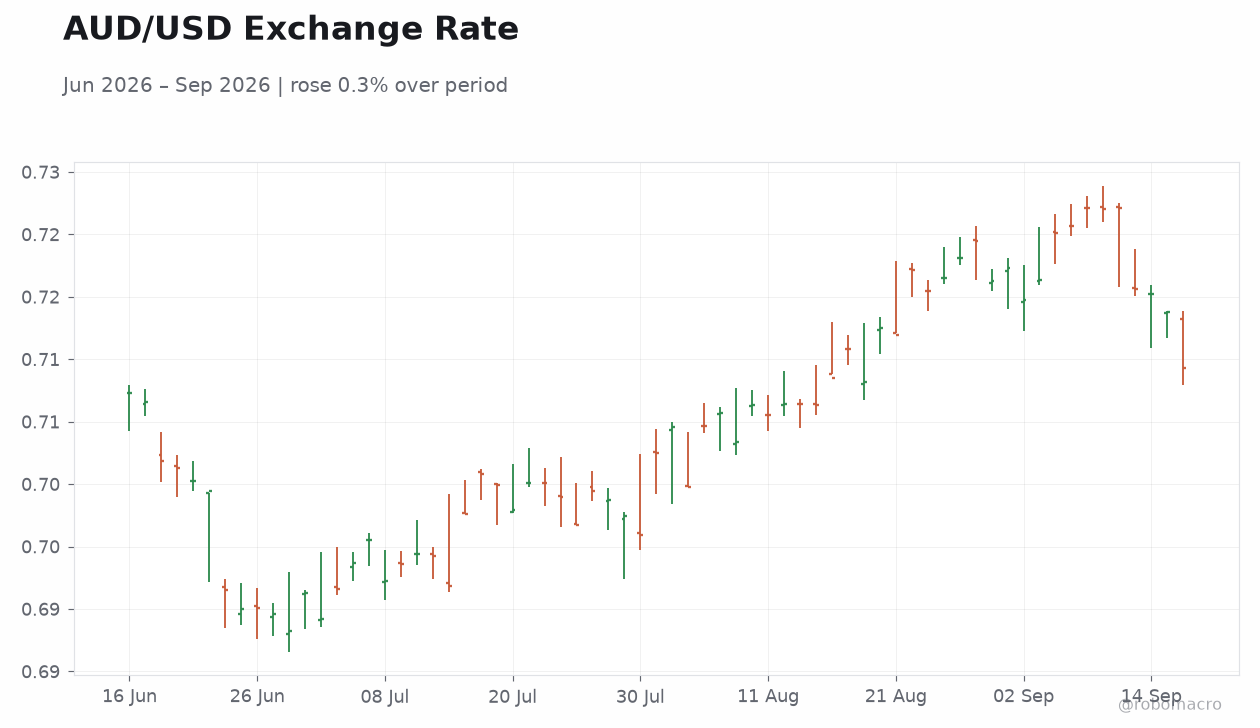
| AUD/USD | 0.71 | -0.62% |
| NZD/USD | 0.57 | -1.08% |
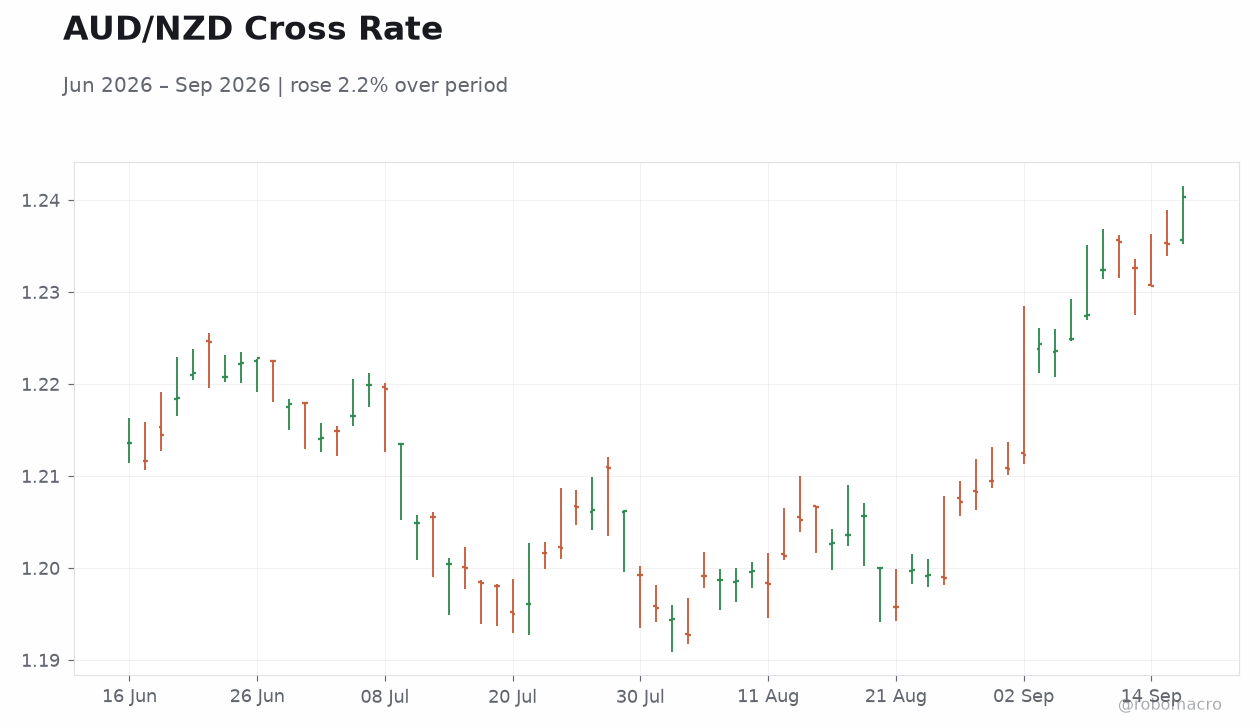
| AUD/NZD | 1.24 | +0.38% |
| BHP | 60.20 | +1.60% |
| Gold | 4,314.60 | -0.42% |
| Brent Crude | 105.28 | -3.19% |
| Bitcoin | 75,941.73 | +0.44% |
| Australia 2Y Govt Yield | 4.83% | +3 bp |
| Australia 10Y Govt Yield | 5.20% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Current Account Balance | -1,090m | -2,570m | -1,670m |
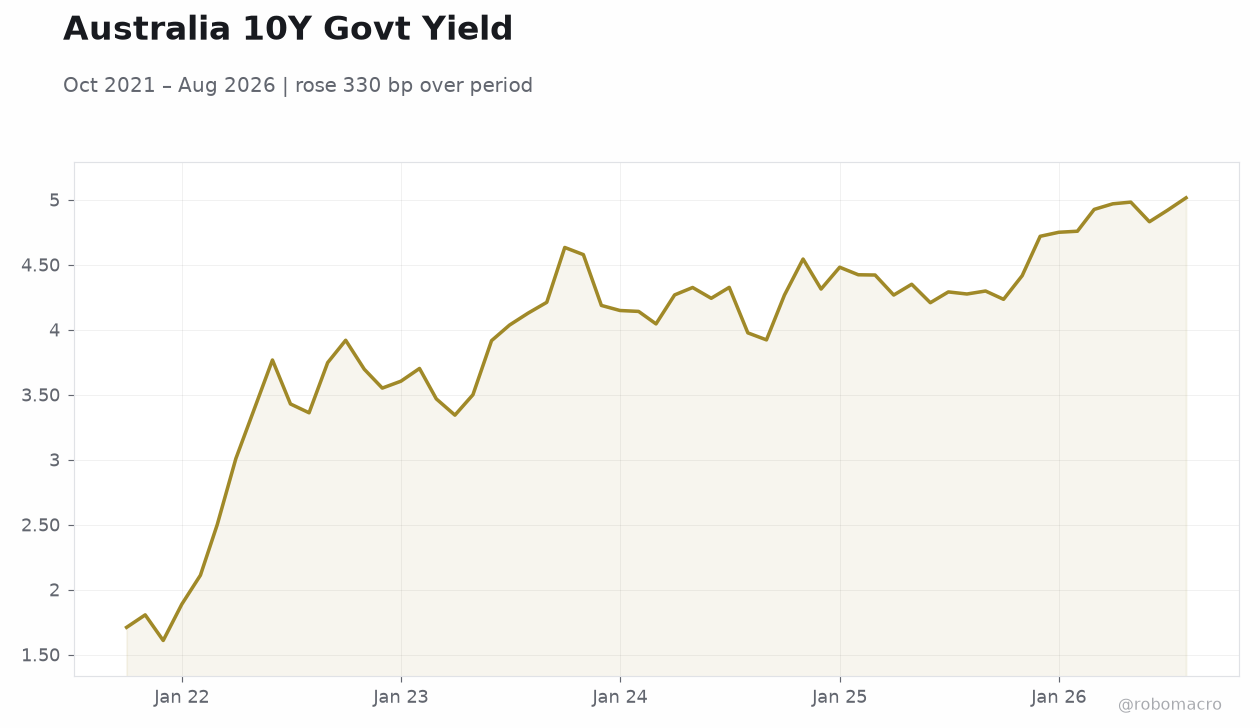 Australia 10Y Govt Yield | Type: macro_line | Yield (%): 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.71,3.551,4.141,4.267,4.831,5.015
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| GDP Growth Quarter-over-Quarter | 0.80 | 0.10 | 14:45 |
| GDP Growth Year-over-Year | 1.50 | 2.30 | 14:45 |
| Trade Balance | -1,950m | -1,275m | 14:45 |
- NZ current account deficit narrowed to NZ$1.67 bn, beating consensus.
- ASX 200 fell 0.88% while NZX 50 rose 0.35%; AUD and NZD both weakened.
- Markets now price 76% chance of RBA rate rise in September.
Yesterday's Recap
New Zealand’s current account balance printed at –NZ$1.67 bn, narrower than the –NZ$2.57 bn consensus though wider than the prior –NZ$1.09 bn. The out-turn eased external-balance concerns ahead of today’s GDP release. The ASX 200 declined 0.88% to 8,672.50 while the NZX 50 advanced 0.35% to 13,622.72.
AUD/USD fell 0.62% to 0.71 and NZD/USD dropped 1.08% to 0.57, lifting AUD/NZD 0.38% to 1.24. Australian 2-year yields rose 3 bp to 4.83% and the 10-year yield added 2 bp to 5.20%. Brent crude’s 3.19% decline and gold’s 0.42% drop weighed on both currencies, reflecting softer Chinese demand signals for Australian iron ore, LNG and New Zealand dairy exports.
BHP gained 1.60% to 60.20, providing a partial offset in the resources sector.
The Day Ahead
New Zealand will release GDP growth figures for the June quarter at 14:45 ET, with consensus calling for 0.1% quarter-on-quarter and 2.3% year-on-year. The trade balance follows tomorrow. No RBA or RBNZ policy meetings are scheduled.
Westpac’s leading index, which edged closer to trend, points to softer but still positive Australian momentum. Markets will watch for any further signals on RBA timing after major banks lifted fixed-rate pricing in anticipation of a September move.
Other Economic Notes
Australian housing density initiatives, including expanded granny-flat approvals, aim to ease supply constraints amid persistent affordability pressures. Commodity price weakness, especially in energy, is trimming near-term trade support for both currencies while highlighting China’s growth sensitivity. Westpac’s leading index confirms Australian growth is moderating yet remains above stall speed, consistent with the RBA’s hawkish stance.
New Zealand dairy margins face further compression if a strong El Niño materialises, adding downside risk to rural incomes and export values.
Global Macro News
The Australian dollar is treading water against the yen ahead of the Bank of Japan’s expected rate decision. Markets are also bracing for the Federal Reserve’s policy announcement, with AUD/USD already below 0.7150. Lower Brent prices reduce immediate revenue support for Australian LNG and New Zealand dairy exports.
↓ p.2