ANZ Macro Daily(Beta Mode)
NZ GDP Beats, AUD Hits One-Month Low
Market Snapshot
| Asset | Level | Change |
|---|---|---|
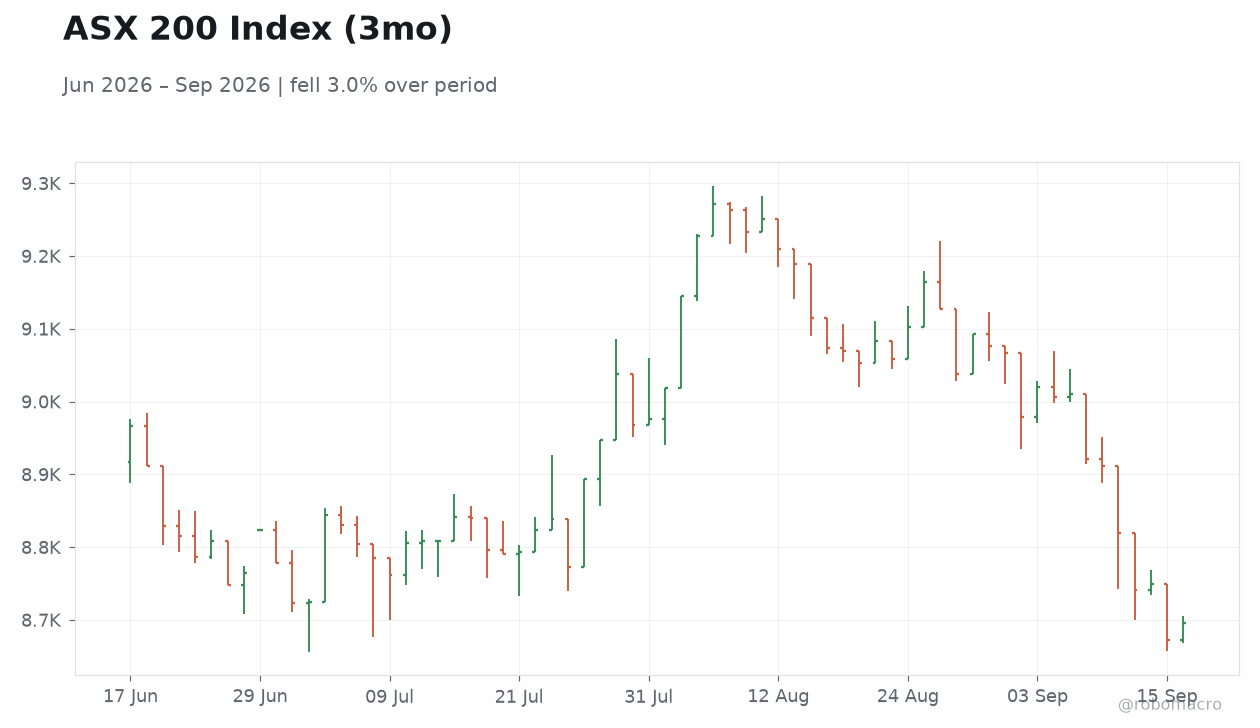
| ASX 200 | 8,696.50 | +0.28% |
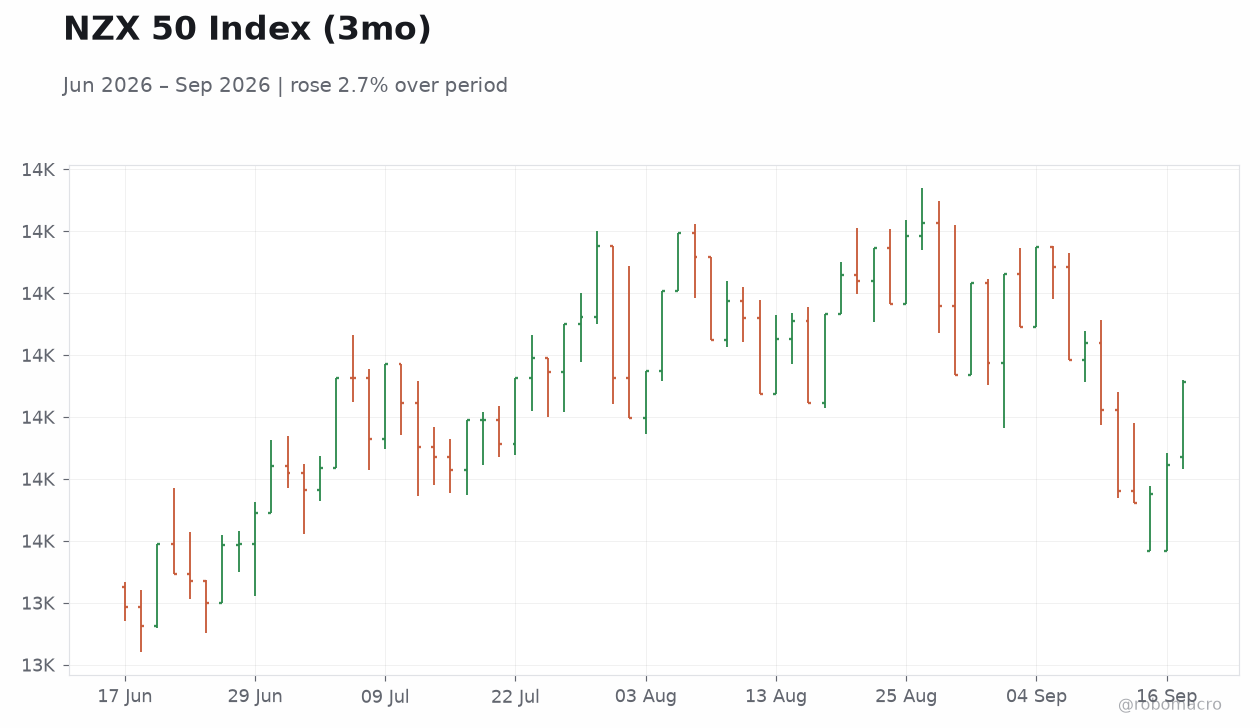
| NZX 50 | 13,756.59 | +0.98% |
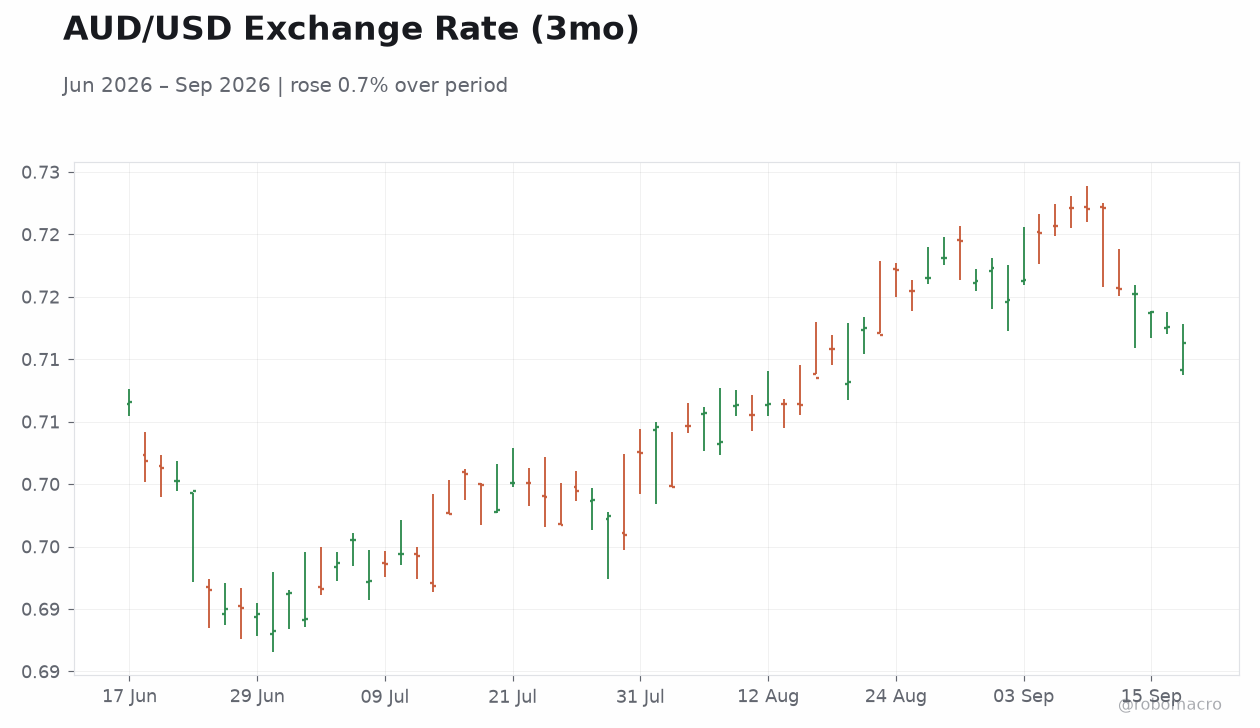
| AUD/USD | 0.71 | -0.18% |
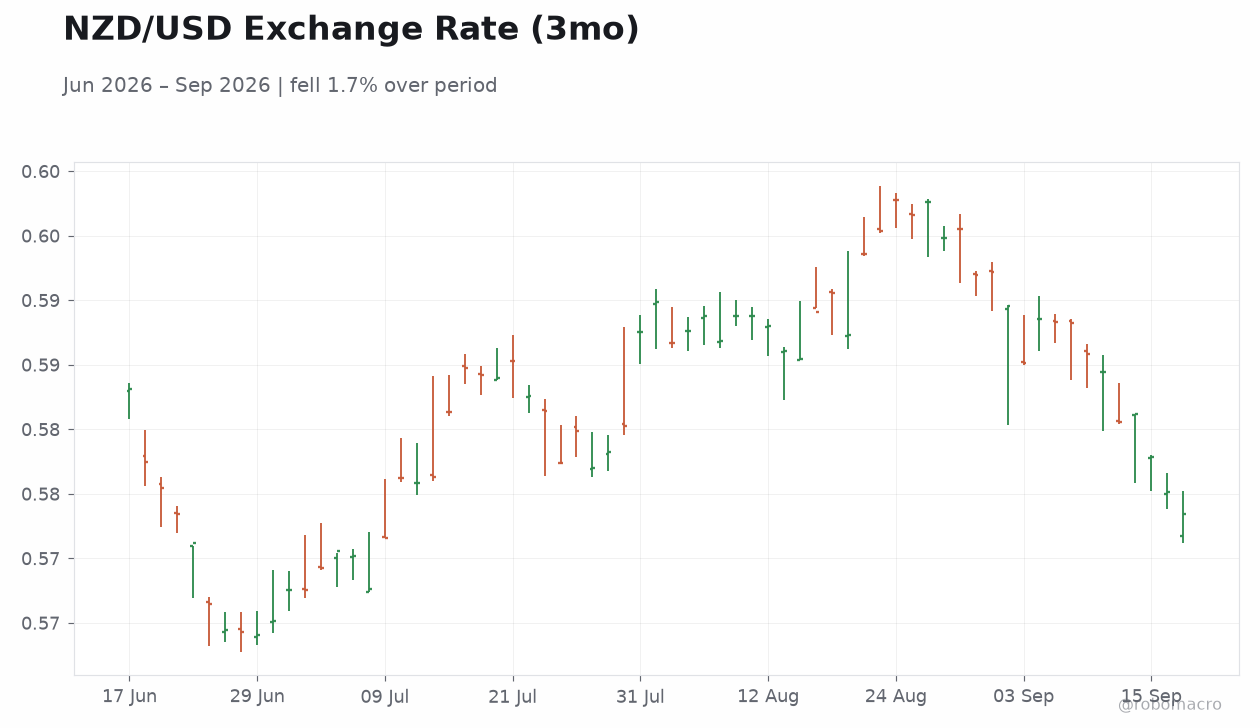
| NZD/USD | 0.57 | -0.30% |
| AUD/NZD | 1.24 | +0.09% |
| BHP | 60.21 | +0.02% |
| Gold | 4,385.30 | -0.05% |
| Brent Crude | 104.04 | -1.69% |
| Bitcoin | 76,466.01 | +0.41% |
| Australia 2Y Govt Yield | 4.83% | +3 bp |
| Australia 10Y Govt Yield | 5.20% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| GDP Growth Quarter-over-Quarter | 0.90 | 0.10 | 0.20 |
| GDP Growth Year-over-Year | 1.70 | 2.30 | 2.60 |
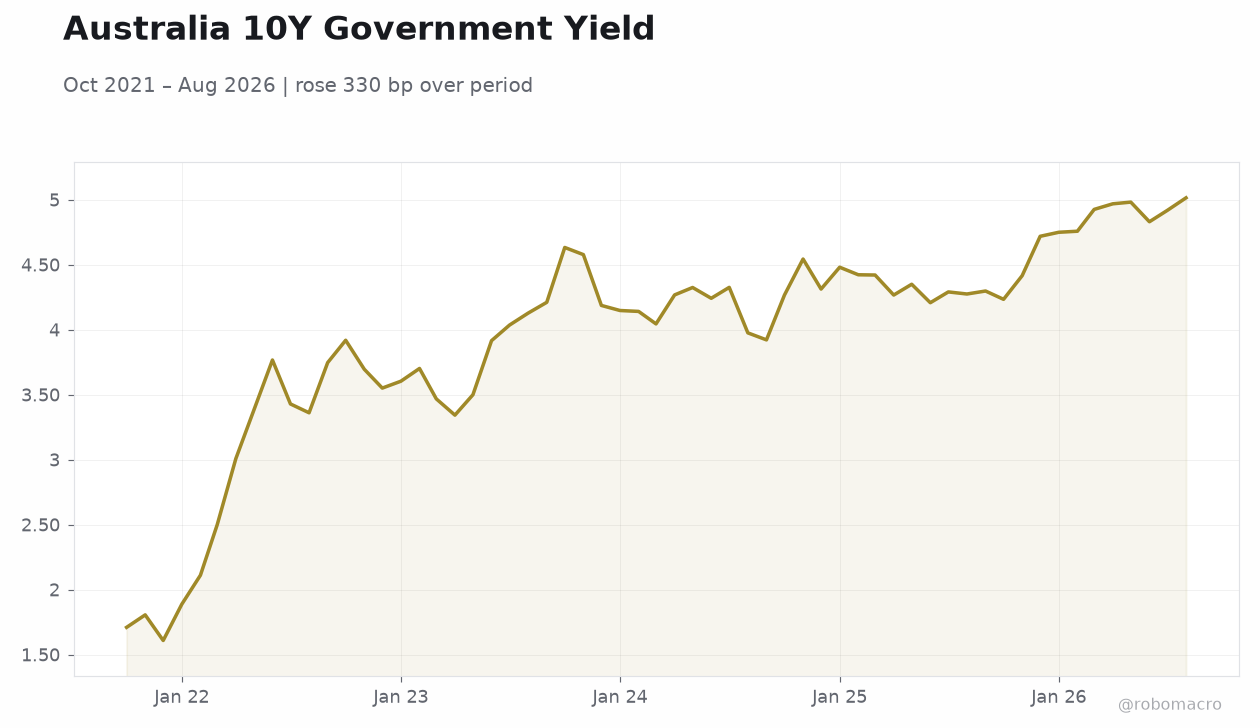 Australia 10Y Government Yield | Type: macro_line | Yield %: 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.71,3.551,4.141,4.267,4.831,5.015
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | -1,950m | -1,775m | 18:45 |
| Speech by RBA's Hunter | - | - | 15:00 |
| S&P Global Manufacturing PMI Flash | 52 | - | 19:00 |
| S&P Global Services PMI Flash | 53.20 | - | 19:00 |
| Employment Change | -15,800 | - | 21:30 |
| Full-Time Employment Change | 16,300 | - | 21:30 |
| Unemployment Rate | 4.50 | - | 21:30 |
- New Zealand Q2 GDP surprised higher at 0.2% QoQ and 2.6% YoY, easing growth concerns.
- Australian dollar fell to a one-month low at 0.71 amid steady RBA hold expectations.
- ASX 200 rose 0.28% while Australian 2-year yields climbed 3 bp to 4.83%.
Yesterday's Recap
New Zealand Q2 GDP printed 0.2% quarter-over-quarter, above the 0.1% consensus, while year-over-year growth reached 2.6% versus 2.3% expected. The ASX 200 advanced 0.28% to 8,696.50 and the NZX 50 gained 0.98% to 13,756.59. AUD/USD declined 0.18% to 0.71 and NZD/USD fell 0.30% to 0.57.
Australian 2-year government yields rose 3 bp to 4.83% and the 10-year yield increased 2 bp to 5.20%. Brent crude dropped 1.69% to 104.04 while BHP edged up 0.02% to 60.21. Market commentary highlighted the Australian dollar's one-month low and expectations that the RBA will hold rates steady in September.
Westpac's leading index edged toward trend, signalling softer but improving Australian growth as the RBA maintains a hawkish stance. Commentary stressed that the RBA should avoid cuts until inflation is fully subdued at 3.45% YoY. New Zealand's stronger-than-expected GDP print reduces immediate downside risks to growth, with the RBNZ OCR at 2.75% and CPI at 4.10% YoY.
The Day Ahead
New Zealand releases its Trade Balance at 18:45 ET today. An RBA speech by Hunter is scheduled for 15:00 ET on 21 September. Australia publishes S&P Global Manufacturing and Services PMI flashes on 22 September.
Employment change, full-time employment change and the unemployment rate follow on 23 September. These releases will provide fresh signals on Australian labour market momentum ahead of the October RBA meeting. Markets will also monitor any commentary on inflation persistence and global rate differentials.
Other Economic Notes
Australia's commodity export linkages to China remain central, with BHP serving as a key bellwether for mining sentiment. Housing market resilience continues to support domestic demand in both countries despite elevated policy rates. New Zealand faces additional growth risks from an emerging El Niño pattern that could squeeze dairy margins.
India's progress toward an FTA with New Zealand offers longer-term trade diversification potential for the smaller economy.