ANZ Macro Daily(Beta Mode)
RBA Hike Bets Rise Despite Jobless Spike
Market Snapshot
| Asset | Level | Change |
|---|---|---|
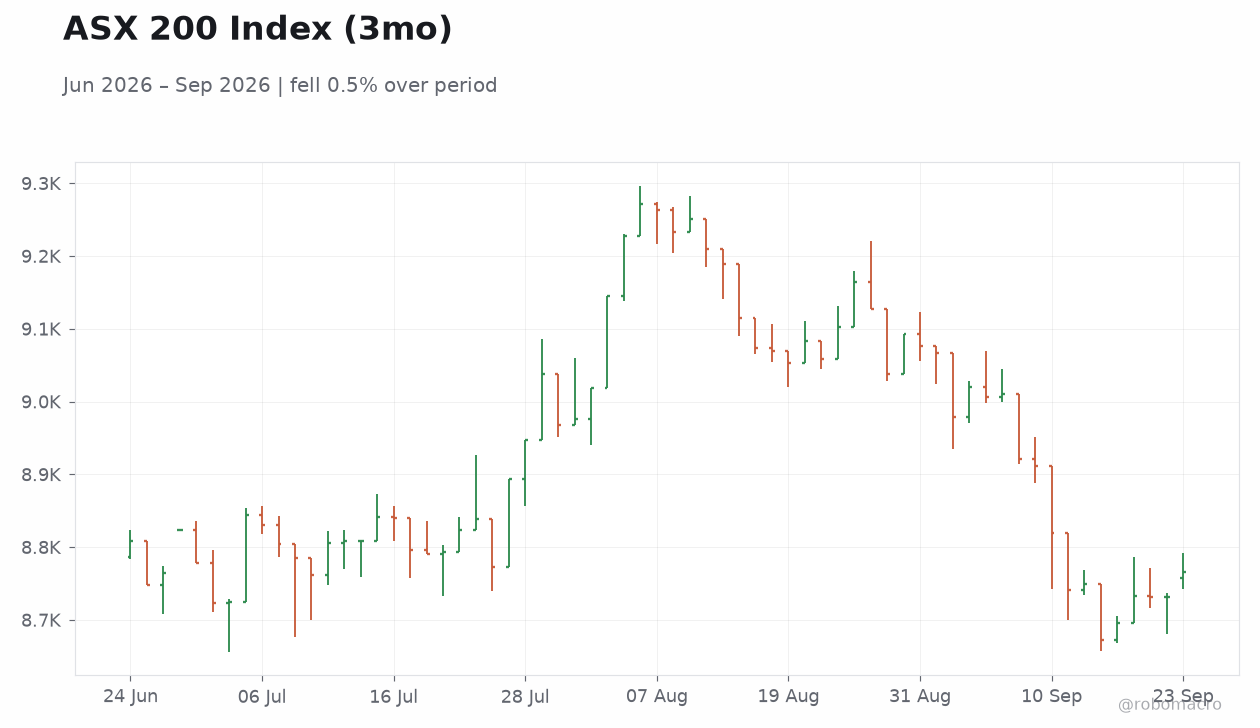
| ASX 200 | 8,765.30 | +0.38% |
| NZX 50 | 13,824.83 | +0.02% |
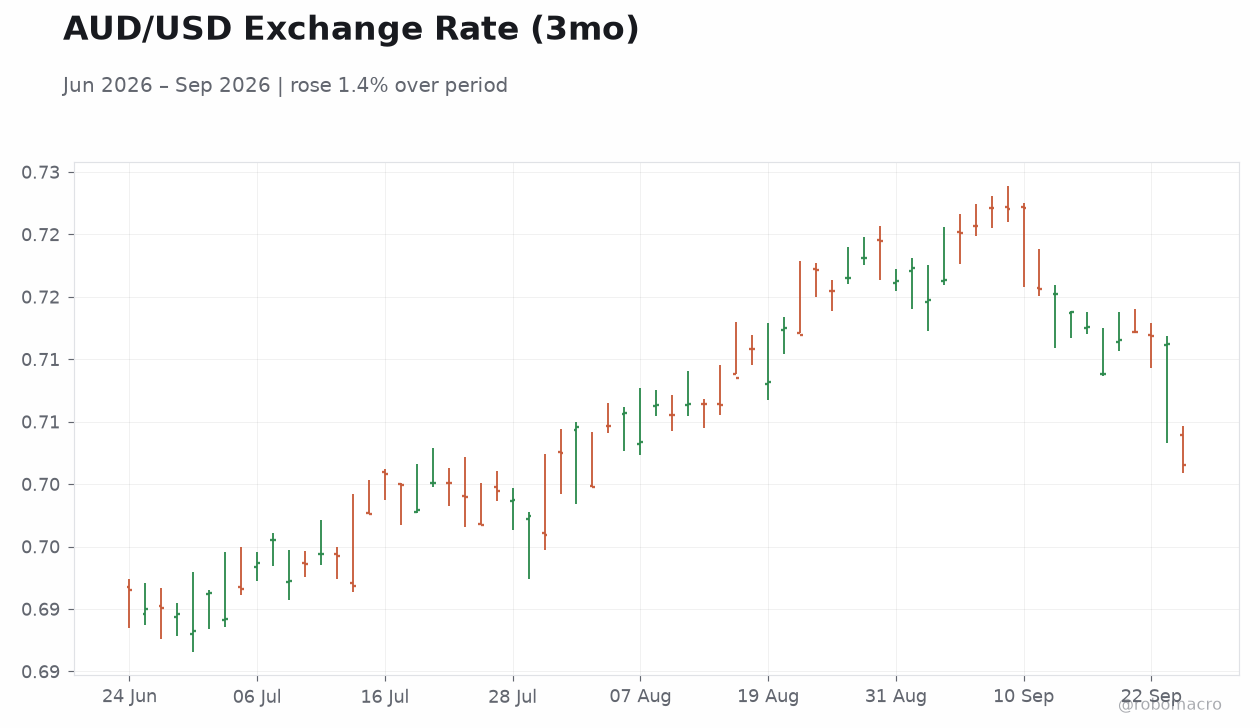
| AUD/USD | 0.70 | -1.36% |
| NZD/USD | 0.57 | -1.11% |
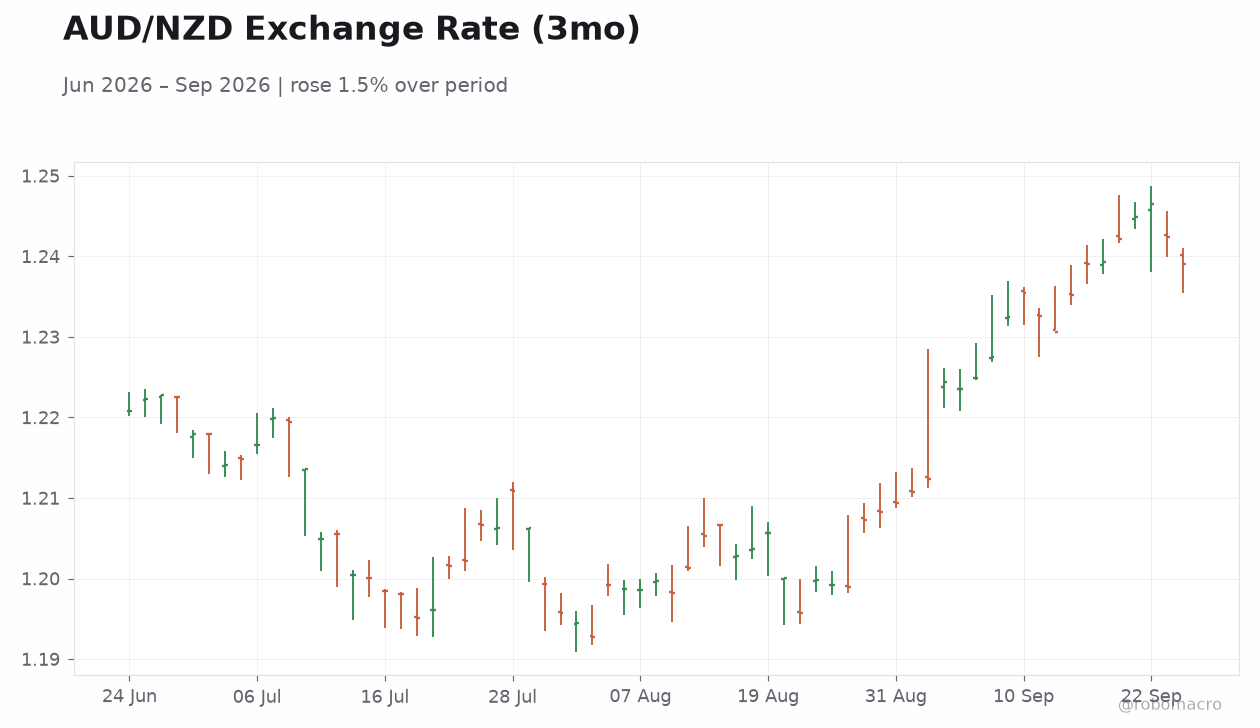
| AUD/NZD | 1.24 | -0.28% |
| BHP | 61.02 | -1.69% |
| Gold | 4,308.10 | -0.24% |
| Brent Crude | 107.39 | +4.18% |
| Bitcoin | 84,336.96 | -0.05% |
| Australia 2Y Govt Yield | 5.00% | -5 bp |
| Australia 10Y Govt Yield | 5.35% | -6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
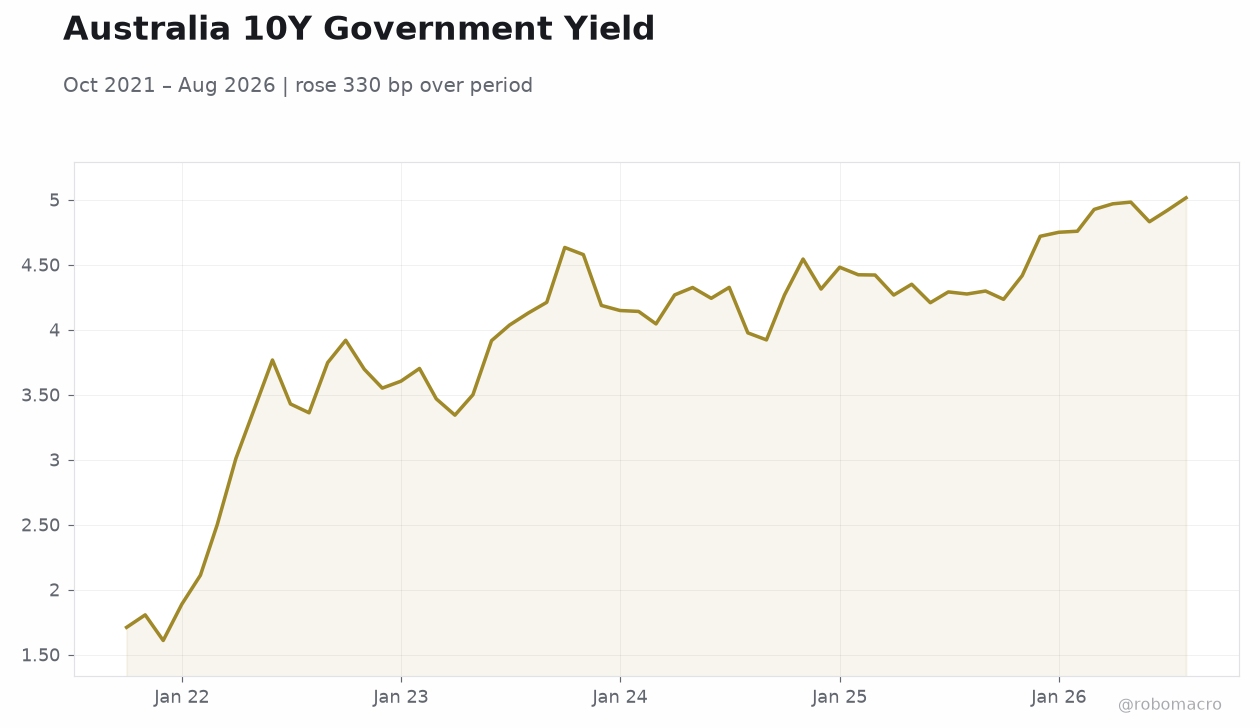 Australia 10Y Government Yield | Type: macro_line | 10Y Yield (%): 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.71,3.551,4.141,4.267,4.831,5.015
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- ASX 200 rose 0.38% while AUD/USD fell 1.36% amid RBA rate-hike speculation.
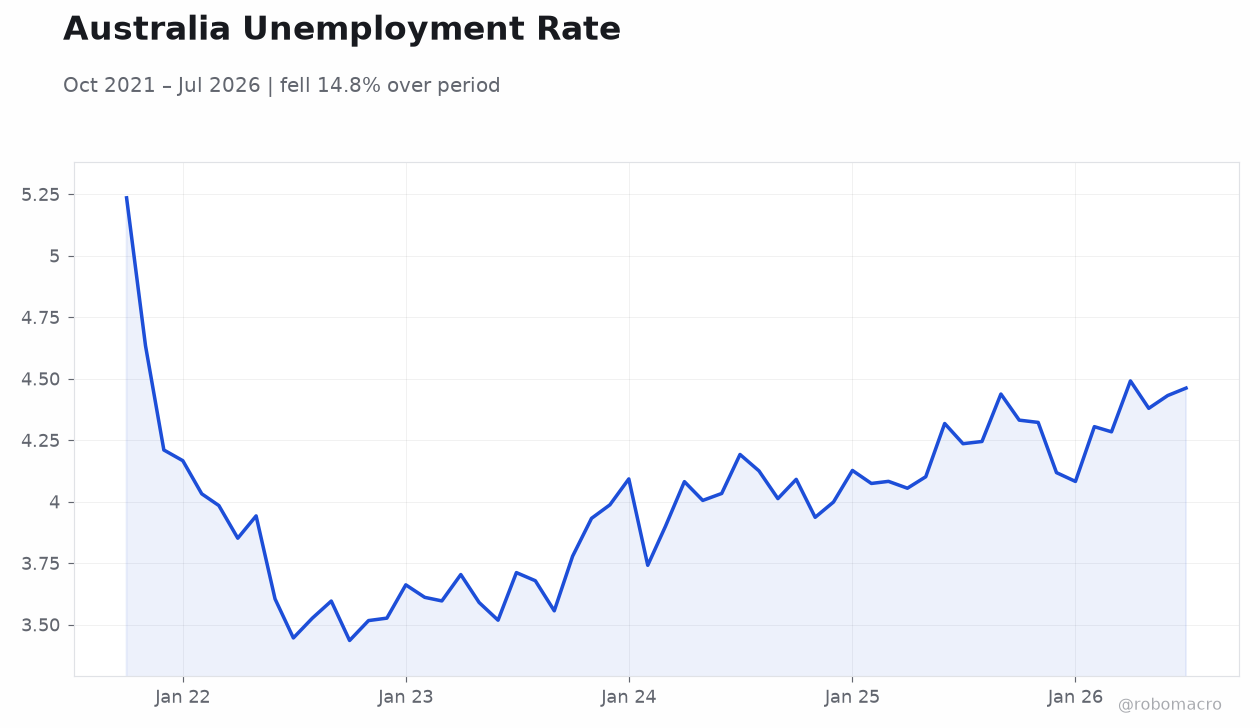
- Australia’s unemployment rate reached a five-year high yet markets still price September tightening.
- NZD/USD declined 1.11% as RBNZ hike expectations offered only partial support against USD strength.
Yesterday's Recap
Equity markets in Australia and New Zealand posted modest gains on 23 September with the ASX 200 closing at 8,765.30, up 0.38%, and the NZX 50 edging 0.02% higher to 13,824.83. BHP fell 1.69% to 61.02, weighing on resources. Australian government bond yields declined, with the 2-year yield easing 5 bp to 5.00% and the 10-year yield falling 6 bp to 5.35%.
AUD/USD dropped 1.36% to 0.70 while NZD/USD slipped 1.11% to 0.57. Brent crude jumped 4.18% to 107.39, supporting commodity-linked sentiment, while gold eased 0.24% to 4,308.10. No macroeconomic data releases occurred in either Australia or New Zealand.
News flow instead focused on Australia’s labour-market resilience prompting fresh RBA tightening expectations despite the higher jobless rate.
The Day Ahead
The calendar remains empty for 24 and 25 September with no scheduled releases from the ABS, Stats NZ, RBA or RBNZ. Markets will therefore track offshore drivers including any further USD moves and commodity price updates. Australian housing commentary may continue to highlight reduced support ahead of potential policy tightening.
New Zealand participants will monitor NZD reaction to ongoing RBNZ hike pricing. Overall, the quiet domestic schedule leaves sentiment exposed to global risk appetite and China-related trade data.
Other Economic Notes
Australia’s position as a major commodity exporter leaves the economy sensitive to iron-ore, coal and LNG price swings driven by Chinese demand. The recent Brent surge offers some offset but AUD weakness signals caution on the growth outlook. New Zealand’s dairy and tourism sectors face similar external headwinds, with construction activity also vulnerable to higher borrowing costs.
Both economies retain strong housing-market linkages that amplify monetary-policy transmission. China’s growth trajectory remains the dominant external variable for ANZ export revenues and terms of trade.