ANZ Macro Daily(Beta Mode)
RBA Hike Expected as AUD Holds 70 Cents
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| ASX 200 | 8,665.00 | -0.43% |
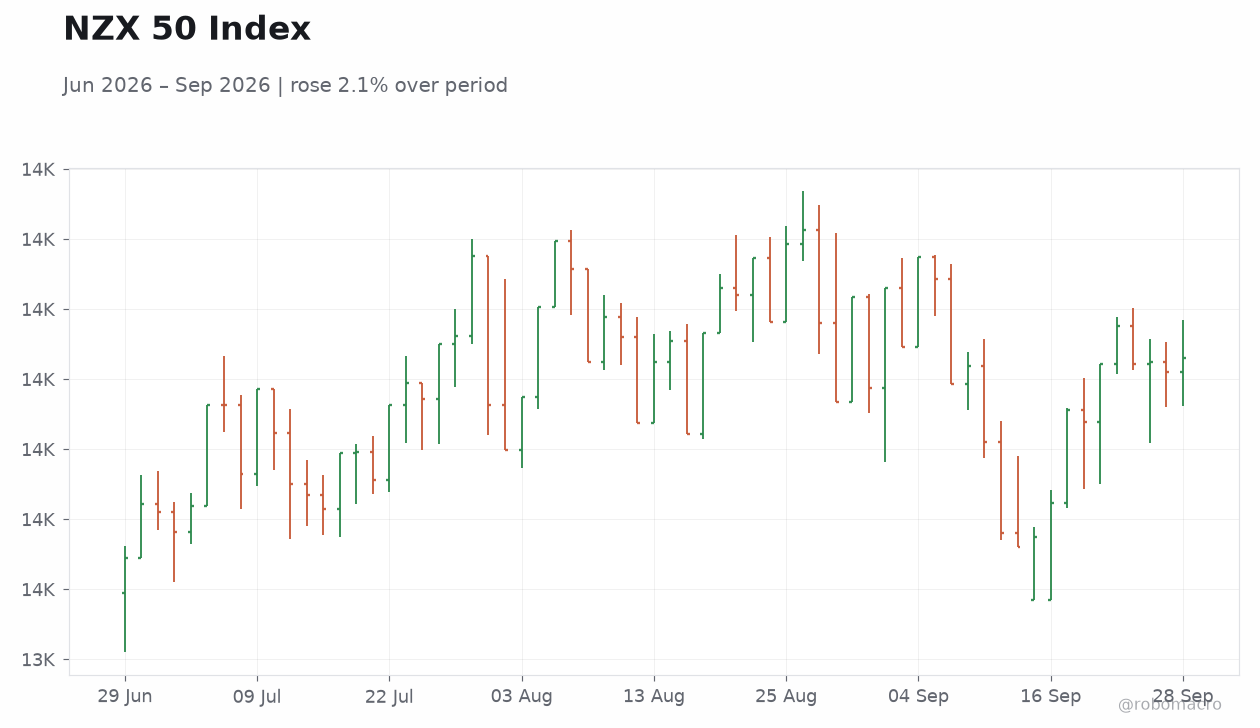
| NZX 50 | 13,830.68 | +0.14% |
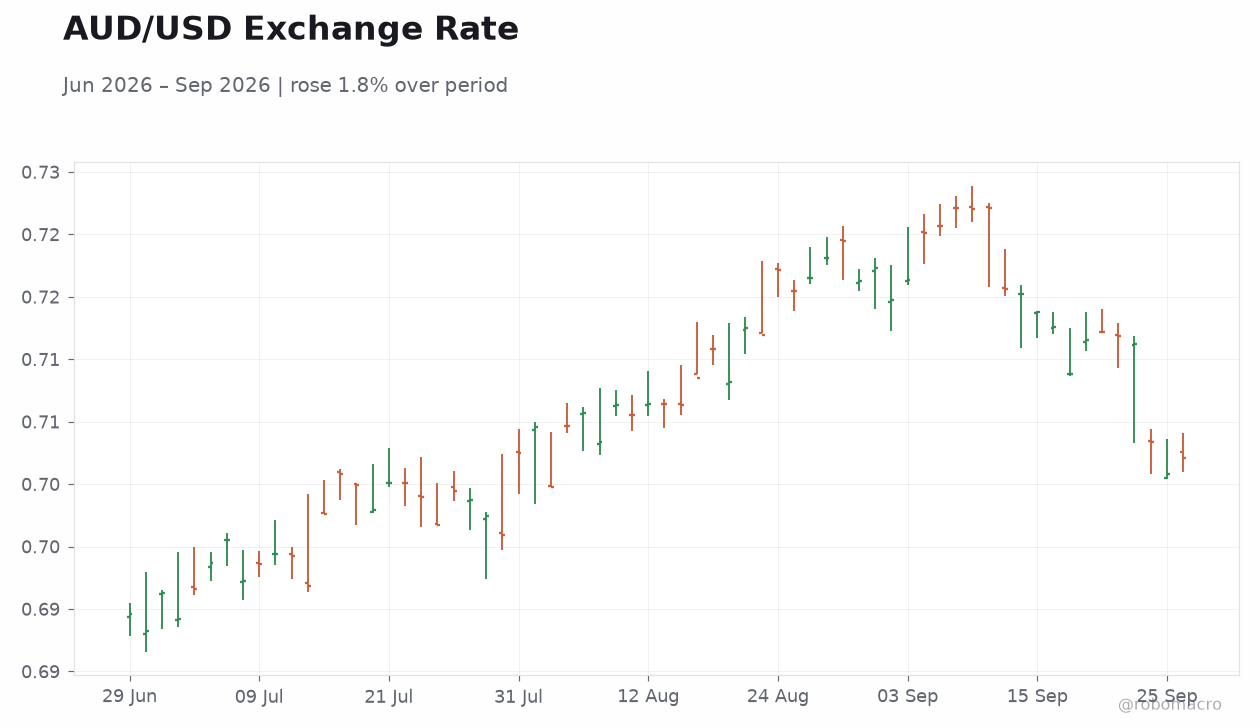
| AUD/USD | 0.70 | +0.18% |
| NZD/USD | 0.57 | +0.21% |
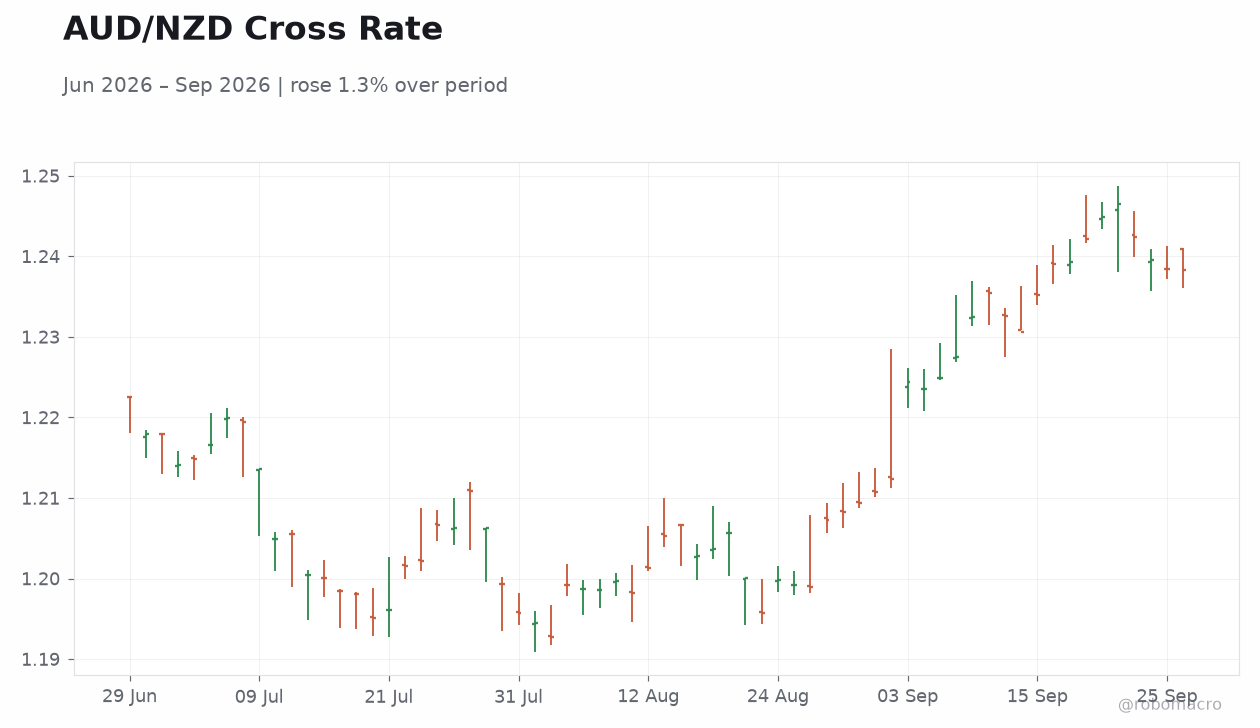
| AUD/NZD | 1.24 | -0.02% |
| BHP | 60.72 | -0.49% |
| Gold | 4,158.40 | -3.77% |
| Brent Crude | 98.08 | -5.98% |
| Bitcoin | 83,372.58 | -1.29% |
| Australia 2Y Govt Yield | 4.95% | -5 bp |
| Australia 10Y Govt Yield | 5.25% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
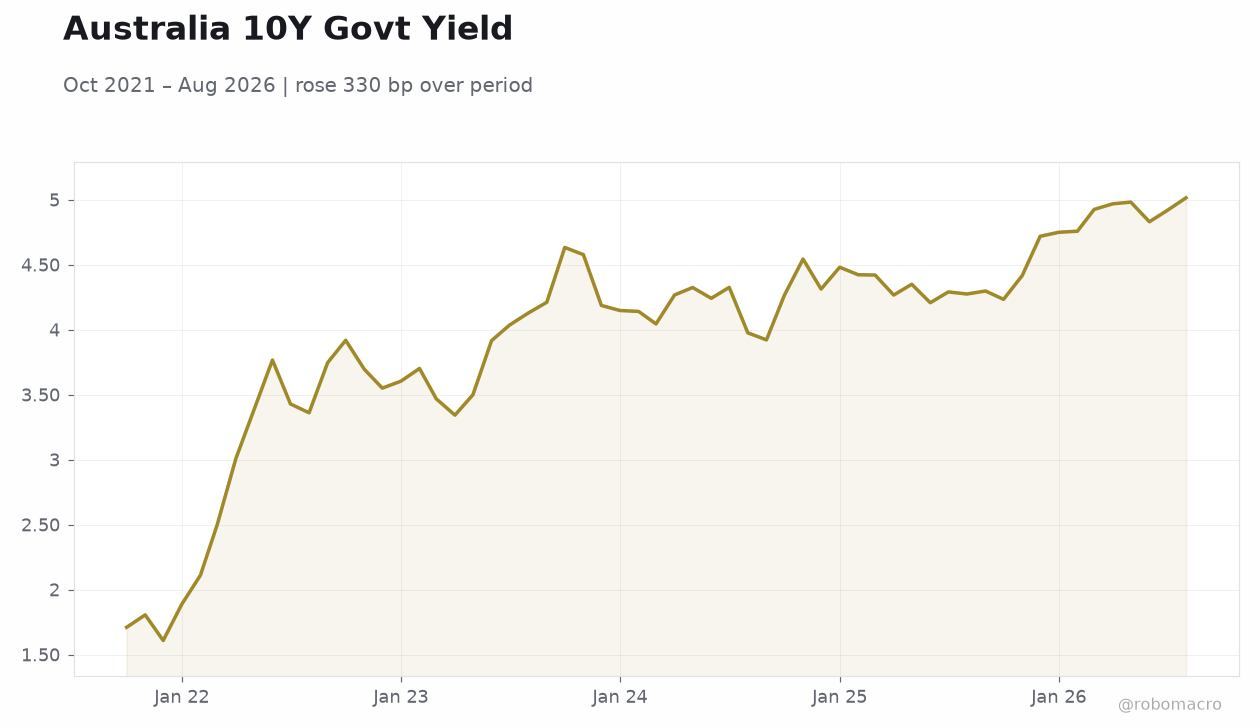 Australia 10Y Govt Yield | Type: macro_line | Yield %: 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.71,3.551,4.141,4.267,4.831,5.015
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| RBA Interest Rate Decision | 4.35 | 4.60 | 20:30 |
| RBA Press Conference | - | - | 21:30 |
| ANZ Business Confidence | 53.70 | - | 16:00 |
| Building Permits Month-over-Month Prel | -3.60 | -0.90 | 17:30 |
| Inflation Rate Month-over-Month | 1 | - | 17:30 |
| Inflation Rate Year-over-Year | 3.50 | 4.10 | 17:30 |
| RBA Trimmed Mean CPI Month-over-Month | 0.50 | - | 17:30 |
| RBA Trimmed Mean CPI Year-over-Year | 3.60 | - | 17:30 |
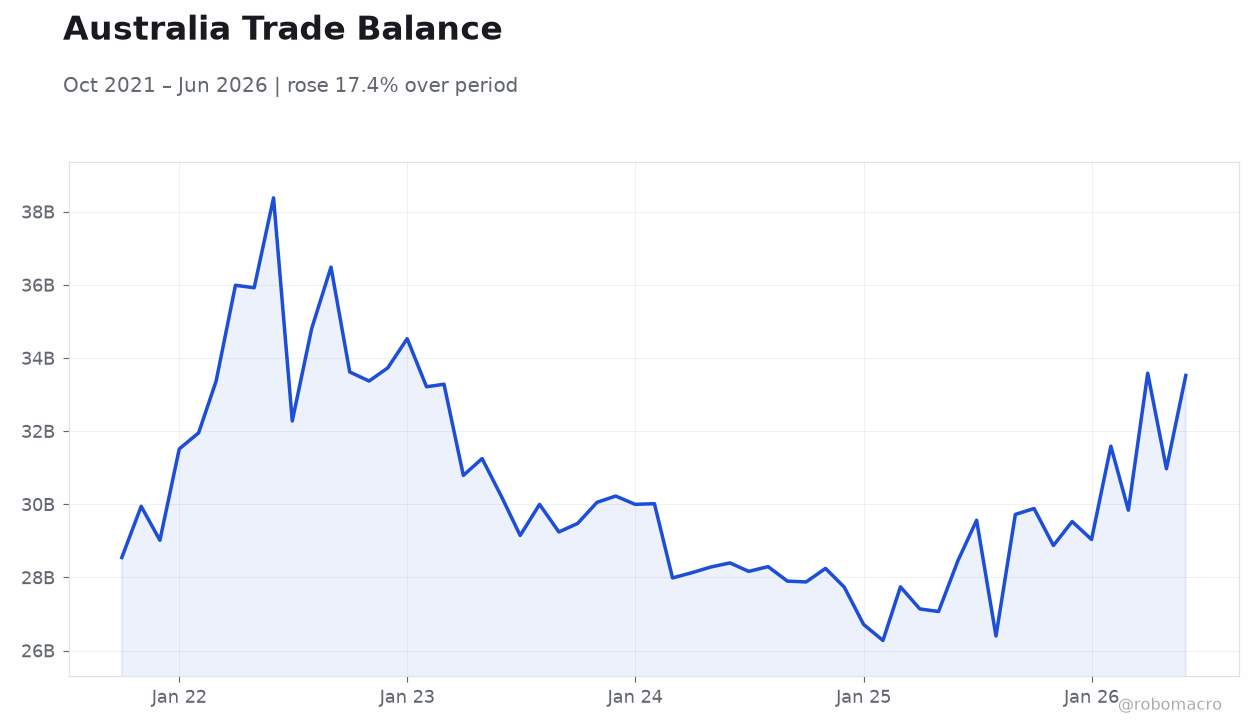
| Trade Balance | 1,923m | 2,100m | 17:30 |
- RBA widely expected to lift cash rate to 4.60% today amid persistent inflation pressures.
- Australian yields fell sharply while ASX 200 declined 0.43% ahead of the decision.
- Housing and growth risks intensify as markets price further tightening from the RBA.
Yesterday's Recap
No economic data releases occurred in Australia or New Zealand on 27 September. The ASX 200 fell 0.43% to 8,665.00 while the NZX 50 rose 0.14% to 13,830.68. AUD/USD advanced 0.18% to 0.70 and NZD/USD gained 0.21% to 0.57.
Australian 2-year yields eased 5 bp to 4.95% and 10-year yields dropped 10 bp to 5.25%. Gold plunged 3.77% to 4,158.40 and Brent crude fell 5.98% to 98.08, weighing on commodity-linked sentiment. BHP declined 0.49% to 60.72 as broader risk appetite softened ahead of the RBA meeting.
Lower gold prices reduce a key support for AUD while the Brent drop signals weaker energy revenue for Australia.
The Day Ahead
Markets focus on the RBA Interest Rate Decision at 20:30 ET, with consensus calling for a 25 bp rise to 4.60% from the current 4.35% level. The subsequent RBA press conference at 21:30 ET will provide fresh guidance on the inflation outlook. Tomorrow brings New Zealand ANZ Business Confidence, Australian building permits, CPI prints including the trimmed-mean measure, and the monthly trade balance.
These releases will test whether inflation has re-accelerated and whether external demand remains supportive for Australia’s commodity exports. Australian inflation data due tomorrow carry high stakes after the prior 3.45% y/y print.
Other Economic Notes
Rising unemployment and elevated borrowing costs are already pressuring household spending and housing turnover. Government employment growth has added to services inflation, complicating the RBA’s task. New Zealand’s milder policy stance leaves the RBNZ with greater room to respond to any global slowdown while Australia’s larger commodity exposure ties its cycle more tightly to China demand.
The RBNZ maintains its 2.75% OCR and has no policy decision scheduled this week. Rebecca Williams was appointed to the RBNZ Monetary Policy Committee, broadening the range of views on the inflation-targeting framework.