ANZ Macro Daily(Beta Mode)
RBA Hikes to 15-Year High, AUD Gains vs NZD
Market Snapshot
| Asset | Level | Change |
|---|---|---|
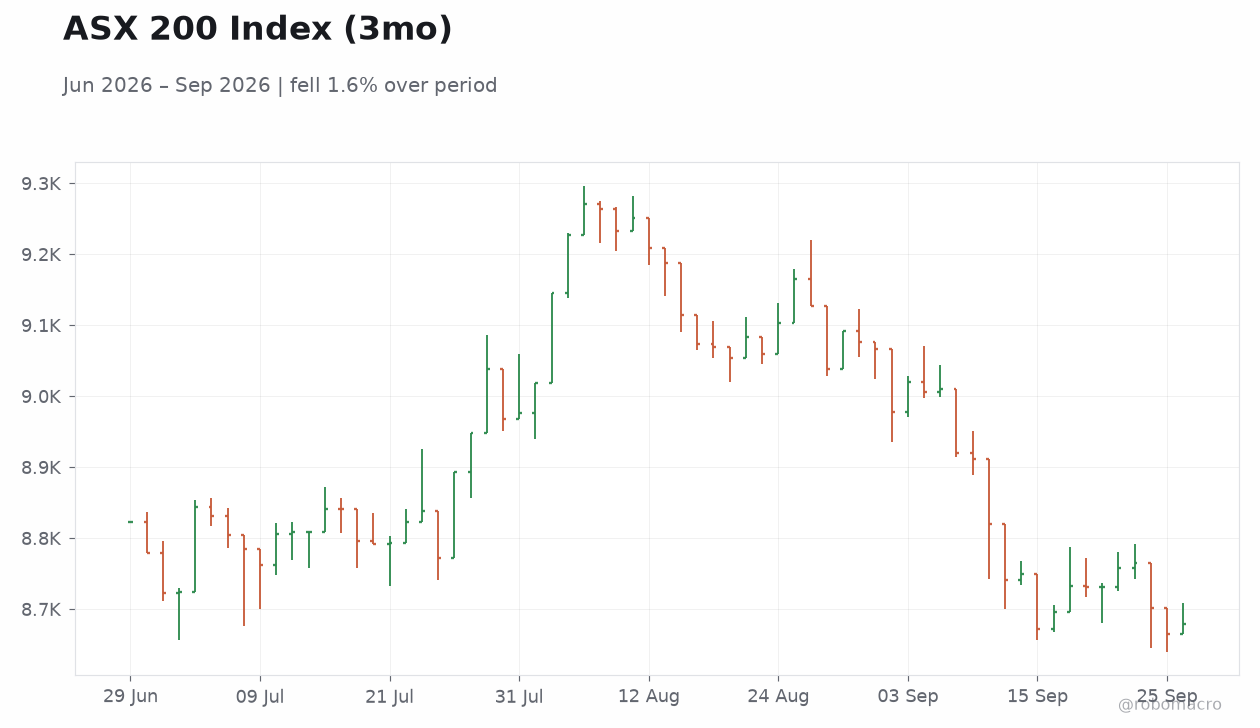
| ASX 200 | 8,679.70 | +0.17% |
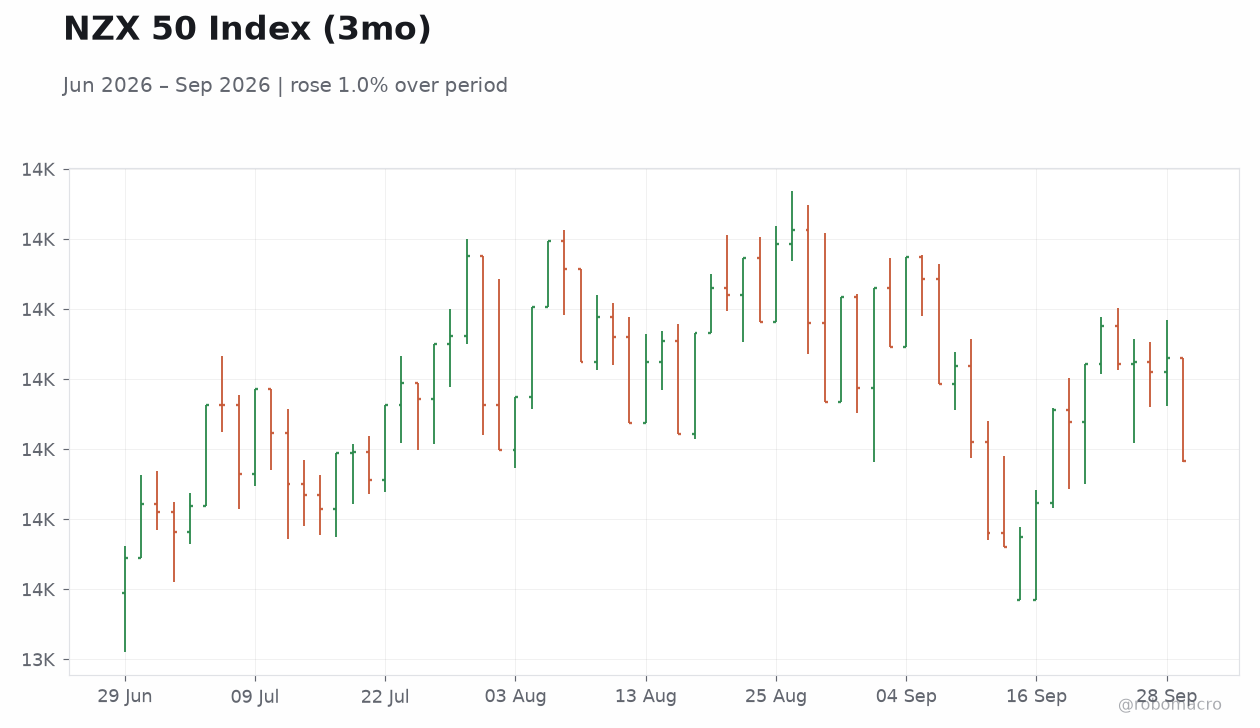
| NZX 50 | 13,683.63 | -1.06% |
| AUD/USD | 0.70 | -0.29% |
| NZD/USD | 0.56 | -0.17% |
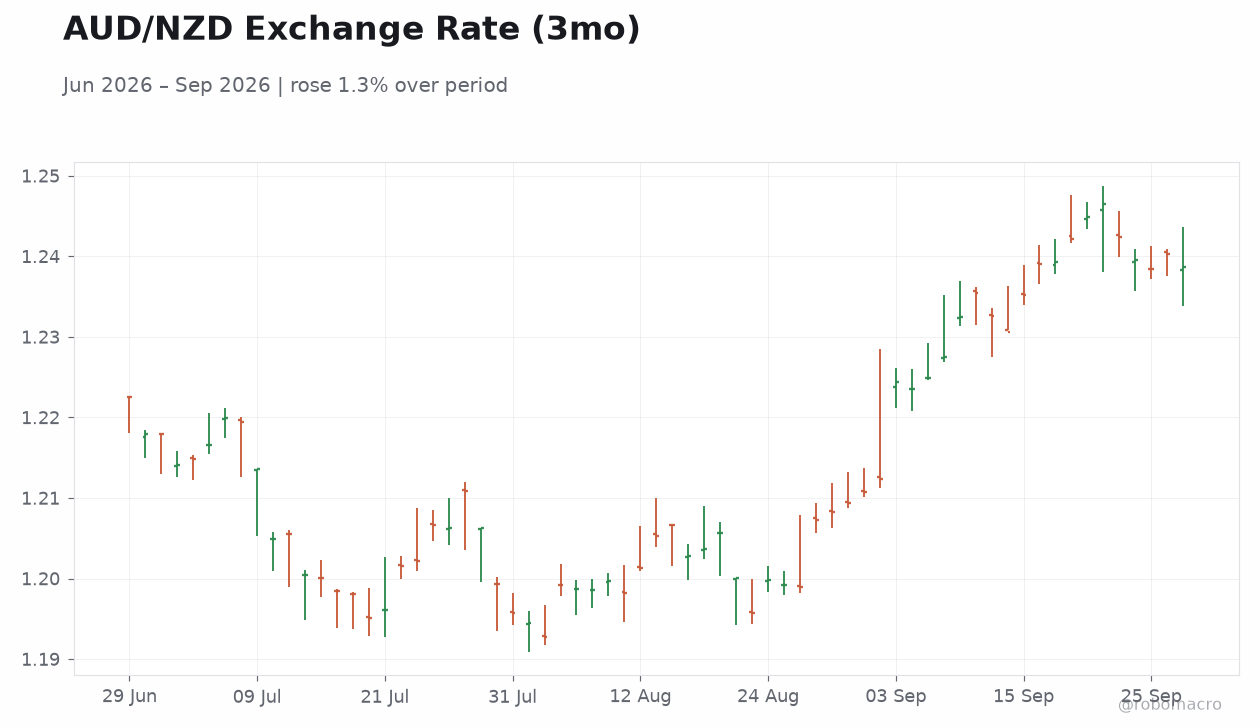
| AUD/NZD | 1.24 | +0.15% |
| BHP | 60.63 | +1.39% |
| Gold | 4,202.70 | +0.82% |
| Brent Crude | 95.97 | -8.84% |
| Bitcoin | 83,571.85 | +0.08% |
| Australia 2Y Govt Yield | 4.95% | -5 bp |
| Australia 10Y Govt Yield | 5.25% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBA Interest Rate Decision | 4.35 | 4.60 | 4.60 |
| RBA Press Conference | - | - | - |
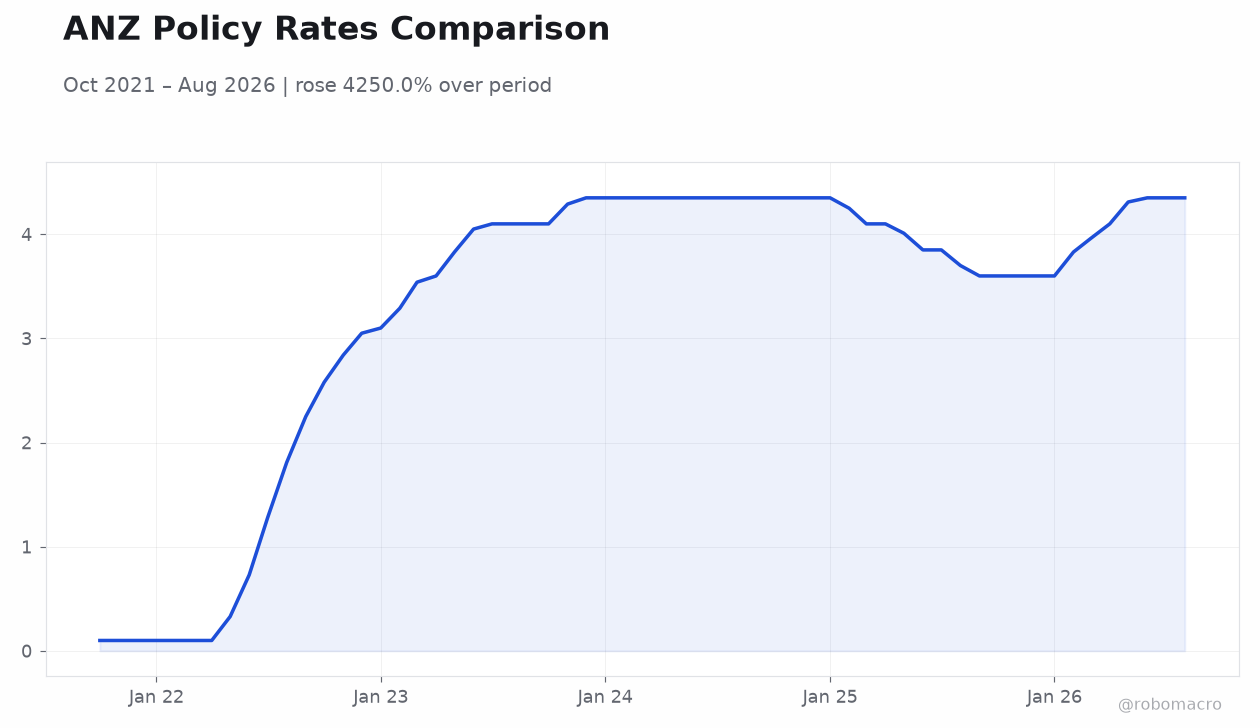
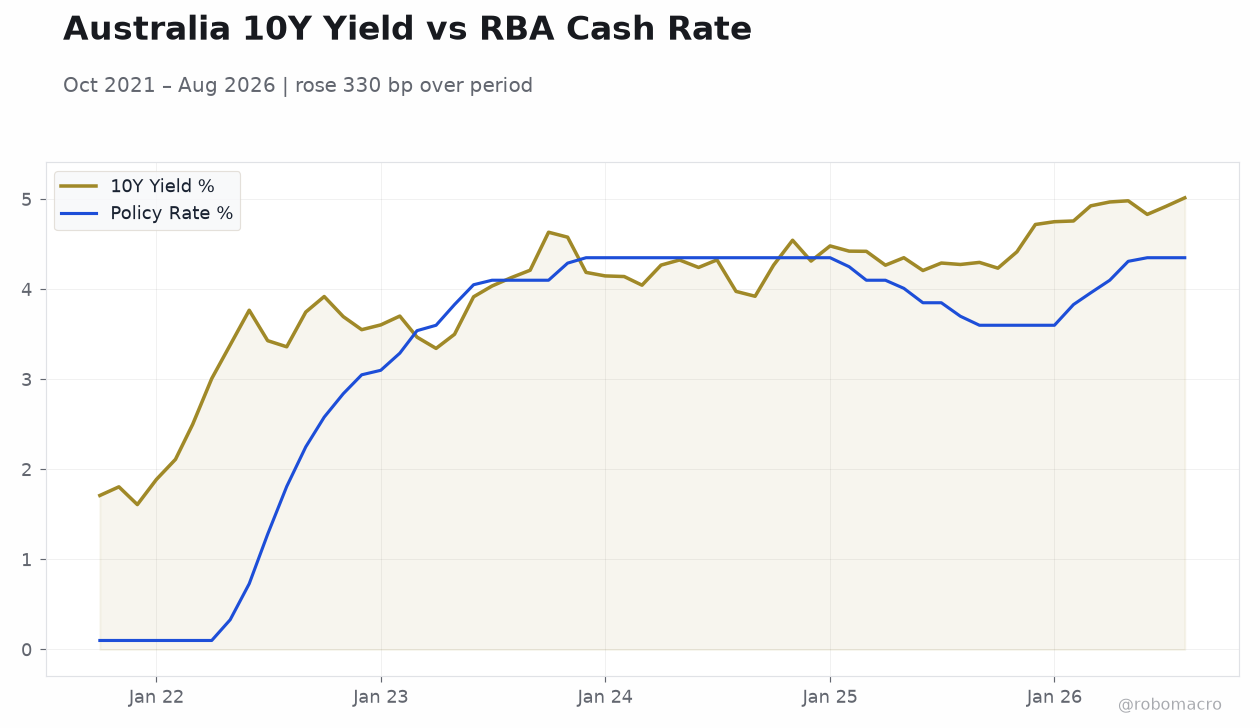 Australia 10Y Yield vs RBA Cash Rate | Type: macro_line | 10Y Yield %: 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.71,3.551,4.141,4.267,4.831,5.015 | Policy Rate %: 4.35 (2026-08-01) | Range: 0.1–4.35 | Trend(5pt): 0.1,3.05,4.35,4.1,4.35
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| ANZ Business Confidence | 53.70 | - | 16:00 |
| Building Permits Month-over-Month Prel | -3.60 | -0.90 | 17:30 |
| Inflation Rate Month-over-Month | 1 | 0.40 | 17:30 |
| Inflation Rate Year-over-Year | 3.50 | 4 | 17:30 |
| RBA Trimmed Mean CPI Month-over-Month | 0.50 | 0.30 | 17:30 |
| RBA Trimmed Mean CPI Year-over-Year | 3.60 | 3.60 | 17:30 |
- RBA lifts cash rate 25 bp to 4.60 %, highest since 2011, lifting AUD versus NZD.
- Australian yields fall after the decision while ASX 200 edges higher and NZX 50 declines.
- Australian inflation prints and building permits due today; NZ ANZ Business Confidence also scheduled.
Yesterday's Recap
The RBA raised the cash rate 25 bp to 4.60 % at its 28 September meeting, matching consensus and marking the highest policy rate in 15 years. Markets responded with the ASX 200 closing 0.17 % higher at 8,679.70 while the NZX 50 fell 1.06 % to 13,683.63. AUD/USD eased 0.29 % to 0.70 and NZD/USD slipped 0.17 % to 0.56, yet AUD/NZD advanced 0.15 % to 1.24 as the RBA’s tightening contrasted with RBNZ inaction.
Australian 2-year yields declined 5 bp to 4.95 % and 10-year yields fell 10 bp to 5.25 %. BHP rose 1.39 % to 60.63, supporting the broader equity tone, while gold advanced 0.82 % to 4,202.70 and Brent crude dropped 8.84 % to 95.97. The RBA press conference reinforced the committee’s focus on persistent inflation pressures without signalling further near-term steps.
The Day Ahead
Australian inflation data headline today’s calendar, with CPI month-over-month, year-over-year, and trimmed-mean measures all due at 17:30 ET alongside preliminary building permits. New Zealand releases ANZ Business Confidence at 16:00 ET, providing an early read on sentiment after the RBA’s move. Tomorrow brings Australia’s trade balance at 17:30 ET, expected to widen modestly on commodity shipments.
Markets will watch whether today’s CPI prints alter expectations for further RBA tightening or confirm the recent hike as sufficient. Housing-related data such as building permits will also highlight sensitivity to higher borrowing costs in both countries.
Other Economic Notes
Australia’s commodity-export model remains tightly linked to Chinese demand, with iron ore, coal, LNG and gold flows driving AUD volatility. BHP’s outperformance yesterday underscored mining-sector resilience despite softer Brent prices. New Zealand’s dairy and tourism sectors face different cyclical pressures, with construction activity sensitive to RBNZ policy settings.
Housing markets in both countries continue to absorb higher rates, with Australian mortgage costs now at multi-year peaks and New Zealand household debt metrics still elevated. External risks centre on China’s growth trajectory and any spillover to global commodity prices.