ANZ Macro Daily(Beta Mode)
RBA Hikes to 15-Year High Amid Cooling CPI
Market Snapshot
| Asset | Level | Change |
|---|---|---|
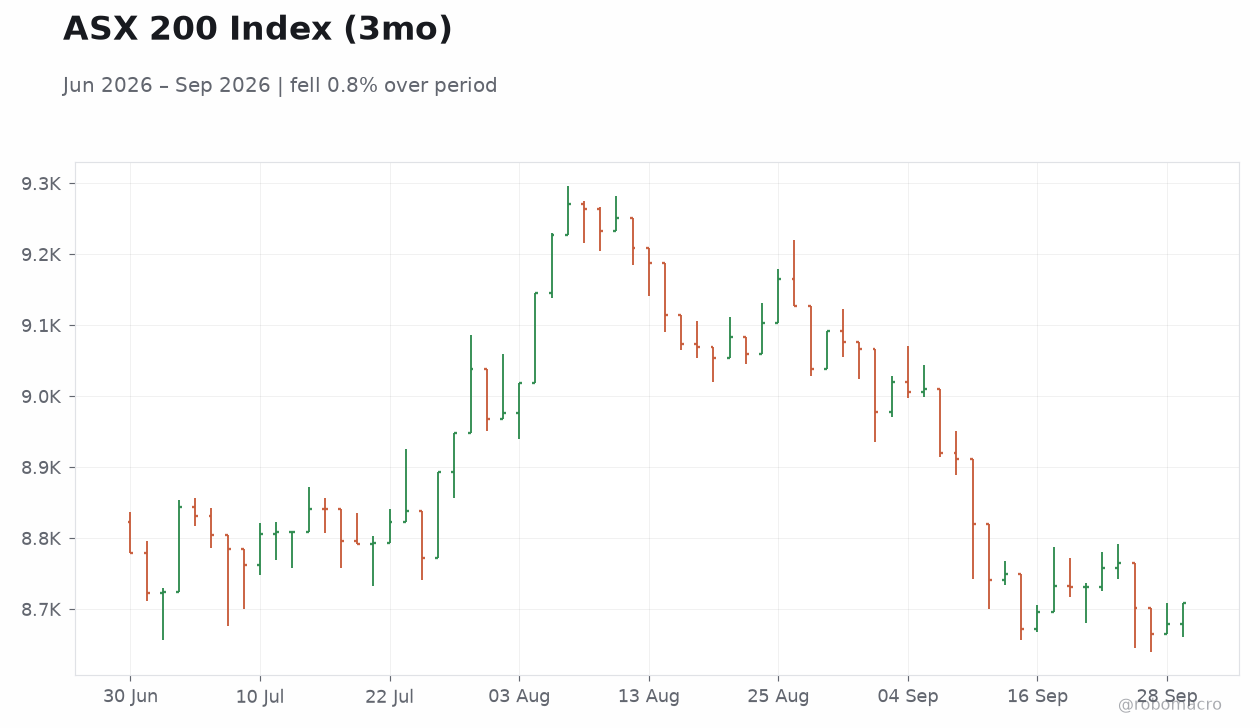
| ASX 200 | 8,709.30 | +0.34% |
| NZX 50 | 13,834.39 | +1.10% |
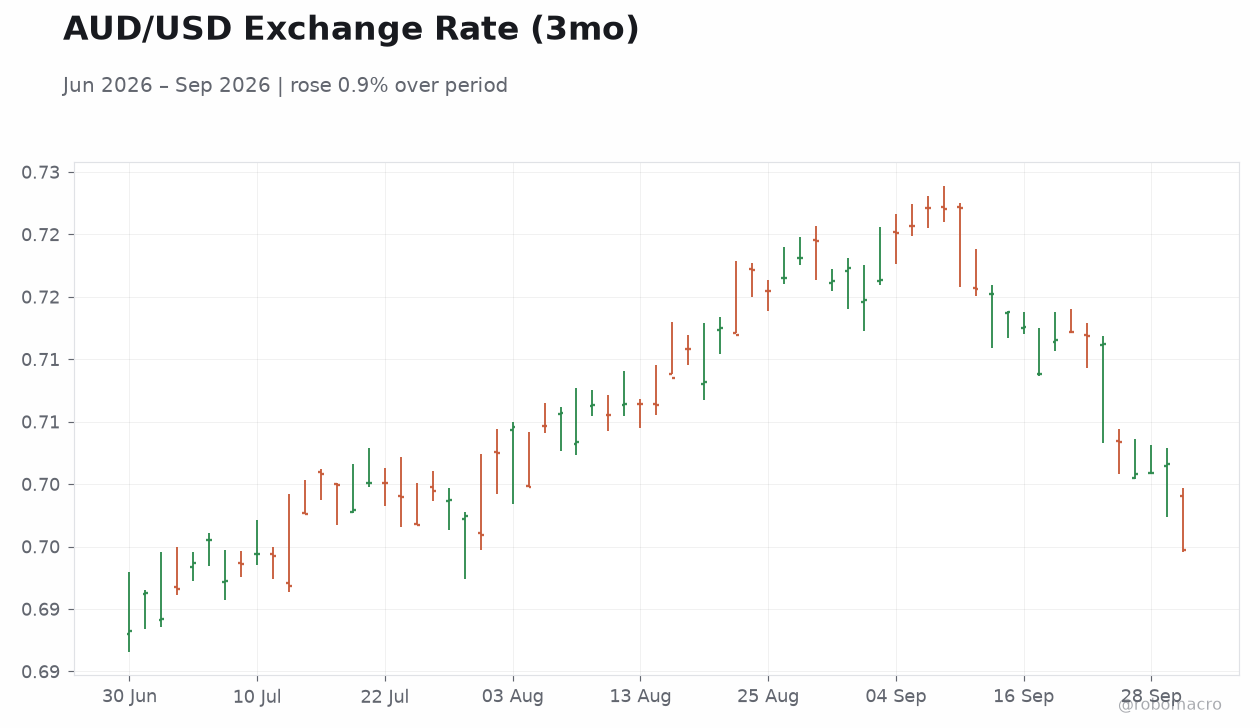
| AUD/USD | 0.69 | -0.98% |
| NZD/USD | 0.56 | -0.50% |
| AUD/NZD | 1.23 | -0.50% |
| BHP | 60.82 | +0.31% |
| Gold | 4,185.00 | +0.13% |
| Brent Crude | 98.02 | -4.45% |
| Bitcoin | 83,563.58 | -0.07% |
| Australia 2Y Govt Yield | 4.95% | -5 bp |
| Australia 10Y Govt Yield | 5.25% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBA Interest Rate Decision | 4.35 | 4.60 | 4.60 |
| RBA Press Conference | - | - | - |
| ANZ Business Confidence | 53.70 | - | 51.90 |
| Building Permits Month-over-Month Prel | -1.90 | -2 | -6.10 |
| Inflation Rate Month-over-Month | 1 | 0.50 | 0.40 |
| Inflation Rate Year-over-Year | 3.50 | 4.10 | 4 |
| RBA Trimmed Mean CPI Month-over-Month | 0.50 | 0.30 | 0.20 |
| RBA Trimmed Mean CPI Year-over-Year | 3.60 | 3.60 | 3.60 |
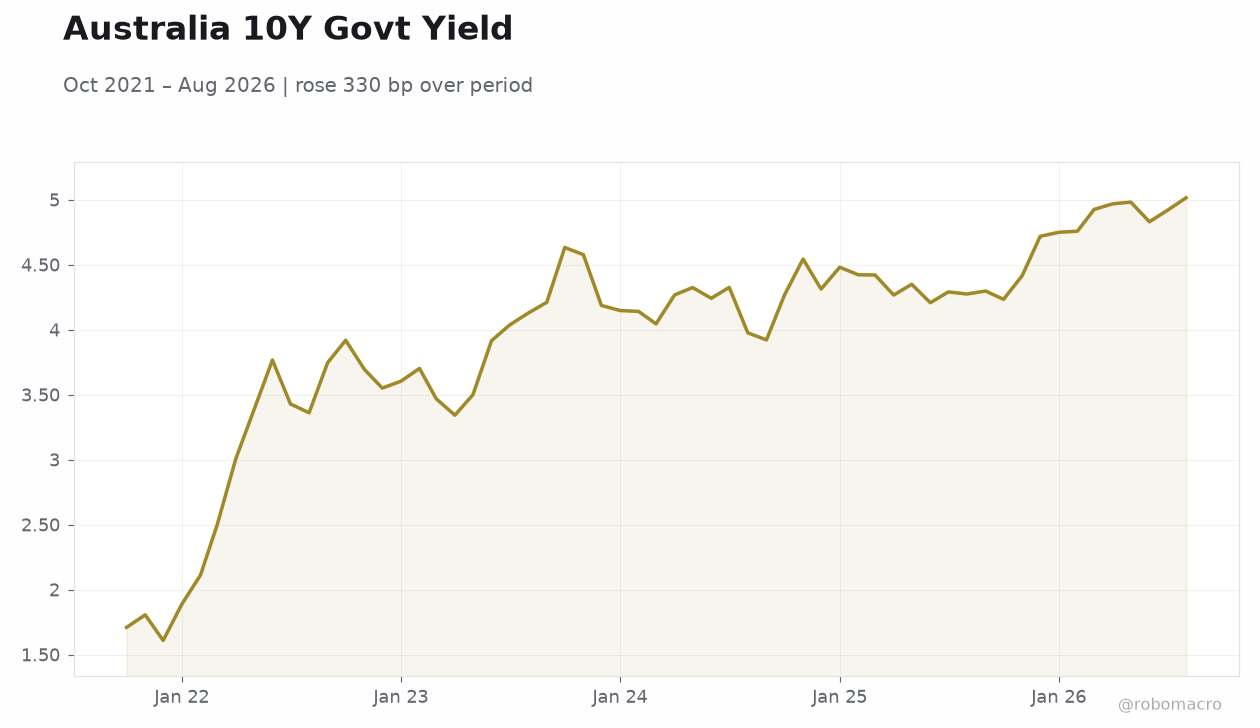 Australia 10Y Govt Yield | Type: macro_line | Percent: 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.71,3.551,4.141,4.267,4.831,5.015
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | 1,923m | 2,000m | 17:30 |
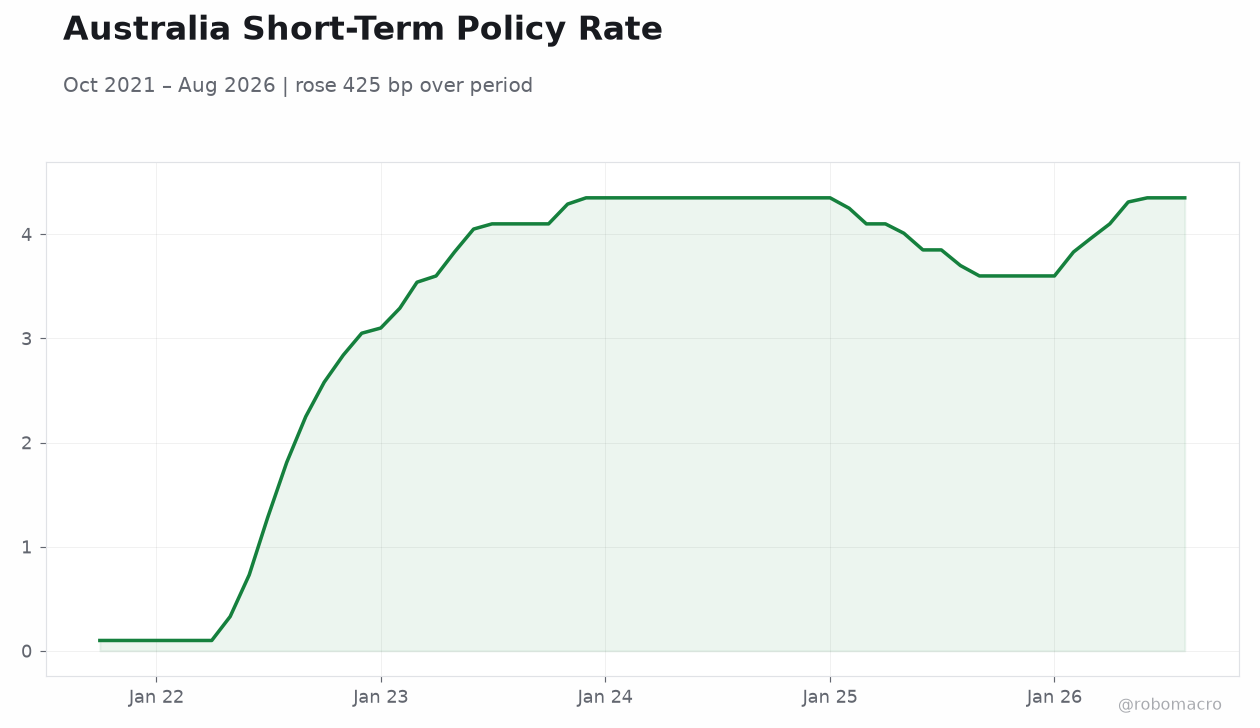
- RBA lifts cash rate 25 bp to 4.60%, matching consensus and marking the highest level in 15 years.
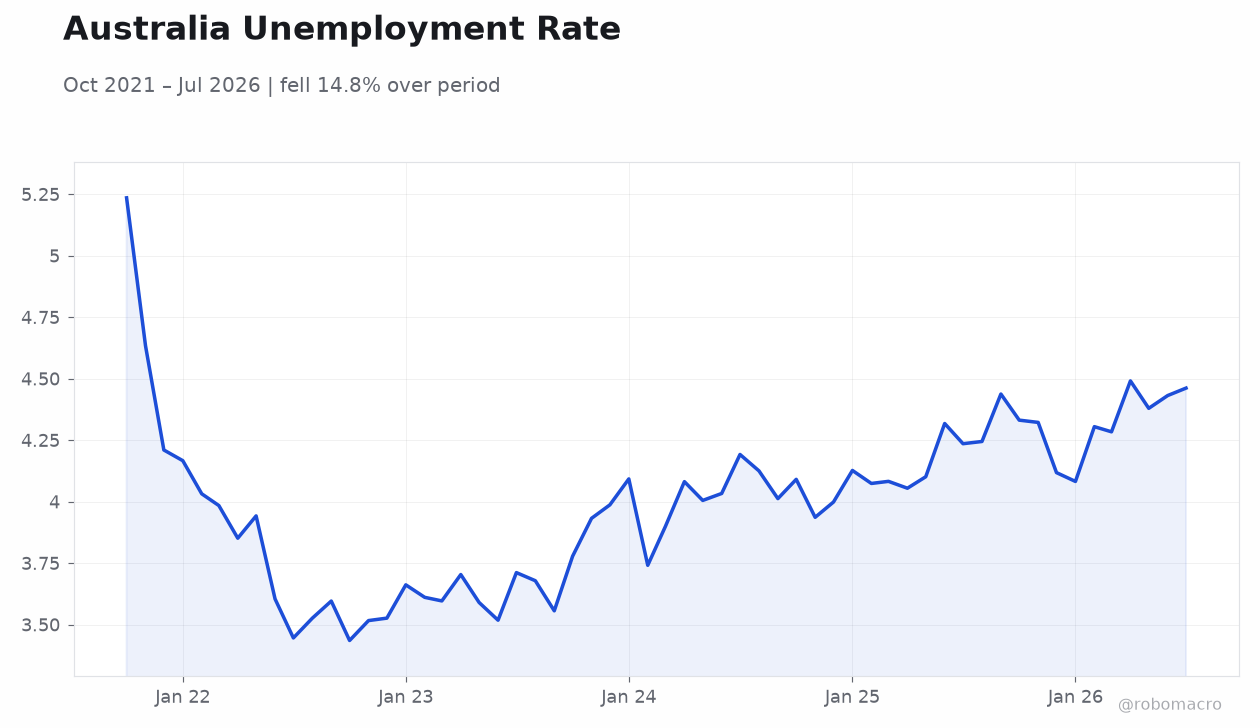
- Australian CPI eases to 4.0% y/y and 0.4% m/m, with trimmed mean holding at 3.6% y/y.
- ASX 200 gains 0.34% while AUD/USD falls 0.98% to 0.69 after the policy decision.
Yesterday's Recap
The RBA raised the cash rate 25 bp to 4.60% at its 28 September meeting, aligning with consensus and lifting the policy rate to its highest level in 15 years. Australian headline CPI printed 4.0% y/y and 0.4% m/m, both below expectations, while the trimmed-mean measure held at 3.6% y/y and 0.2% m/m. Building permits plunged 6.1% m/m, well below the -2.0% consensus.
In New Zealand, ANZ Business Confidence fell to 51.9 from 53.7. Equity markets advanced, with the ASX 200 rising 0.34% to 8,709.30 and the NZX 50 climbing 1.10% to 13,834.39. The AUD/USD dropped 0.98% to 0.69 and the NZD/USD eased 0.50% to 0.56, while Australian 10-year yields fell 10 bp to 5.25% and 2-year yields declined 5 bp to 4.95%.
Brent crude tumbled 4.45% to 98.02 amid the policy shift. The combination of firmer policy and softer inflation data points to a potential pause in tightening, with housing-sector weakness evident in the permits print.
The Day Ahead
Australia releases the August trade balance at 17:30 ET, with consensus pointing to a A$2.0 bn surplus versus the prior A$1.923 bn. No RBA or RBNZ events are scheduled. Markets will monitor any follow-up comments from RBA Governor Bullock after yesterday’s press conference.
New Zealand data are absent from the calendar. Attention remains on commodity price reactions and any China demand signals that could influence AUD and NZD flows. The sharp Brent decline may ease imported-energy costs for both economies, though sustained weakness risks pressuring Australia’s terms of trade via LNG and coal linkages.
Other Economic Notes
Cooling Australian inflation prints alongside the RBA’s latest hike suggest the tightening cycle may be nearing its end. Building-permit weakness highlights downside risks in the housing sector, a key transmission channel for both the RBA and RBNZ. New Zealand’s softer business-confidence reading adds to evidence of moderating domestic demand.
Commodity exporters face mixed signals as Brent’s sharp drop eases imported-energy costs but could pressure terms of trade if iron-ore and coal prices follow. ↓ p.2