ANZ Macro Daily(Beta Mode)
RBA Hikes to 4.6% as AU Inflation Cools
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| ASX 200 | 8,789.30 | +0.92% |
| NZX 50 | 13,810.51 | -0.17% |
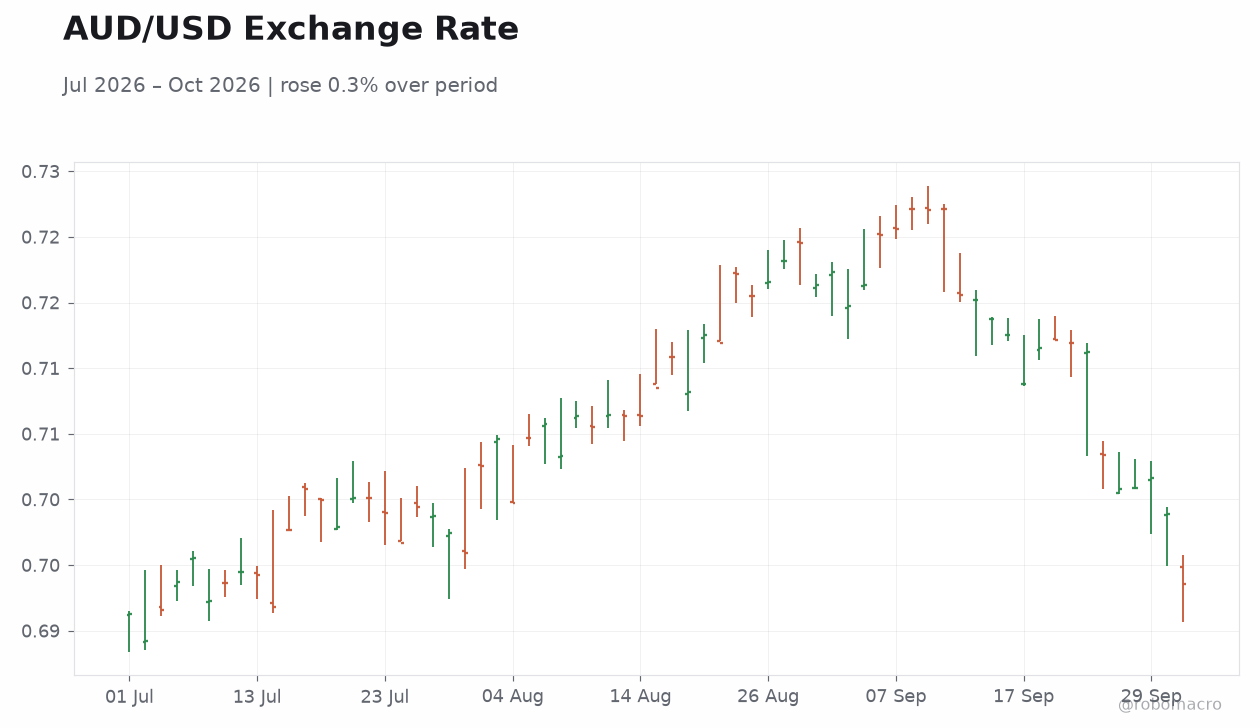
| AUD/USD | 0.69 | -0.80% |
| NZD/USD | 0.56 | -0.59% |
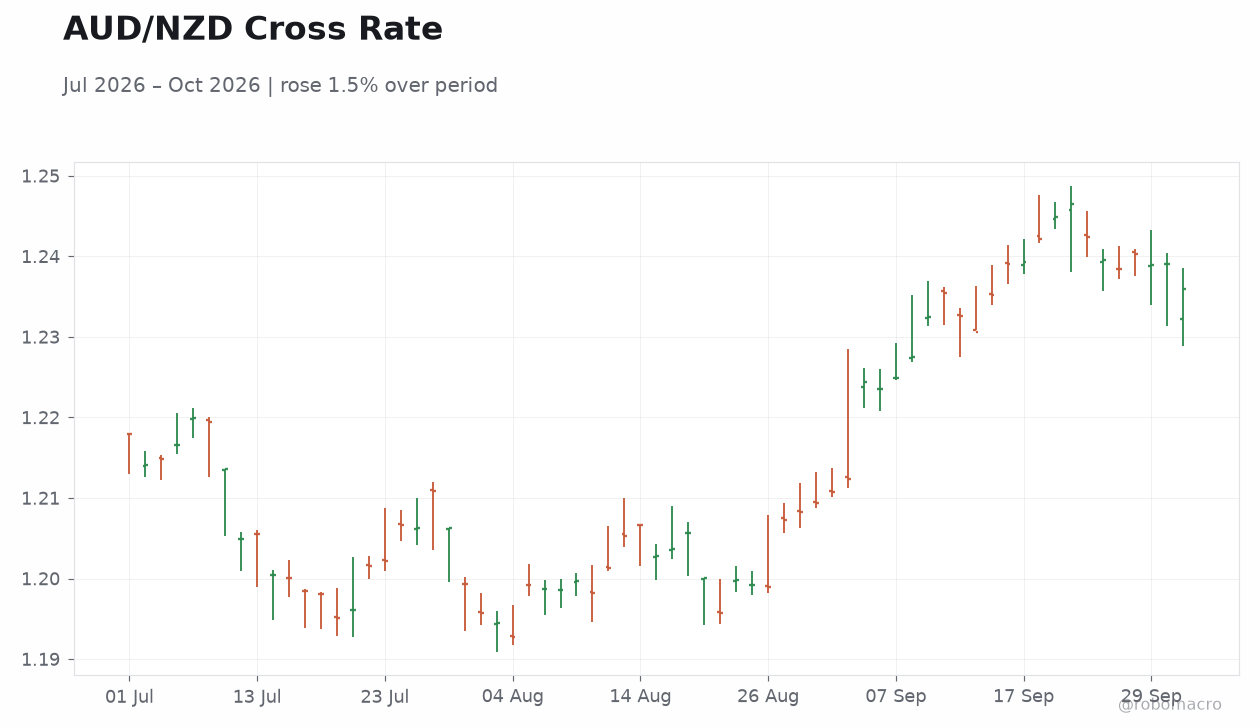
| AUD/NZD | 1.24 | -0.24% |
| BHP | 60.26 | -0.92% |
| Gold | 4,209.10 | +0.54% |
| Brent Crude | 102.45 | -1.04% |
| Bitcoin | 84,725.09 | +1.40% |
| Australia 2Y Govt Yield | 4.95% | -5 bp |
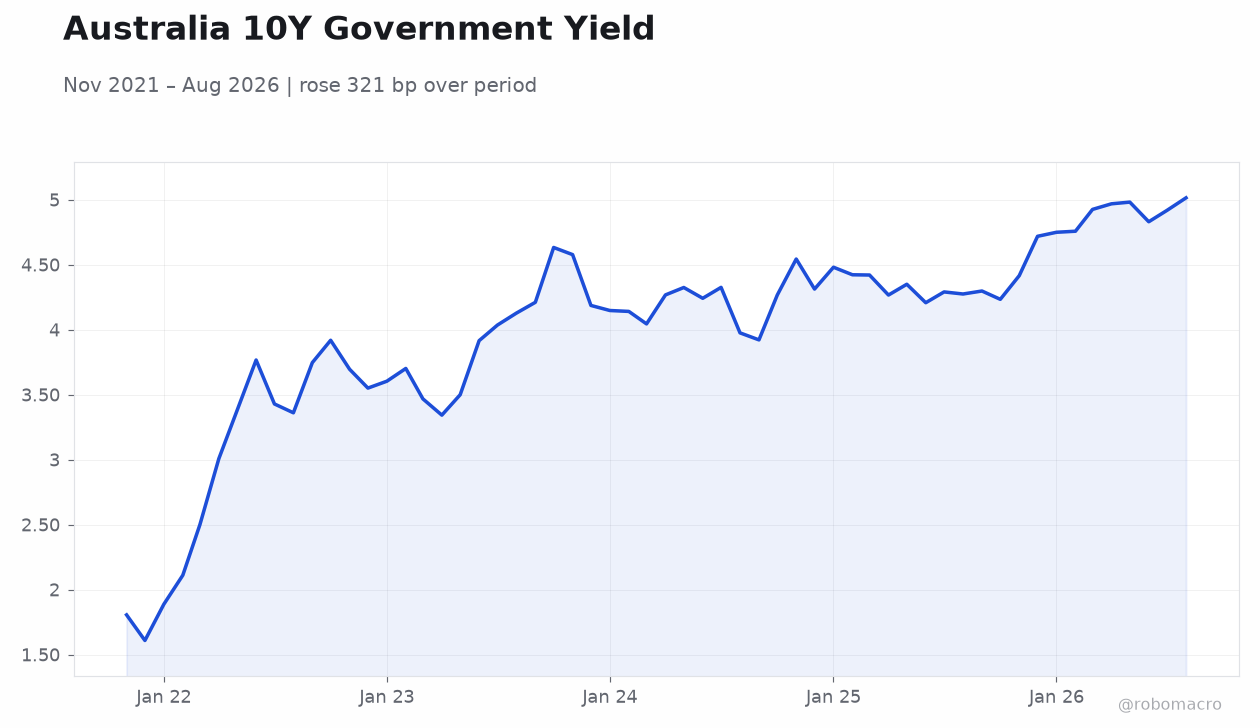
| Australia 10Y Govt Yield | 5.25% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBA Interest Rate Decision | 4.35 | 4.60 | 4.60 |
| RBA Press Conference | - | - | - |
| ANZ Business Confidence | 53.70 | - | 51.90 |
| Building Permits Month-over-Month Prel | -1.90 | -2 | -6.10 |
| Inflation Rate Month-over-Month | 1 | 0.50 | 0.40 |
| Inflation Rate Year-over-Year | 3.50 | 4.10 | 4 |
| RBA Trimmed Mean CPI Month-over-Month | 0.50 | 0.30 | 0.20 |
| RBA Trimmed Mean CPI Year-over-Year | 3.60 | 3.60 | 3.60 |
| Trade Balance | 1,351m | 2,000m | 495m |
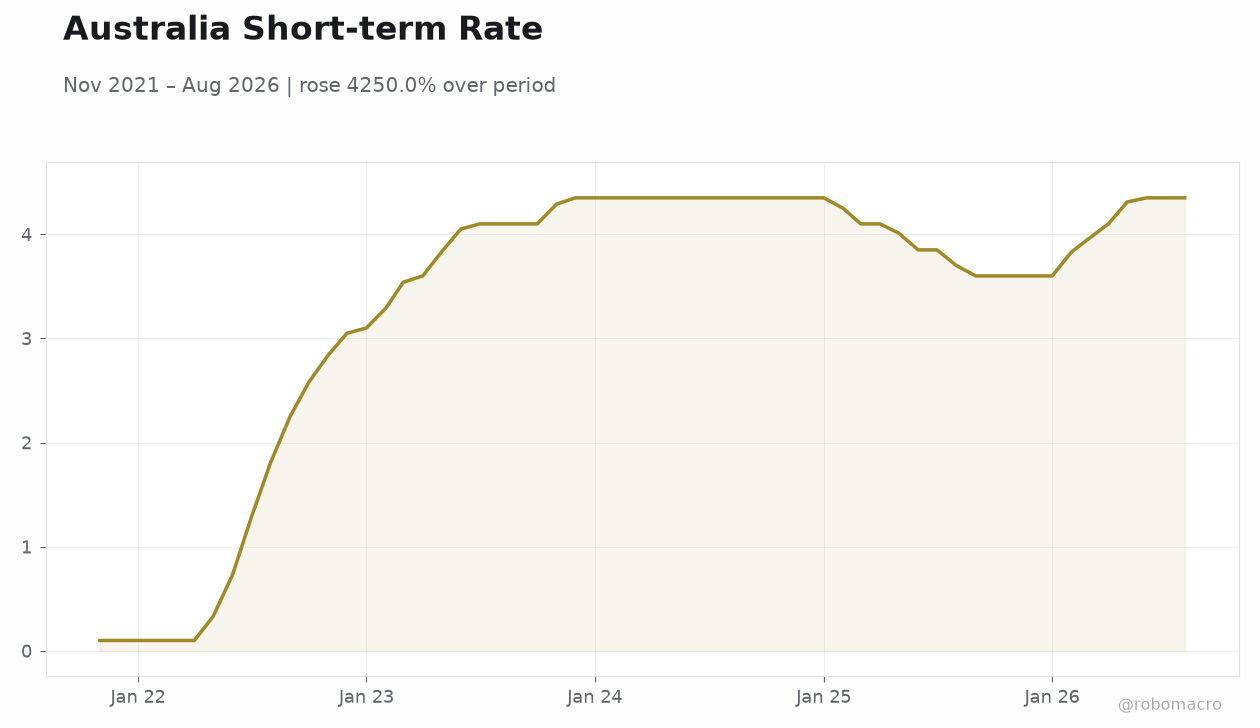 Australia Short-term Rate | Type: macro_line | Rate %: 4.35 (2026-08-01) | Range: 0.1–4.35 | Trend(5pt): 0.1,3.1,4.35,4.01,4.35
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- RBA lifted cash rate 25 bp to 4.6% while Australian CPI YoY eased to 4.0% and trade balance missed forecasts sharply.
- ASX 200 rose 0.92% to 8,789.30 as yields fell, but AUD/USD dropped 0.80% to 0.69 on stronger US data.
- NZ ANZ Business Confidence slipped to 51.9; NZX 50 edged 0.17% lower amid ongoing house-price weakness.
Yesterday's Recap
The RBA raised the cash rate to 4.6% from 4.35% and held a press conference, citing persistent inflation risks despite the move. Australian headline CPI rose 0.4% MoM and 4.0% YoY in August, both below consensus, while the trimmed-mean measure printed 0.2% MoM and 3.6% YoY. Building permits fell 6.1% MoM, far worse than the -2.0% expected.
New Zealand’s ANZ Business Confidence declined to 51.9 from 53.7. Australia’s September trade balance printed A$495 million versus a A$2 billion consensus. The ASX 200 gained 0.92% while the 10-year government yield eased 10 bp to 5.25% and the 2-year yield fell 5 bp to 4.95%.
AUD/USD declined 0.80% to 0.69 as higher global yields outweighed the RBA decision. NZD/USD fell 0.59% to 0.56 and AUD/NZD eased 0.24% to 1.24. BHP declined 0.92% to 60.26.
Gold rose 0.54% to 4,209.10 while Brent Crude fell 1.04% to 102.45.
The Day Ahead
No Australian or New Zealand data releases, RBA or RBNZ meetings, or bond auctions are scheduled for 1–2 October. Markets will monitor Chinese manufacturing PMI due early next week for commodity-demand signals. The absence of fresh domestic prints leaves focus on global risk sentiment and US data.
AUD and NZD will remain sensitive to Treasury-yield moves and any China stimulus commentary. Equity and commodity traders await any follow-through from yesterday’s RBA communications. Bitcoin rose 1.40% to 84,725.09 with limited immediate macro implications for the region.
Other Economic Notes
Softer Australian inflation prints and the weak trade outcome reduce the chance of further RBA tightening in the near term. Building-permit weakness points to slower construction activity ahead, weighing on related employment. New Zealand house prices have fallen to the lowest level since early 2021, extending the slump that began in 2022 and pressuring household balance sheets.
Commodity-export revenues remain the dominant channel linking Australian growth to Chinese demand, with BHP serving as the key equity bellwether. ↓ p.2