RoboMacro ResearchAlso todaySee the FX Daily

ANZ Macro Daily(Beta Mode)

October 06, 2026 robomacro.com

Aussie Confidence Slumps, RBA in Focus

-4.70 Westpac Consumer80.40 Westpac Consumer
ASX 2008,735.70+0.57%
NZX 5013,700.12+0.01%
AUD/USD0.70+0.49%
NZD/USD0.56+0.15%

Market Snapshot

AssetLevelChange
ASX 2008,735.70+0.57%
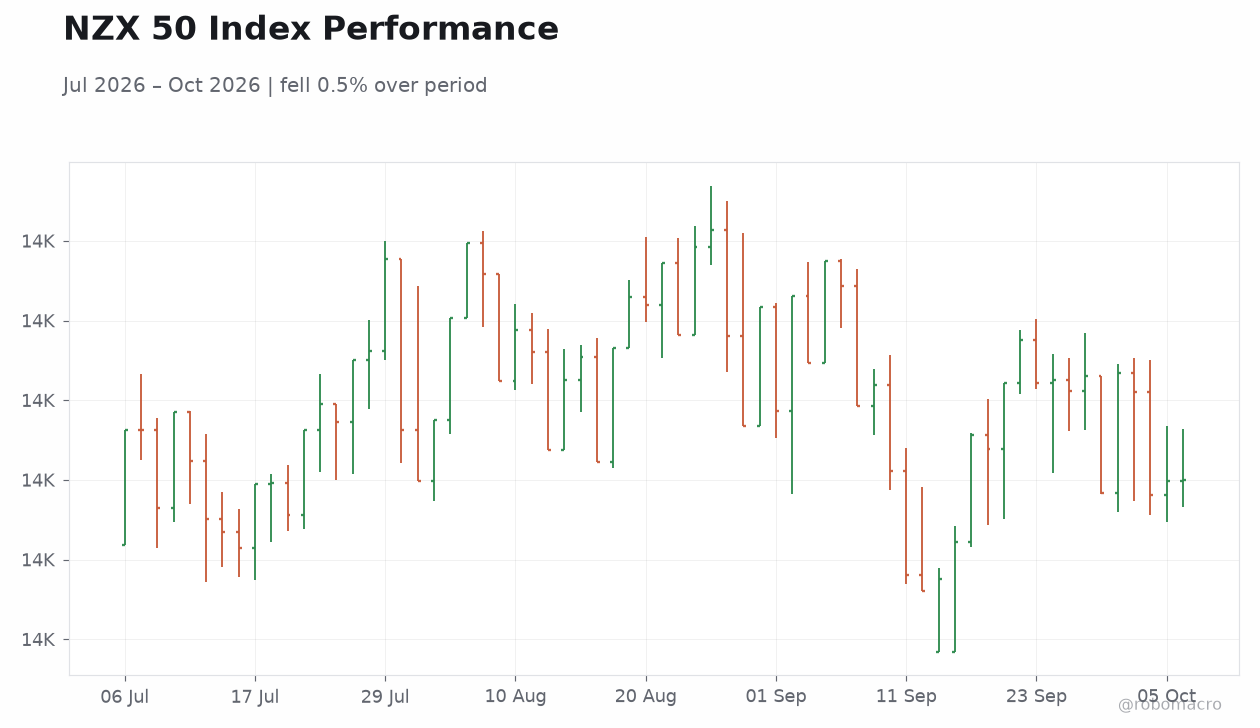
NZX 5013,700.12+0.01%
AUD/USD0.70+0.49%
NZD/USD0.56+0.15%
AUD/NZD1.24+0.55%
BHP62.86+1.57%
Gold4,195.00+0.92%
Brent Crude100.98+0.66%
Bitcoin85,614.09-0.20%
Australia 2Y Govt Yield--
Australia 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
Westpac Consumer Confidence Change-5.20--4.70
Westpac Consumer Confidence Index84.40-80.40
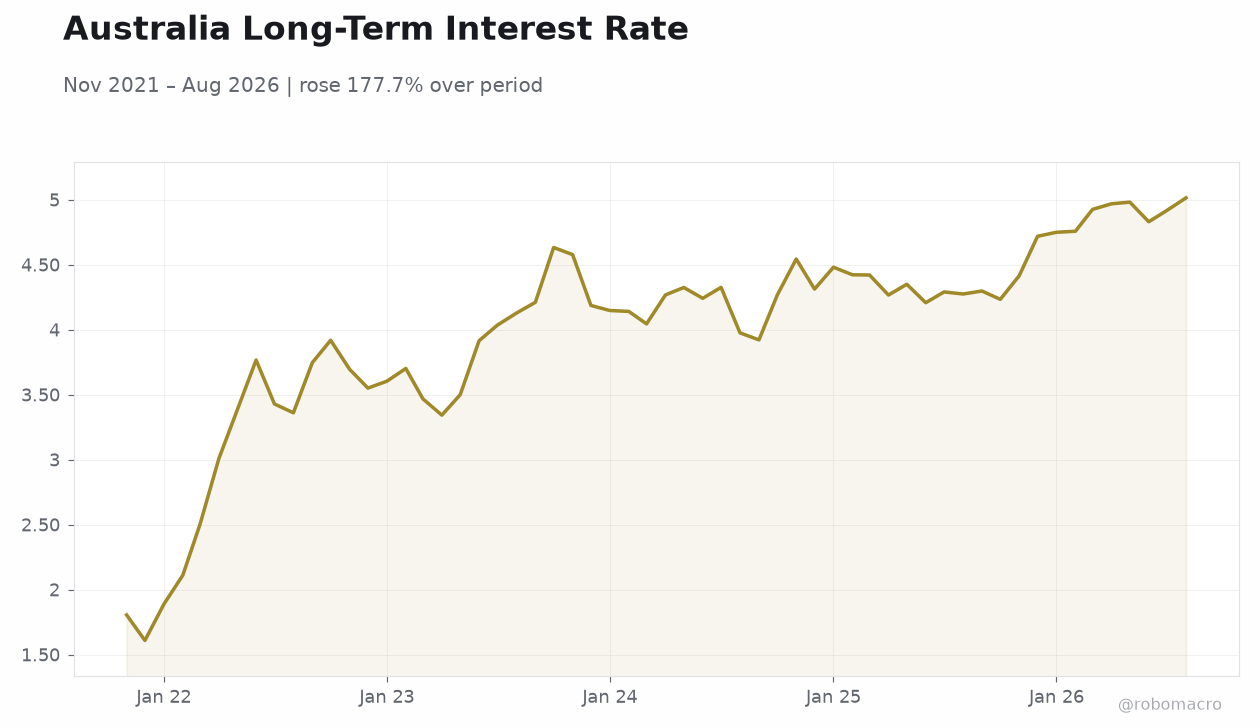
Australia Long-Term Interest RateAustralia Long-Term Interest Rate | Type: macro_line | 10Y Yield (%): 5.015 (2026-08-01) | Range: 1.609–5.015 | Trend(6pt): 1.806,3.604,4.045,4.35,4.919,5.015

Today's Economic Events

Data Prior Cons Time
Ai Group Industry Index-3.50-18:00
  • Australian consumer confidence deteriorated further, with Westpac's index falling to 80.4, extending losses as households absorb the impact of restrictive policy settings.
  • The AUD firmed 0.49% against the USD while the ASX 200 advanced 0.57%, led by a 1.57% gain in BHP on commodity strength.
  • Attention turns to today's Ai Group Industry Index, with markets continuing to parse the RBA's policy trajectory amid sticky inflation near 4%.

Yesterday's Recap

Australian sentiment data dominated yesterday's calendar. The Westpac Consumer Confidence Change printed at -4.7%, a smaller decline than the prior -5.2% reading but still a further contraction, leaving the headline index at a deeply subdued 80.4 — well below the 100 neutral mark that separates optimism from pessimism. The persistent sub-100 readings underscore the toll that elevated borrowing costs and a softening labour market are taking on household sentiment, with mortgage holders still digesting the cumulative tightening cycle.

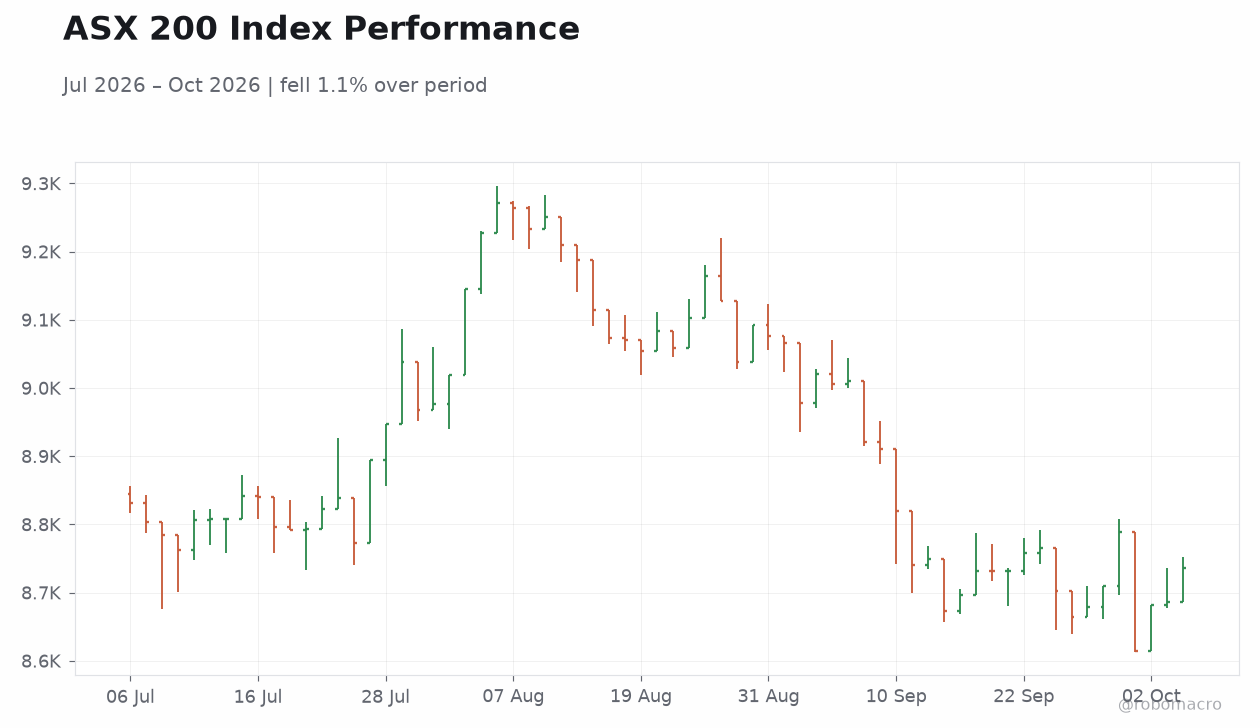
The weakness was broad-based across the subindices, reflecting gloom on both family finances and the economic outlook. Equity markets, however, looked through the gloom: the ASX 200 climbed 0.57% to 8,735.70, with BHP's 1.57% rally to 62.86 providing the standout contribution as iron ore and broader commodity sentiment held firm. The NZX 50 was flat, edging just 0.01% higher to 13,700.12.

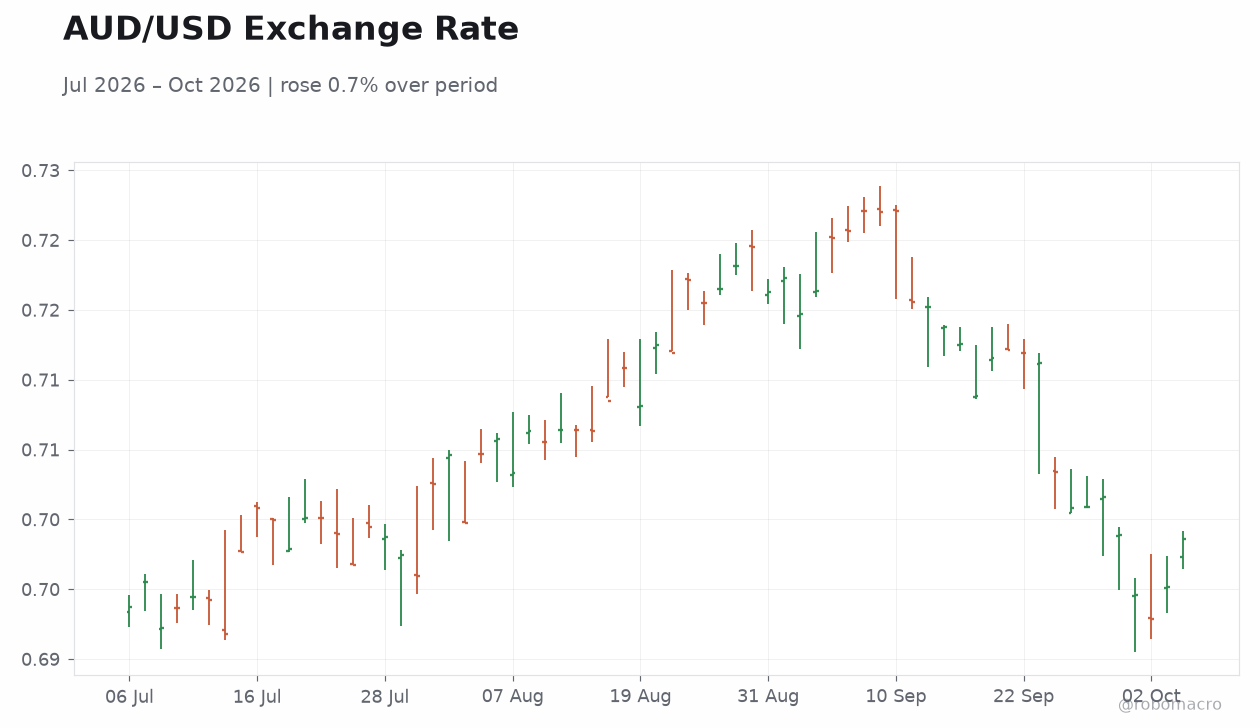
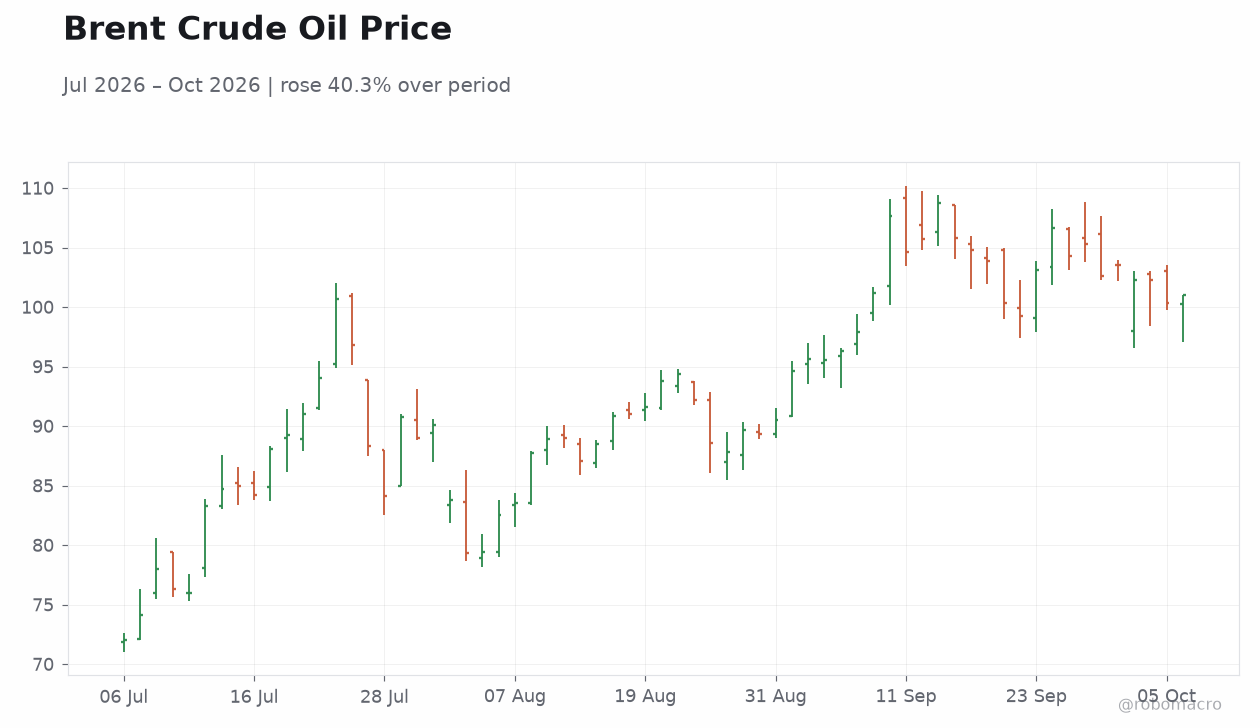
In FX, the AUD gained 0.49% to 0.70 against the USD, outperforming the NZD's 0.15% advance to 0.56, pushing AUD/NZD up 0.55% to 1.24. Gold's 0.92% rise to 4,195.00 and Brent crude's 0.66% gain to 100.98 supported the resource-heavy Australian index, while Bitcoin slipped 0.20% to 85,614.09 in a muted session for risk assets.

The Day Ahead

Today's calendar is light. The sole scheduled release is Australia's Ai Group Industry Index at 18:00 ET, following the prior reading of -3.5. The index has been signalling contraction across the manufacturing, construction and services sectors, and markets will watch whether the negative reading deepens or stabilises.

Any further deterioration would reinforce the narrative of a slowing Australian economy and add weight to expectations that the RBA's tightening cycle has peaked. With no New Zealand data scheduled, the NZD will take its cues from global risk sentiment and commodity flows. Tomorrow's calendar is currently empty, leaving the remainder of the week's data flow sparse and elevating the importance of each marginal print for shaping rate expectations.

Page 1

ANZ Macro Daily(Beta Mode)

October 06, 2026 robomacro.com
AUD/USD Exchange Rate AUD/USD Exchange Rate | Type: market_hloc | AUD/USD: 0.6986 (2026-10-06) | Range: 0.6918–0.7221 | Trend(6pt): 0.6937,0.6987,0.7082,0.7221,0.6929,0.6986
Brent Crude Oil Price Brent Crude Oil Price | Type: market_hloc | Brent ($/bbl): 101 (2026-10-06) | Range: 71.99–108.8 | Trend(6pt): 71.99,84.09,91.62,104.6,100.3,101
ASX 200 Index Performance ASX 200 Index Performance | Type: market_hloc | ASX 200: 8736 (2026-10-06) | Range: 8614–9272 | Trend(6pt): 8831,8948,9054,8819,8682,8736
NZX 50 Index Performance NZX 50 Index Performance | Type: market_hloc | NZX 50: 1.37e+04 (2026-10-06) | Range: 1.356e+04–1.401e+04 | Trend(6pt): 1.376e+04,1.398e+04,1.392e+04,1.358e+04,1.37e+04,1.37e+04

Other Economic Notes

Australia's inflation backdrop remains the dominant macro theme, with CPI running at 4.00% YoY as of August — still above the RBA's 2-3% target band and keeping the policy debate alive. Commentary in the domestic press continues to probe the RBA's reaction function, with analysis focusing on where to look for signs the Bank is prepared to pause, and the political economy of rate rises deepening housing affordability divides. The AUD's resilience despite soft domestic data reflects the pull of the carry trade and firm commodity terms of trade.

In New Zealand, the RBNZ's ongoing work on cash access highlights structural financial-system issues, while dairy markets are navigating Canadian restrictions and Chinese demand questions — a key watch for NZ's export receipts.

Global Macro News

Global central bank dynamics are in focus, with the Bank of Japan's Ueda characterising Japan's economy as recovering moderately albeit with weaknesses. The yen traded in a tight range in the upper 157s against the dollar, with wide yield differentials continuing to support USD/JPY and Japan's government vowing fiscal prudence — a combination that keeps the carry trade environment relatively stable for now. Elsewhere in Asia, the Korean won firmed marginally against the greenback.

↓ p.3

Sponsored by Arbitrage Search
Page 2

ANZ Macro Daily(Beta Mode)

October 06, 2026 robomacro.com

Continuation

Global Macro News (continued)

On the trade front, Treasurer Chalmers moved to calm Japanese jitters over Australia's gas reservation policy, promising executives in Tokyo that Australia would remain a dependable energy supplier — a reassurance with direct relevance to LNG trade flows and Japan's energy security. Middle East tensions continue to underpin oil, with Brent holding above the 100 level, a tailwind for Australia's terms of trade but a headwind for global growth sentiment.

ANZ Central Banks Watch

The policy divergence between the RBA and RBNZ remains the defining structural feature of the trans-Tasman rates complex. The RBA's cash rate stands at 4.35%, set at the September 24 meeting, with Australian CPI at 4.00% YoY still running hot enough to keep further tightening on the table — a debate amplified by consumer confidence languishing at 80.4. The RBNZ, by contrast, has been on a markedly different path: the OCR sits at 2.75% as of September 25, reflecting the Bank's earlier and more aggressive easing cycle as New Zealand's disinflation progressed with CPI at 4.10% YoY as of June.

That 160 bp gap in policy rates underpins the AUD's 0.55% premium move against the NZD yesterday and continues to shape relative-value positioning in trans-Tasman fixed income. The RBNZ's October Monetary Policy Review updates and November Financial Stability Report scheduling have been flagged, giving markets clear markers for the next policy checkpoints. For the RBA, the path forward hinges on monthly CPI prints and the labour market; the press commentary on the "only fast path to rate cuts" being a "more painful one" captures the tension between a soft landing and timely easing.

Housing remains the critical transmission channel in both economies, with Australian rate rises deepening affordability divides and New Zealand's construction sector sensitive to the OCR path. Watch for any shift in the RBA's guidance as Q3 data accumulates.

Sponsored by Arbitrage Search
Page 3