ANZ Macro Daily(Beta Mode)
RBNZ Hike Expected as Australia CPI Looms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
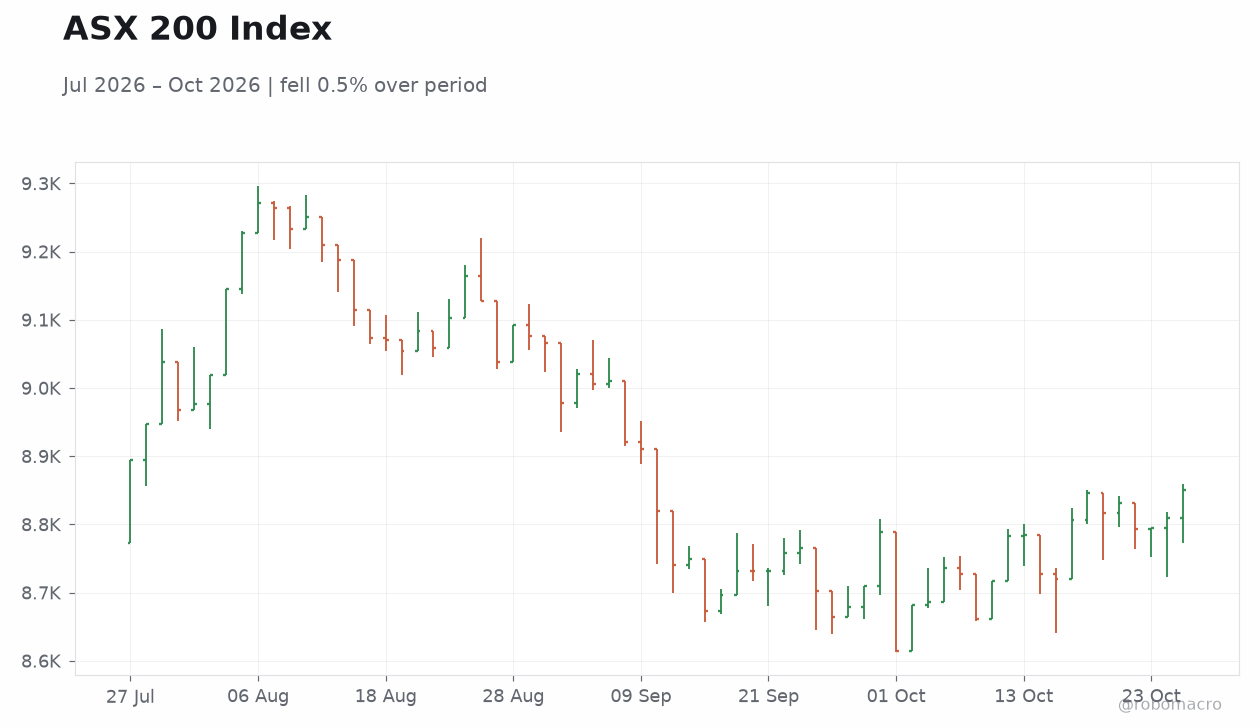
| ASX 200 | 8,850.10 | +0.46% |
| NZX 50 | 13,680.27 | -0.39% |
| AUD/USD | 0.70 | +0.02% |
| NZD/USD | 0.57 | -0.26% |
| AUD/NZD | 1.24 | +0.26% |
| BHP | 57.99 | +4.26% |
| Gold | 4,075.40 | +0.92% |
| Brent Crude | 109.45 | -5.49% |
| Bitcoin | 80,719.27 | +0.89% |
| Australia 2Y Govt Yield | 4.92% | +6 bp |
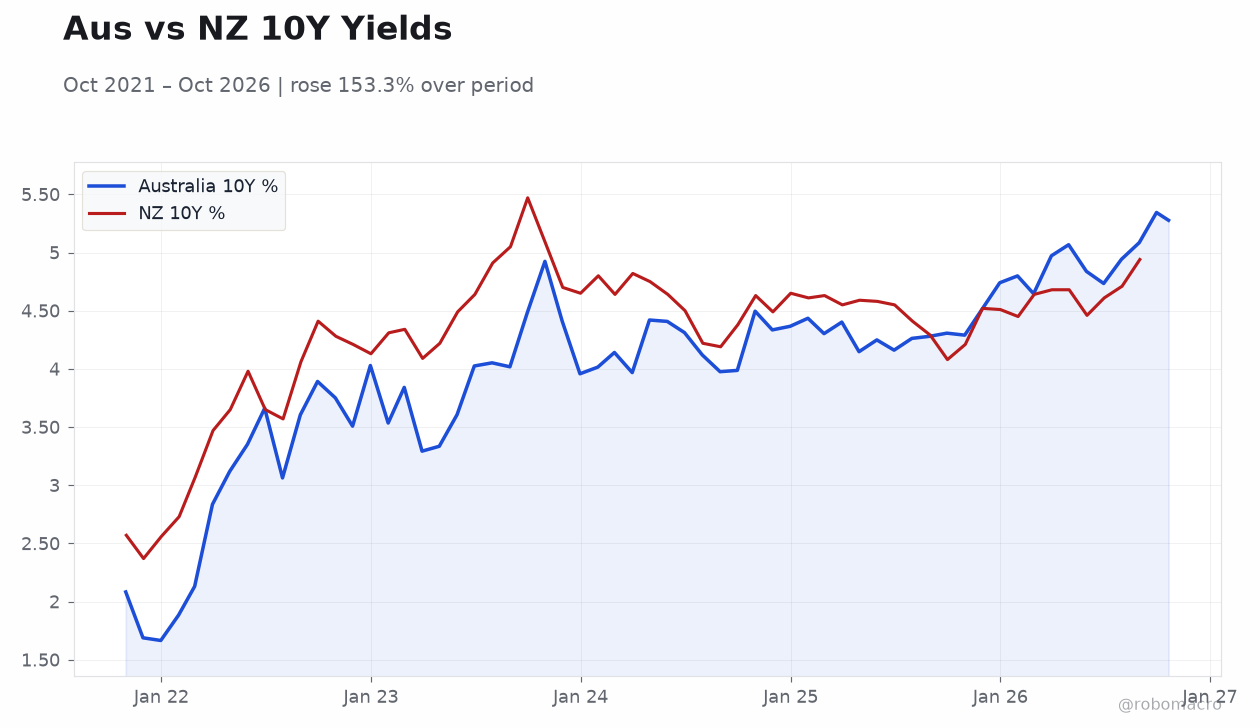
| Australia 10Y Govt Yield | 5.28% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
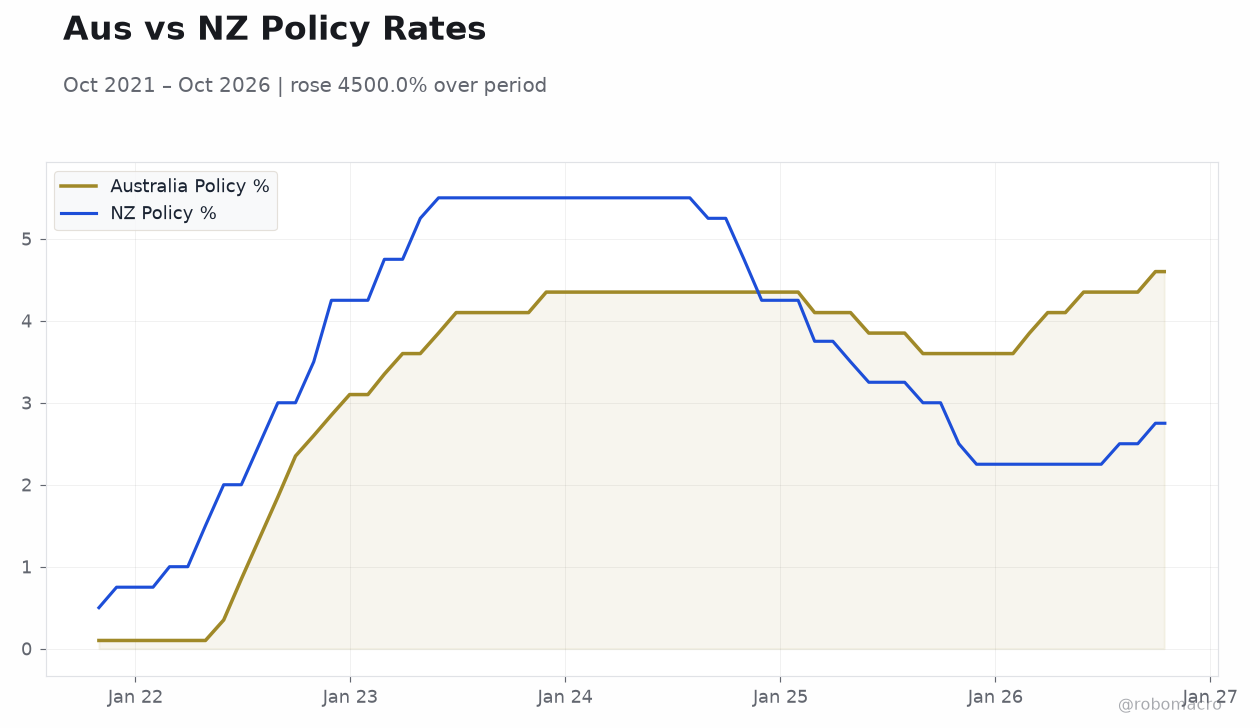 Aus vs NZ Policy Rates | Type: macro_line | Australia Policy %: 4.6 (2026-10-15) | Range: 0.1–4.6 | Trend(5pt): 0.1,3.1,4.35,3.85,4.6 | NZ Policy %: 2.75 (2026-10-16) | Range: 0.5–5.5 | Trend(5pt): 0.5,4.25,5.5,3.25,2.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| RBA Senate Appearance | - | - | 20:15 |
| Inflation Rate Month-over-Month | 0.40 | 0.70 | 20:30 |
| Inflation Rate Year-over-Year | 4 | 4.20 | 20:30 |
| RBA Trimmed Mean CPI Month-over-Month | 0.20 | 0.30 | 20:30 |
| RBA Trimmed Mean CPI Year-over-Year | 3.60 | 3.60 | 20:30 |
| RBNZ Interest Rate Decision | 2.75 | 3 | 21:00 |
| RBNZ Rate Statement | - | - | 21:00 |
| RBNZ Press Conference | - | - | 22:00 |
| ANZ Business Confidence | 51.90 | - | 20:00 |
- Australia CPI and RBNZ decision dominate today's ANZ calendar, with markets pricing tighter policy in both countries.
- ASX 200 rose 0.46% while NZX 50 fell 0.39%, as miners advanced on commodity strength and yields lifted across the curve.
- AUD/USD held above 0.70 amid inflation focus, while NZD/USD eased despite RBNZ hike expectations.
Yesterday's Recap
Australian equity markets advanced as the ASX 200 gained 0.46% to 8,850.10, supported by a 4.26% surge in BHP shares and broader commodity gains. The NZX 50 declined 0.39% to 13,680.27 as local sentiment lagged. Australian government yields rose, with the 2-year yield climbing 6 bp to 4.92% and the 10-year yield adding 3 bp to 5.28%.
The Australian dollar strengthened 0.02% to 0.70 against the US dollar, while the New Zealand dollar fell 0.26% to 0.57. AUD/NZD rose 0.26% to 1.24. Gold climbed 0.92% to 4,075.40, offsetting a 5.49% drop in Brent crude.
No major economic data releases occurred in either Australia or New Zealand.
The Day Ahead
Australia's October CPI figures, including headline and trimmed-mean measures, are scheduled for release at 20:30 ET alongside an RBA Senate appearance at 20:15 ET. Markets will assess whether the data reinforces the case for further RBA tightening given the verified 4.0% YoY print from August. New Zealand's RBNZ will announce its interest-rate decision, statement and press conference at 21:00 ET, with the committee expected to address the path from the 2.75% OCR level set on 2 September.
The RBNZ press conference will provide fresh guidance on inflation and housing-market risks. Tomorrow brings the ANZ Business Confidence survey for New Zealand.
Other Economic Notes
Australia's role as a major commodity exporter leaves its growth outlook tightly linked to Chinese demand for iron ore, coal and LNG. New Zealand's dairy, tourism and construction sectors remain sensitive to global travel recovery and domestic credit conditions. Housing-market dynamics continue to influence both central banks, with rate paths affecting mortgage costs and household spending.
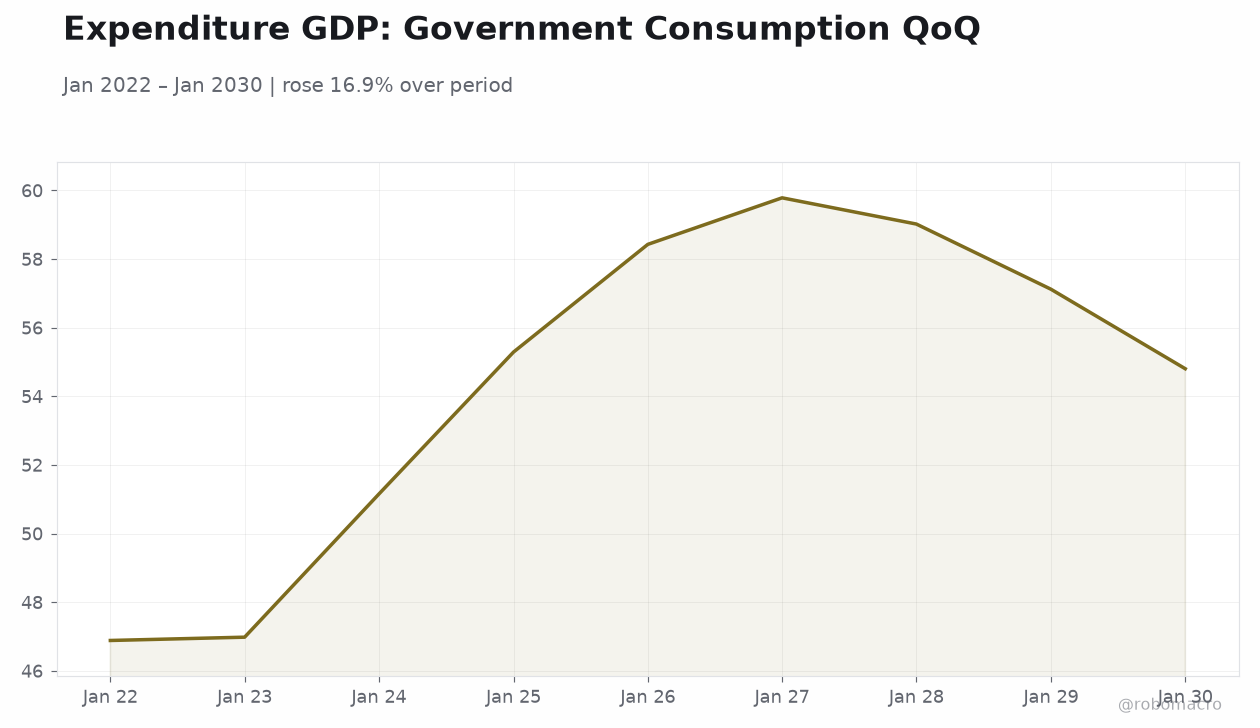
Broader fiscal restraint in Australia could help moderate inflation pressures without additional monetary tightening. China’s growth trajectory remains the dominant external variable for both economies.