ANZ Macro Daily(Beta Mode)
RBA Hike Bets Build as RBNZ Stuns With Hold
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| ASX 200 | 8,847.30 | -0.03% |
| NZX 50 | 13,691.33 | +0.08% |
| AUD/USD | 0.71 | +0.58% |
| NZD/USD | 0.56 | -1.01% |
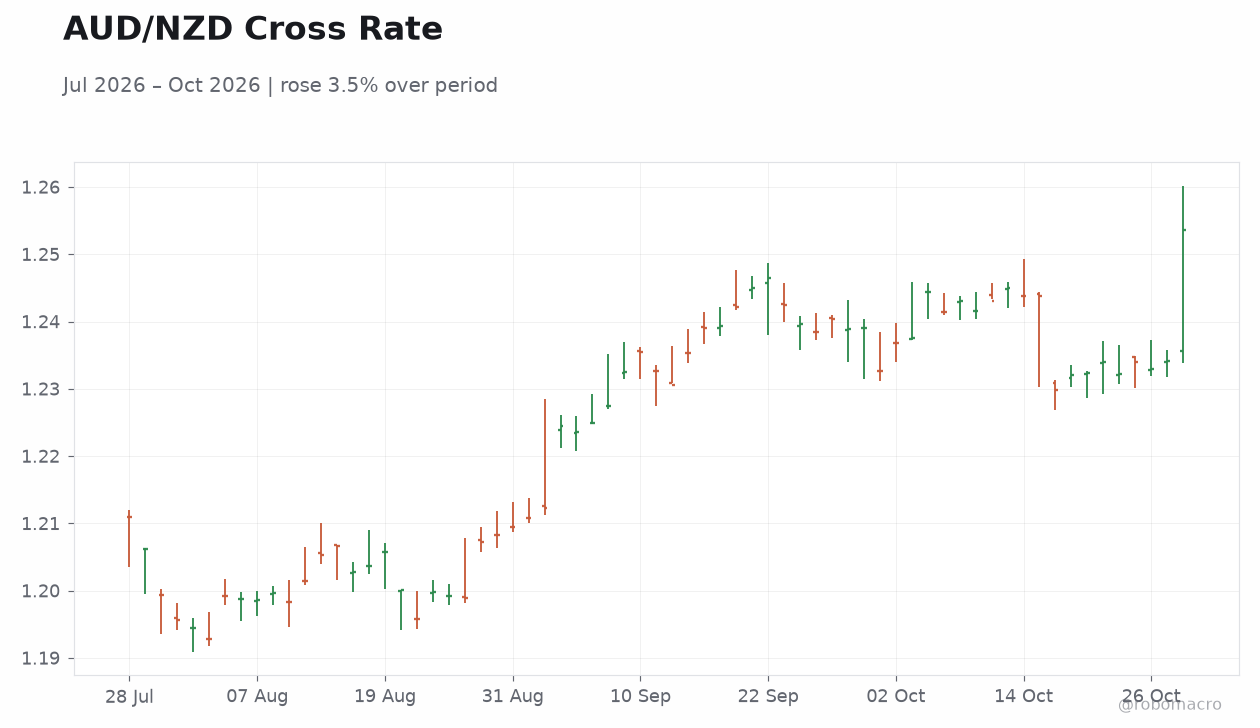
| AUD/NZD | 1.25 | +1.58% |
| BHP | 58.04 | +0.09% |
| Gold | 4,061.40 | -0.32% |
| Brent Crude | 111.32 | -2.25% |
| Bitcoin | 81,109.83 | +0.38% |
| Australia 2Y Govt Yield | 4.92% | +6 bp |
| Australia 10Y Govt Yield | 5.28% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBA Senate Appearance | - | - | "" |
| Inflation Rate Month-over-Month | 0.40 | 0.70 | 0.80 |
| Inflation Rate Year-over-Year | 4 | 4.20 | 4.30 |
| RBA Trimmed Mean CPI Month-over-Month | 0.20 | 0.30 | 0.30 |
| RBA Trimmed Mean CPI Year-over-Year | 3.50 | 3.60 | 3.60 |
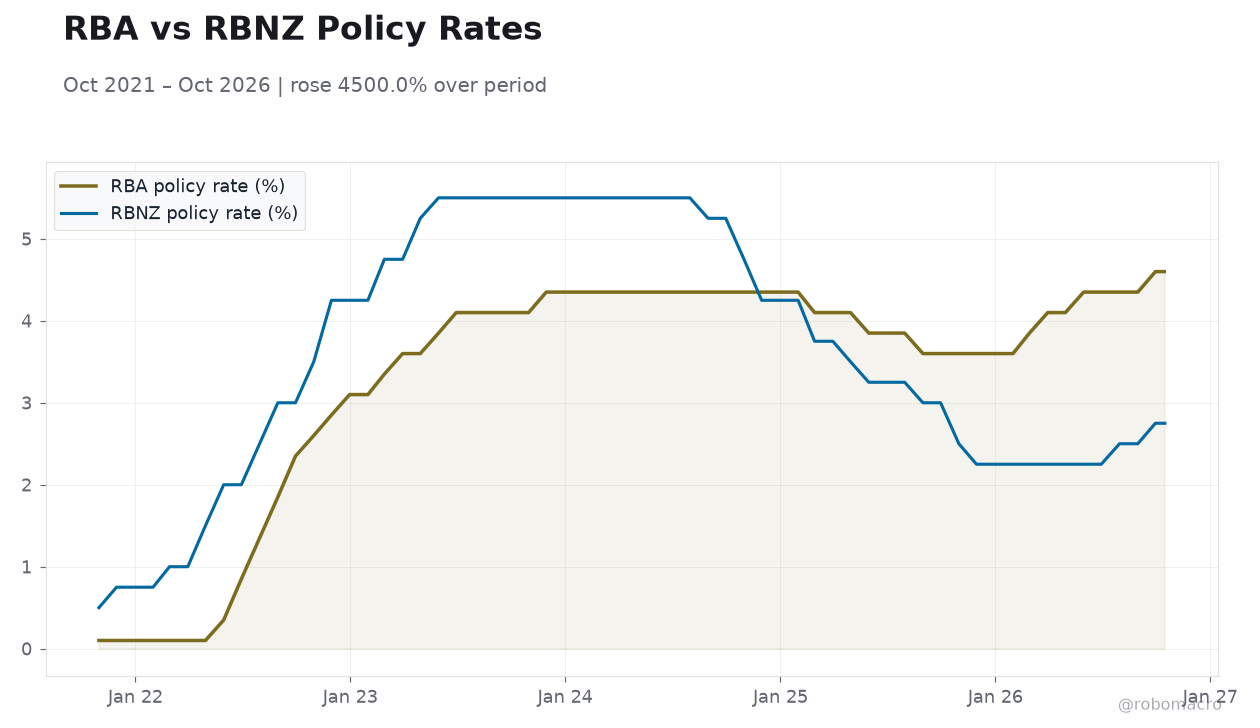
| RBNZ Interest Rate Decision | 2.75 | 3 | 2.75 |
| RBNZ Rate Statement | - | - | - |
| RBNZ Press Conference | - | - | - |
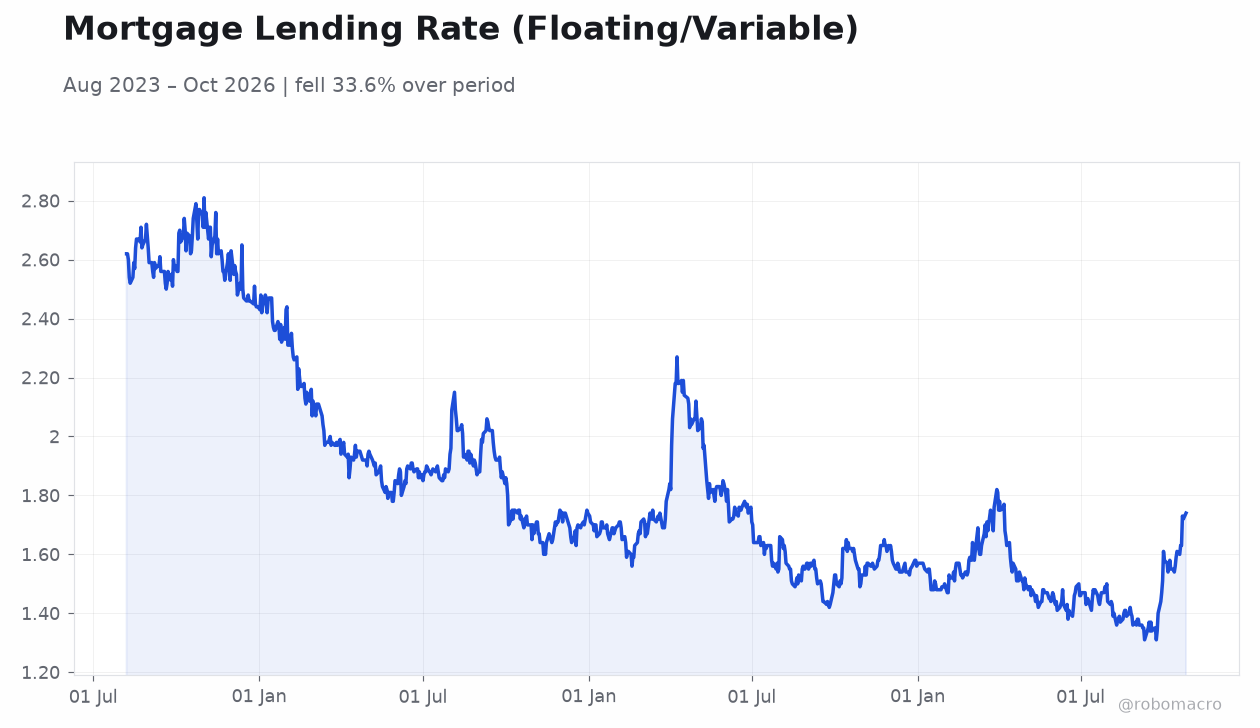
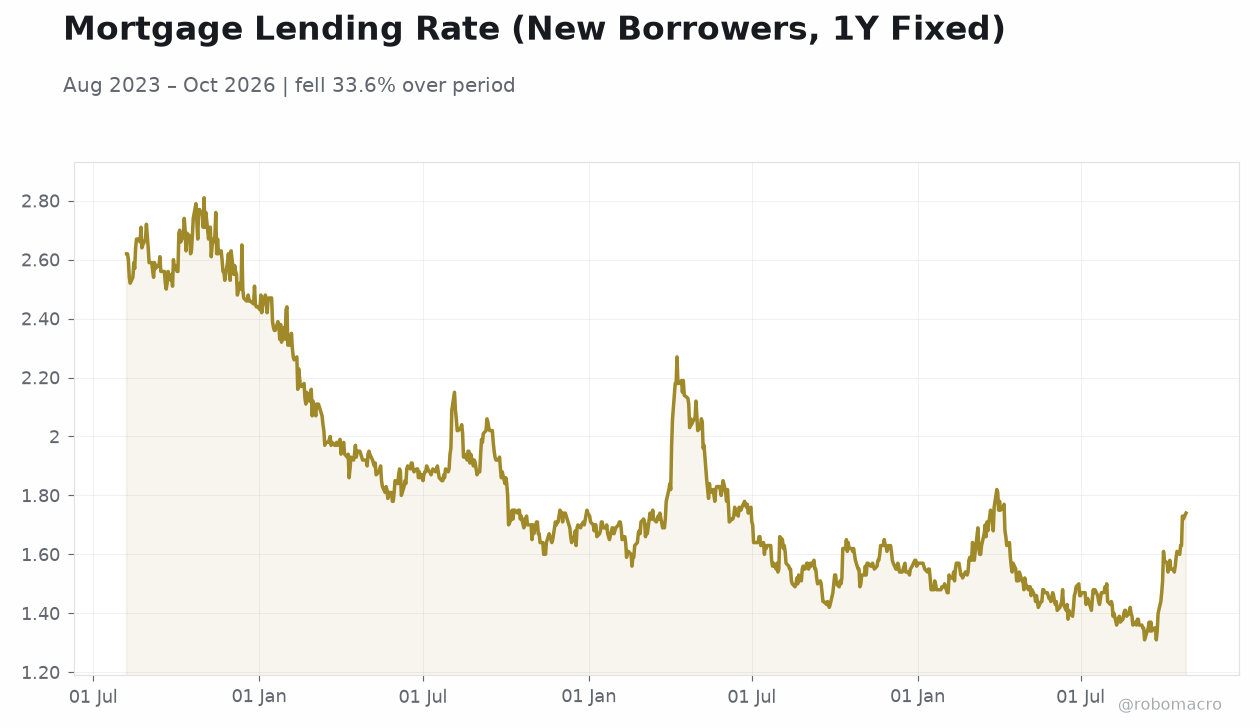 Mortgage Lending Rate (New Borrowers, 1Y Fixed) | Type: macro_line | Mortgage Lending Rate (New Borrowers, 1Y Fixed): 1.74 (2026-10-26) | Range: 1.31–2.81 | Trend(5pt): 2.62,1.78,1.72,1.57,1.74
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| ANZ Business Confidence | 51.90 | - | 20:00 |
| PPI Quarter-over-Quarter | 1.30 | 1 | 20:30 |
| Thursday (2026-10-29) | |||
| PPI Quarter-over-Quarter | 1.30 | 1 | 20:30 |
- Australia Q3 CPI surprised to the upside, with headline inflation at 4.3% y/y and trimmed mean at 3.6% y/y, cementing expectations for a near-term RBA hike.
- The RBNZ unexpectedly held the OCR at 2.75% against consensus for a hike to 3.00%, sending NZD/USD down over 1% and AUD/NZD up 1.58%.
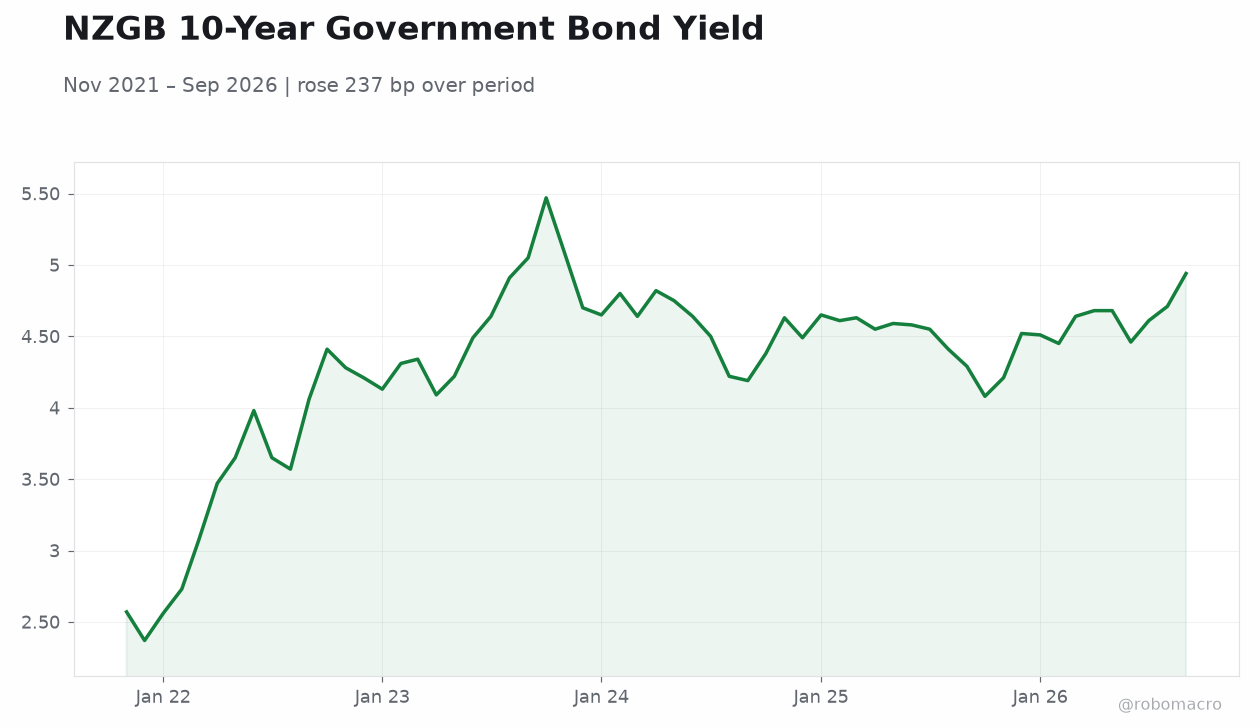
- Australian 2Y yields rose 6 bp to 4.92% and 10Y yields 3 bp to 5.28% as markets priced a more hawkish RBA path, widening the AU-NZ rate differential sharply.
Yesterday's Recap
Australia's Q3 CPI printed above expectations, with headline inflation at 4.3% y/y versus consensus of 4.2% and 0.8% m/m against a 0.7% forecast. The RBA trimmed mean rose 0.3% m/m as expected and 3.6% y/y, in line with the 3.6% consensus, confirming sticky underlying price pressures. The hotter headline drove AUD/USD up 0.58% to 0.71 and pushed Australian 2Y yields 6 bp higher to 4.92%, with 10Y yields up 3 bp to 5.28%.
In New Zealand, the RBNZ unexpectedly left the OCR unchanged at 2.75% despite consensus for a hike to 3.00%, a dovish surprise that sent NZD/USD down 1.01% to 0.56. The divergence drove AUD/NZD up 1.58% to 1.25, the sharpest single-day move since 2017 per Bloomberg. The ASX 200 was essentially flat at 8,847.30 (-0.03%) while the NZX 50 edged up 0.08% to 13,691.33.
The Day Ahead
New Zealand's ANZ Business Confidence release for October is the key domestic print today, with the prior reading at 51.9. Australia's Q3 PPI follows tomorrow, with consensus at 1.0% q/q versus a previous 1.3%, offering a further read on pipeline inflation pressures. The RBA Senate appearance already occurred yesterday, so attention shifts to the inflation implications for the November 3 RBA meeting.
Markets will also watch for any RBNZ commentary following yesterday's surprise hold, with the press conference having already taken place. Regional data flow is light, leaving AUD and NZD positioning driven by rate-differential dynamics.
Other Economic Notes
The Australian inflation surprise leaves the RBA with little room to manoeuvre, with headline CPI at 4.3% y/y well above the target band and trimmed mean at 3.6% y/y. RBA Governor Bullock has publicly warned inflation is "far too high" while ruling out a near-term recession, a delicate communication challenge. Housing remains a critical transmission channel, with elevated rates pressuring mortgage holders and dampening construction activity.
In New Zealand, the RBNZ's surprise hold suggests the committee sees insufficient evidence to resume tightening despite earlier hawkish guidance. The AU-NZ rate differential is now a dominant driver of cross-rate flows.