ANZ Macro Daily(Beta Mode)
RBNZ Surprise Hold; Hot AU CPI Boosts RBA Hike Bets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| ASX 200 | 8,891.80 | +0.50% |
| NZX 50 | 13,710.17 | +0.14% |
| AUD/USD | 0.70 | +0.04% |
| NZD/USD | 0.56 | -0.87% |
| AUD/NZD | 1.25 | +0.90% |
| BHP | 57.52 | -0.90% |
| Gold | 4,023.20 | -0.70% |
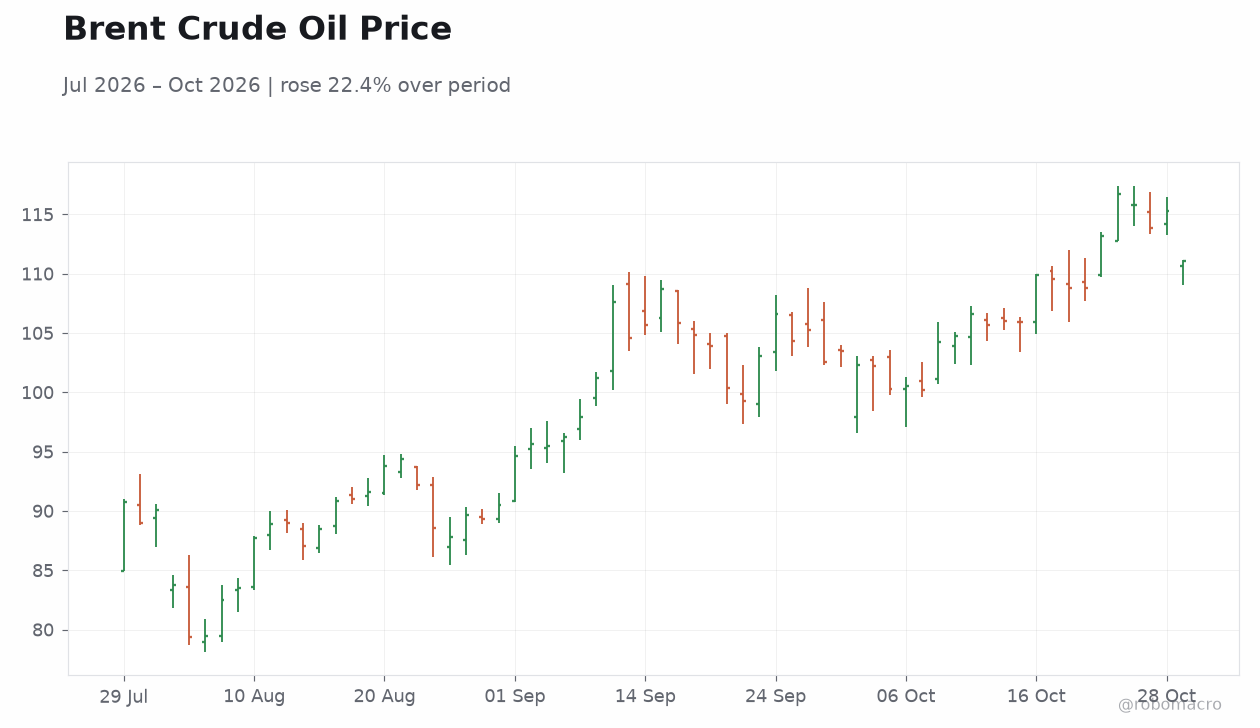
| Brent Crude | 110.97 | -3.77% |
| Bitcoin | 80,724.54 | -0.67% |
| Australia 2Y Govt Yield | 4.92% | +6 bp |
| Australia 10Y Govt Yield | 5.28% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBA Senate Appearance | - | - | "" |
| Inflation Rate Month-over-Month | 0.40 | 0.70 | 0.80 |
| Inflation Rate Year-over-Year | 4 | 4.20 | 4.30 |
| RBA Trimmed Mean CPI Month-over-Month | 0.20 | 0.30 | 0.30 |
| RBA Trimmed Mean CPI Year-over-Year | 3.50 | 3.60 | 3.60 |
| RBNZ Interest Rate Decision | 2.75 | 3 | 2.75 |
| RBNZ Rate Statement | - | - | - |
| RBNZ Press Conference | - | - | - |
| ANZ Business Confidence | 51.90 | - | 52.50 |
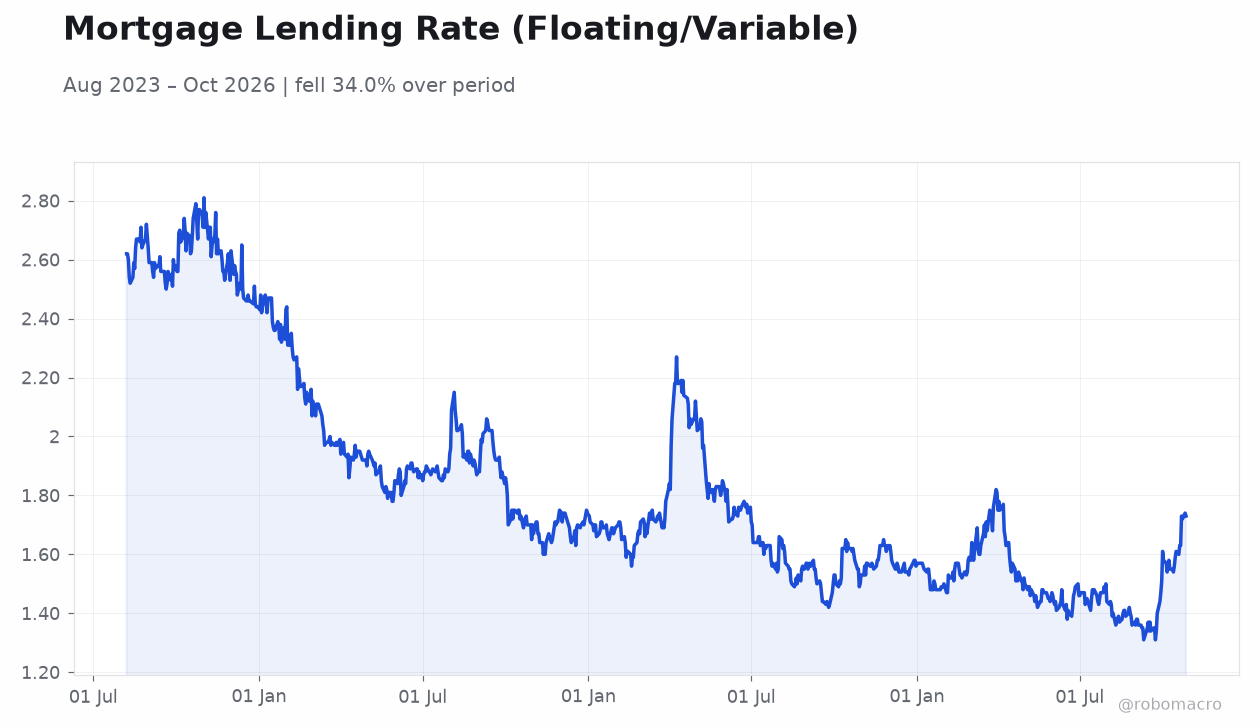
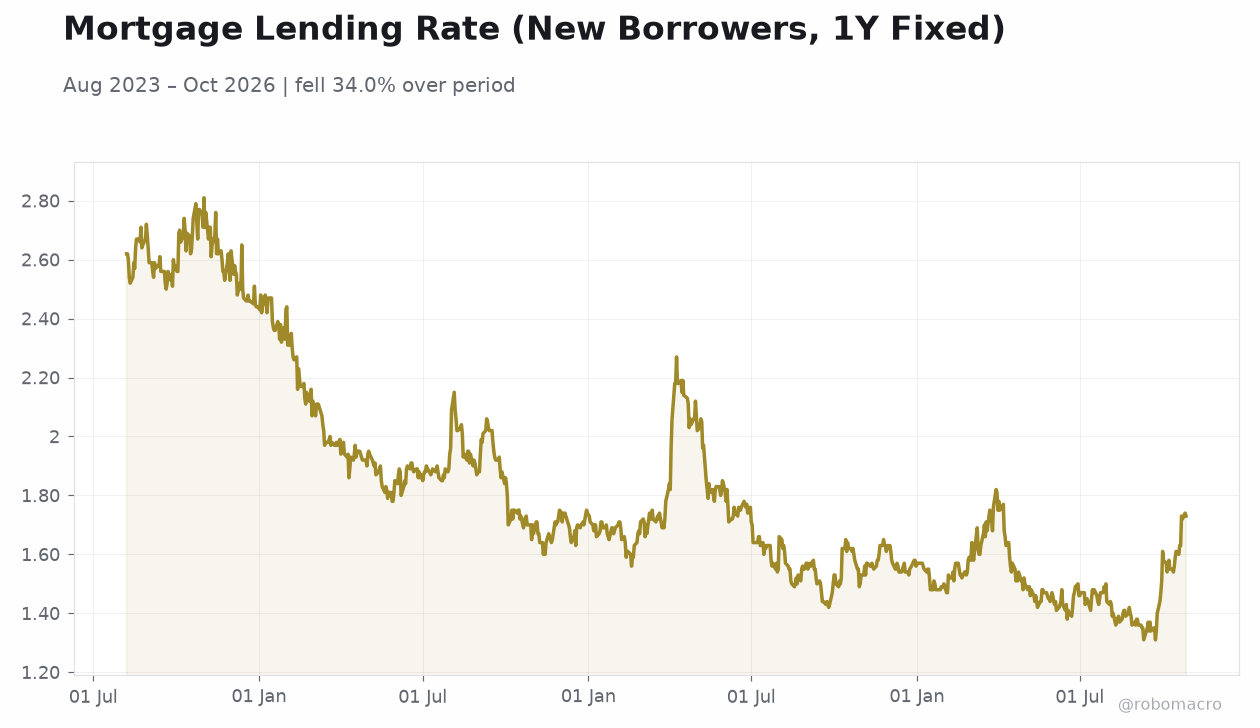 Mortgage Lending Rate (New Borrowers, 1Y Fixed) | Type: macro_line | Mortgage Lending Rate (New Borrowers, 1Y Fixed): 1.73 (2026-10-27) | Range: 1.31–2.81 | Trend(6pt): 2.62,1.78,1.72,1.57,1.74,1.73
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| PPI Quarter-over-Quarter | 1.30 | 1 | 20:30 |
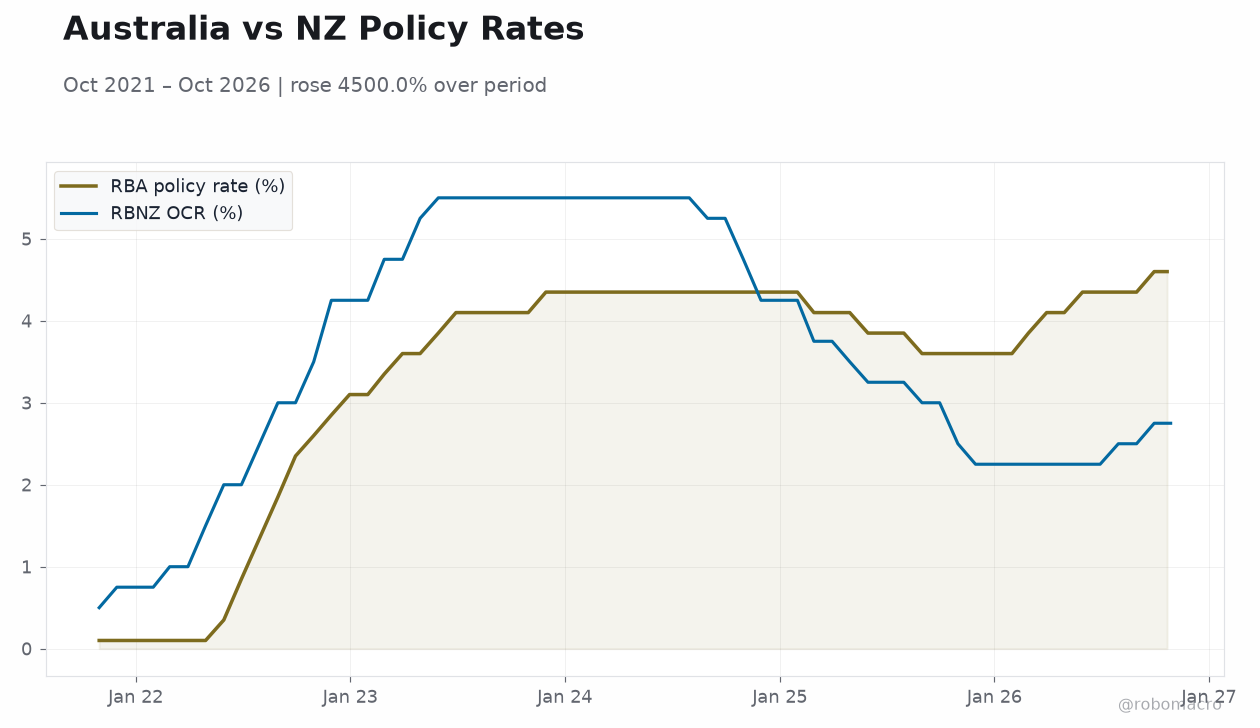
- RBNZ unexpectedly held the OCR at 2.75% versus consensus for a hike to 3.00%, sending NZD/USD down 0.87% and AUD/NZD up 0.90% — the kiwi's sharpest slide versus the Aussie since 2017.
- Australian Q3 CPI printed hot: headline 0.8% m/m and 4.3% y/y versus consensus 0.7% and 4.2%, with trimmed mean at 0.3% m/m and 3.6% y/y, cementing expectations for an RBA hike at the 3 November meeting.
- Australian 2-year yields rose 6 bp to 4.92% and 10-year yields 3 bp to 5.28% as markets priced a more hawkish RBA path, while Brent crude fell 3.77% to $110.97.
Yesterday's Recap
Australia's Q3 CPI came in above consensus across every measure: headline rose 0.8% m/m (consensus 0.7%) and 4.3% y/y (consensus 4.2%), while the RBA's preferred trimmed mean printed 0.3% m/m and 3.6% y/y, both a touch above expectations. The result reinforced market pricing for another RBA hike at next week's meeting, with the Australian dollar trading above 0.7050 intraday before settling at 0.70, up 0.04%. In New Zealand, the RBNZ surprised the market by holding the OCR at 2.75% rather than delivering the hike consensus had expected, and the accompanying statement and press conference were read as leaving the door open to a December move.
The kiwi plunged, with NZD/USD falling 0.87% to 0.56 and AUD/NZD jumping 0.90% to 1.25 — the largest single-day kiwi decline versus the Aussie since 2017. NZ ANZ Business Confidence edged up to 52.5 from 51.9, a mildly constructive signal for activity. Domestic equities were firm, with the ASX 200 up 0.50% to 8,891.80 and the NZX 50 up 0.14% to 13,710.17, though BHP slipped 0.90% to $57.52.
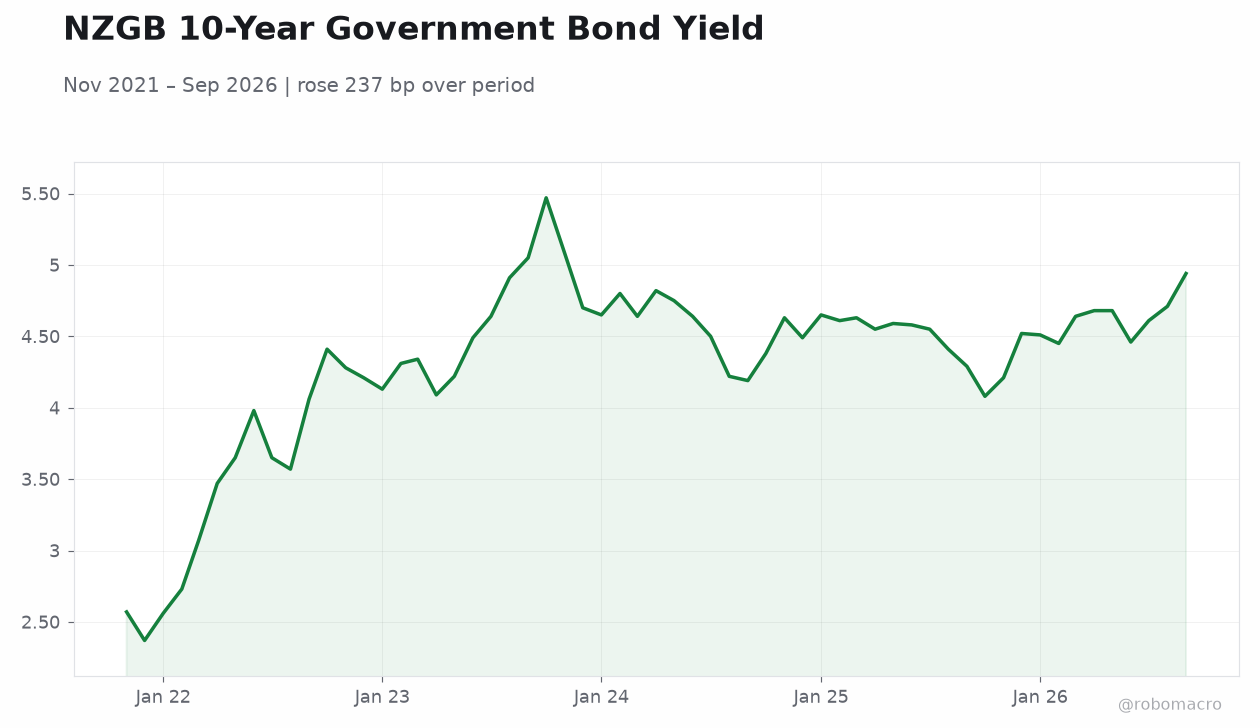
Rates markets moved to price the Australian inflation surprise, with the 2-year yield up 6 bp to 4.92% and the 10-year up 3 bp to 5.28%.
The Day Ahead
The only scheduled ANZ release today is Australian PPI for the quarter, due at 20:30 ET, with consensus at 1.0% q/q following the prior 1.3% print. The data will be scrutinised for pipeline inflation pressure following yesterday's hot CPI, though it is unlikely to shift the RBA narrative materially given the CPI already landed. No New Zealand data is scheduled, leaving NZD direction to be driven by offshore factors and positioning after the RBNZ shock.
With the RBA meeting on 3 November now firmly in focus, markets will continue to refine hike odds, and the PPI print could nudge the curve at the margin. Attention also turns to the global backdrop, with the Fed decision looming and risk sentiment fragile after the oil selloff.
Other Economic Notes
The divergence between Australian and New Zealand policy trajectories is now the dominant ANZ macro theme: Australian inflation at 4.3% y/y is well above target and pushing the RBA toward further tightening, while New Zealand CPI at 3.70% y/y sits closer to the RBNZ's band and justified its decision to hold. ↓ p.2