ANZ Macro Daily(Beta Mode)
RBA Hikes to 4.85% as AUD Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| ASX 200 | 8,886.80 | +0.34% |
| NZX 50 | 13,720.26 | +0.46% |
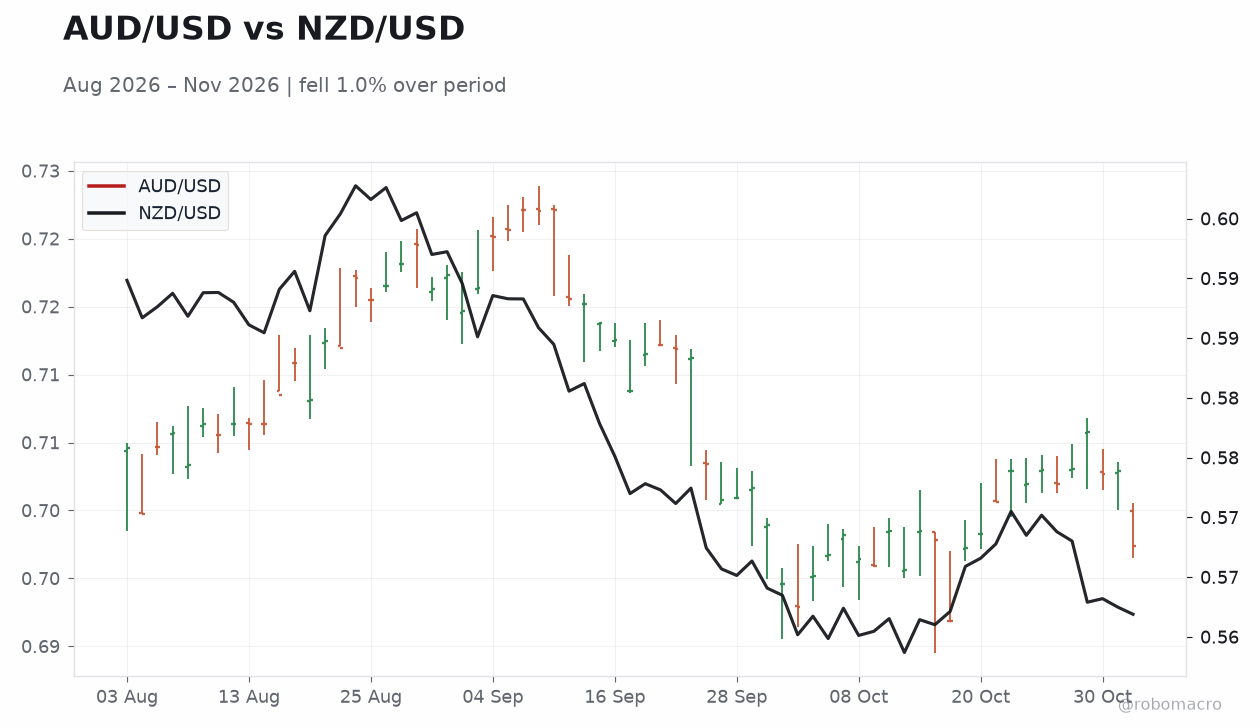
| AUD/USD | 0.70 | -0.79% |
| NZD/USD | 0.56 | -0.11% |
| AUD/NZD | 1.24 | -0.70% |
| BHP | 56.42 | -0.56% |
| Gold | 3,937.00 | -0.82% |
| Brent Crude | 103.37 | -1.34% |
| Bitcoin | 77,487.59 | +1.06% |
| Australia 2Y Govt Yield | 4.95% | +7 bp |
| Australia 10Y Govt Yield | 5.21% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBA Interest Rate Decision | 4.60 | 4.85 | 4.85 |
| RBA Monetary Policy Statement | - | - | - |
| RBA Rate Statement | - | - | - |
| RBA Press Conference | - | - | - |
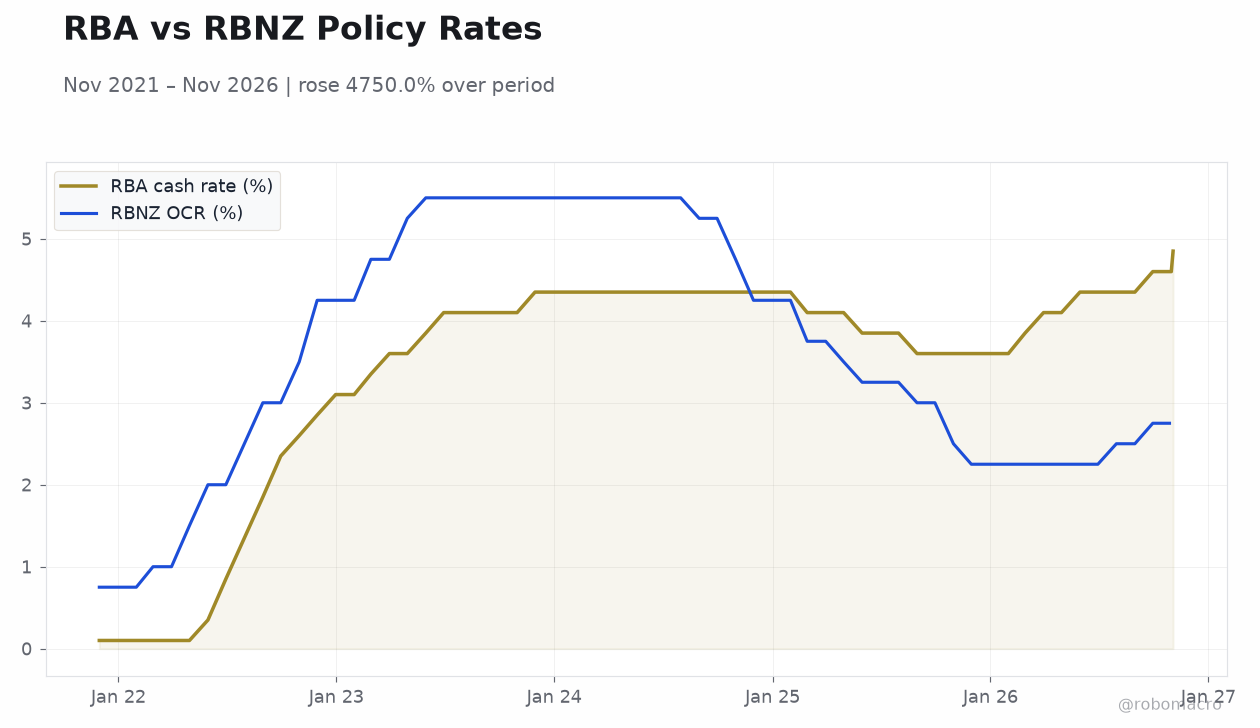 RBA vs RBNZ Policy Rates | Type: macro_line | RBA cash rate (%): 4.85 (2026-11-03) | Range: 0.1–4.85 | Trend(5pt): 0.1,3.35,4.35,3.6,4.85 | RBNZ OCR (%): 2.75 (2026-10-28) | Range: 0.75–5.5 | Trend(5pt): 0.75,4.75,5.5,3,2.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Employment Change Quarter-over-Quarter | 0.50 | 0.40 | 16:45 |
| Headline Unemployment Rate | 5.60 | 5.50 | 16:45 |
| Ai Group Industry Index | -24.20 | - | 17:00 |
- RBA lifts cash rate to 4.85% in fifth hike this year, citing persistent inflation.
- Australian yields rise and AUD falls against USD and NZD despite the tightening.
- Equity markets edge higher while commodity prices retreat on global demand concerns.
Yesterday's Recap
The RBA raised the cash rate to 4.85% at its November meeting, in line with consensus, and released an accompanying statement that flagged elevated inflation risks. The Monetary Policy Statement and subsequent press conference reinforced the committee's focus on returning CPI to target. Australian 2-year yields climbed 7 bp to 4.95% and 10-year yields added 6 bp to 5.21%.
The AUD/USD pair fell 0.79% to 0.70 while AUD/NZD slipped 0.70% to 1.24. The ASX 200 rose 0.34% to 8,886.80 and the NZX 50 gained 0.46% to 13,720.26. BHP shares declined 0.56% to 56.42 amid softer iron-ore prices.
The RBNZ held its OCR at 2.75% at its late-October meeting and registered Revolut as New Zealand's 27th bank.
The Day Ahead
New Zealand releases quarterly employment data and the headline unemployment rate at 16:45 ET, with markets expecting a modest slowdown in hiring (consensus 0.4% q/q employment change versus 0.5% previously, and unemployment at 5.5% versus 5.6%). Australia's Ai Group Industry Index follows at 17:00 ET and will provide an early read on manufacturing and services momentum, with the prior print at -24.2. Tomorrow brings Australia's October trade balance, forecast to widen to A$1.2bn from A$495m on stronger commodity shipments.
No RBA or RBNZ speakers are listed in the calendar for today.
Other Economic Notes
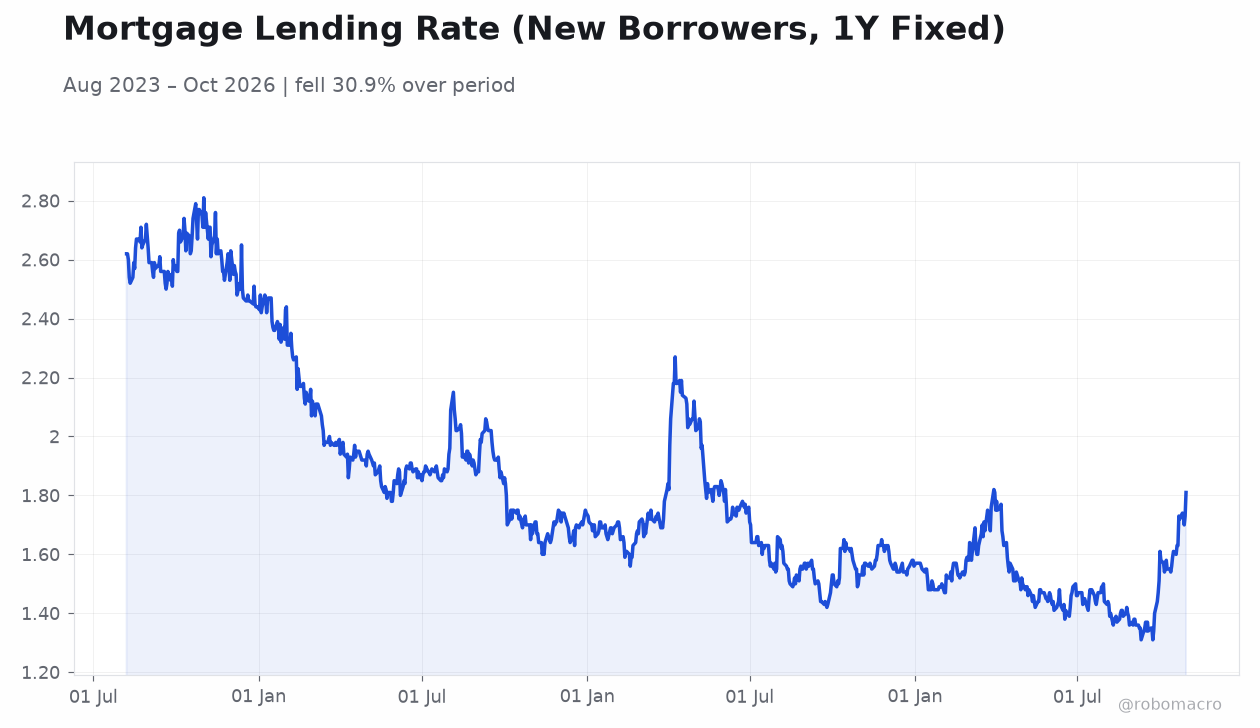
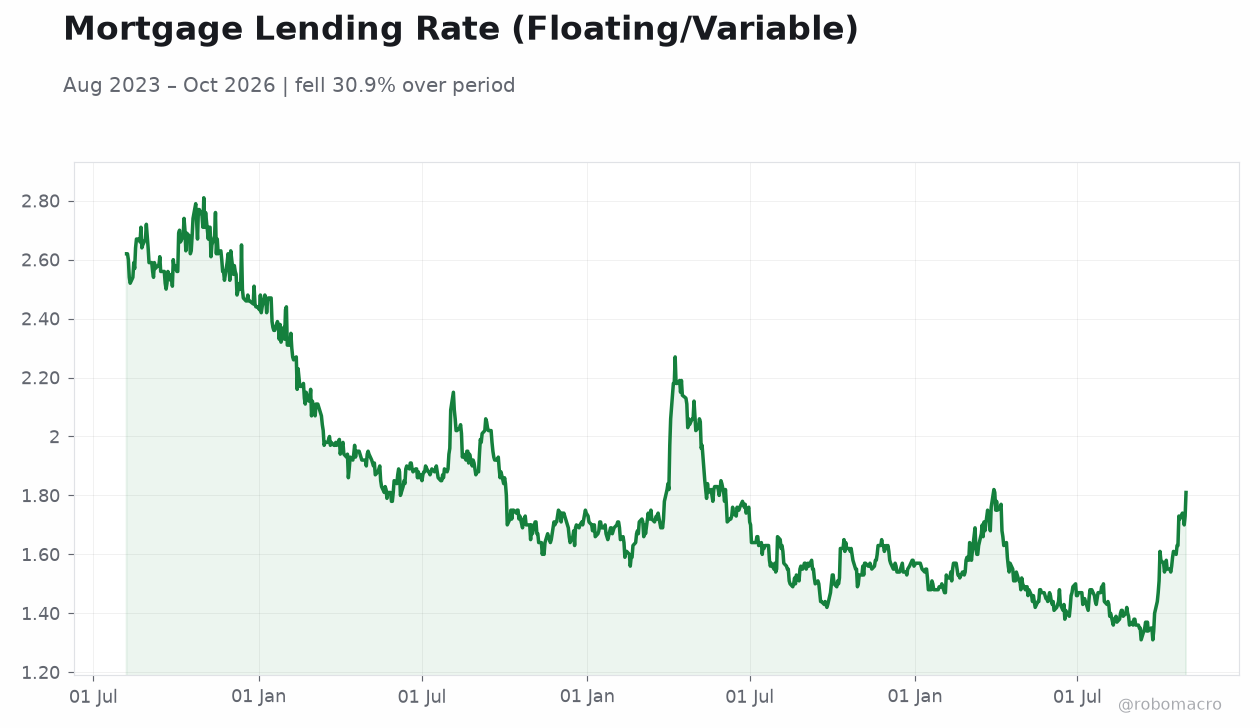
Australia's housing market continues to weaken under higher borrowing costs, with transaction volumes and prices both sliding. The RBA has warned that next year could feel recessionary for households despite the economy avoiding outright contraction. New Zealand's dairy and tourism sectors remain sensitive to global growth and currency swings.
China's demand outlook stays the dominant external driver for Australian commodity exports and NZ agricultural prices. Policymakers in both countries are watching wage and housing inflation closely for signs of persistence.