ANZ Macro Daily(Beta Mode)
RBA Hikes to 4.85%, NZ Jobs Slump
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| ASX 200 | 9,065.10 | +2.61% |
| NZX 50 | 14,090.97 | +0.84% |
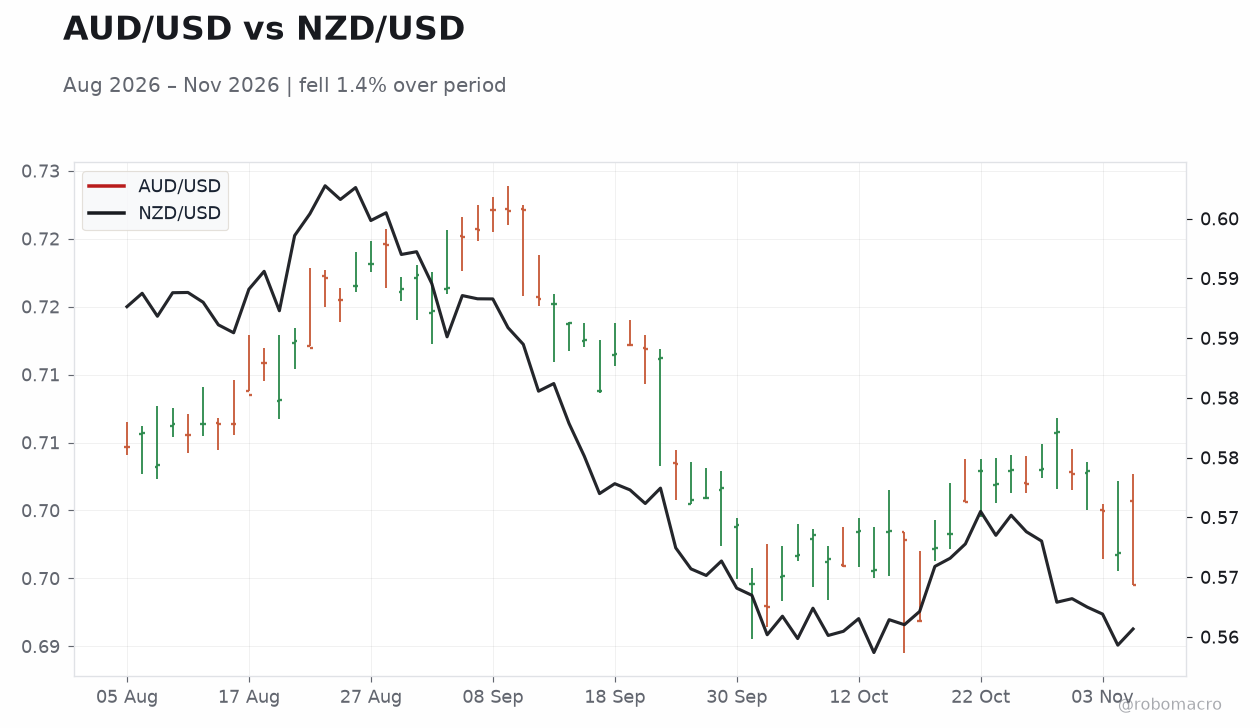
| AUD/USD | 0.69 | -0.30% |
| NZD/USD | 0.56 | +0.27% |
| AUD/NZD | 1.24 | -0.59% |
| BHP | 59.00 | +6.19% |
| Gold | 4,109.40 | +0.89% |
| Brent Crude | 97.94 | +3.51% |
| Bitcoin | 75,966.30 | -5.52% |
| Australia 2Y Govt Yield | 4.95% | +7 bp |
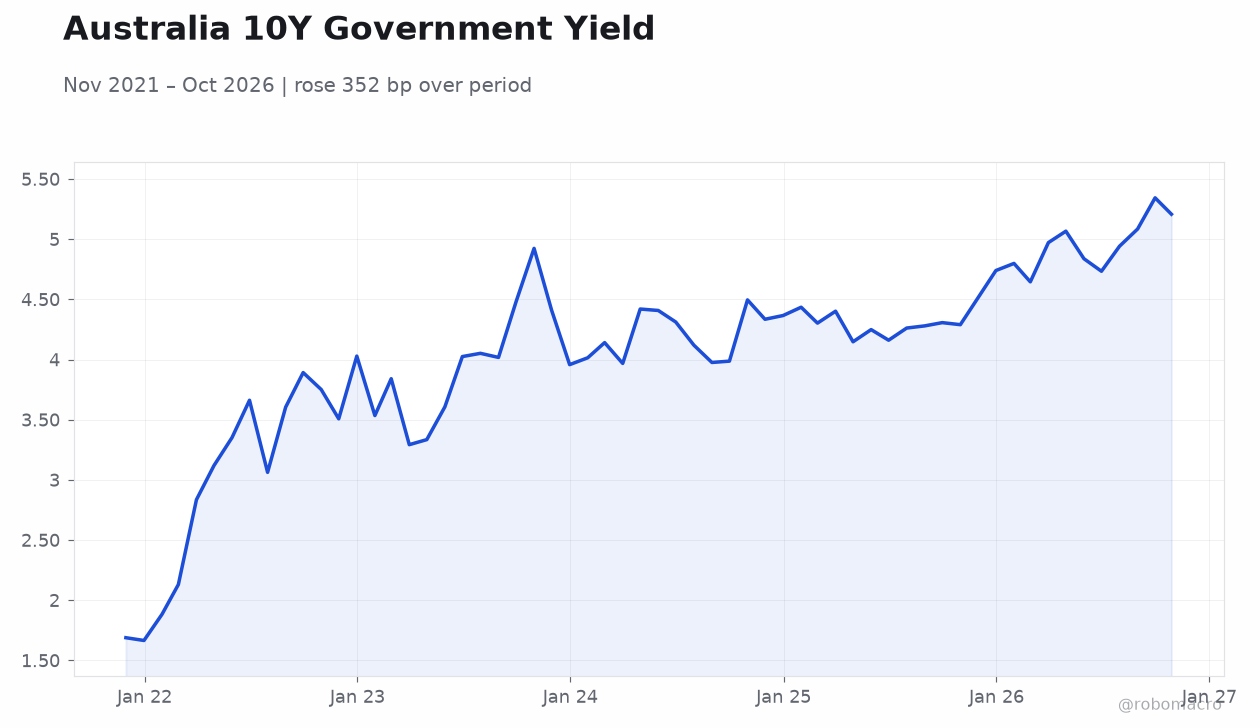
| Australia 10Y Govt Yield | 5.21% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBA Interest Rate Decision | 4.60 | 4.85 | 4.85 |
| RBA Monetary Policy Statement | - | - | - |
| RBA Rate Statement | - | - | - |
| RBA Press Conference | - | - | - |
| Employment Change Quarter-over-Quarter | 0.50 | 0.40 | -0.10 |
| Headline Unemployment Rate | 5.60 | 5.50 | 5.70 |
| Ai Group Industry Index | -24.20 | - | -19.10 |
| Trade Balance | 184m | 800m | 2,826m |
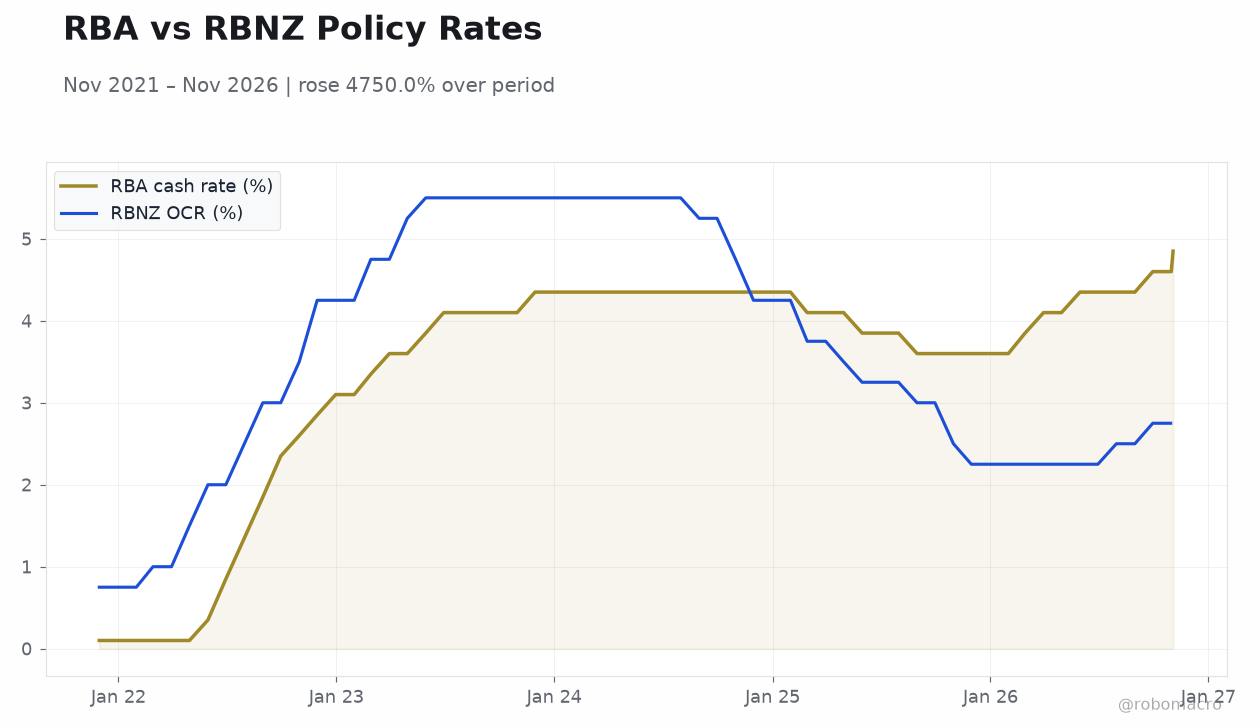 RBA vs RBNZ Policy Rates | Type: macro_line | RBA cash rate (%): 4.85 (2026-11-03) | Range: 0.1–4.85 | Trend(5pt): 0.1,3.35,4.35,3.6,4.85 | RBNZ OCR (%): 2.75 (2026-10-30) | Range: 0.75–5.5 | Trend(5pt): 0.75,4.75,5.5,3,2.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- RBA raised the cash rate to 4.85% at its November 3 decision, a 25 bp increase that nonetheless failed to support AUD as markets priced a slower hiking path ahead.
- New Zealand employment contracted 0.1% q/q in Q3 with unemployment rising to 5.7%, an 11-year high that sharply reduces the odds of a December RBNZ hike.
- Australia's trade surplus blew out to A$2.83bn versus A$0.8bn consensus, while the Ai Group Industry Index improved to -19.1 from -24.2, and the ASX 200 surged 2.61% led by BHP's 6.19% rally.
Yesterday's Recap
The RBA delivered a 25 bp hike on November 3, lifting the cash rate to 4.85% from 4.6%, in line with consensus, alongside its Monetary Policy Statement and a post-meeting press conference. Despite the hike, AUD/USD fell 0.30% to 0.69 as markets judged the tightening cycle near its peak. New Zealand's Q3 labour data printed materially weaker than expected: employment change came in at -0.1% q/q against 0.4% consensus, and the headline unemployment rate rose to 5.7% versus 5.5% expected and 5.6% previously.
Australia's Ai Group Industry Index improved to -19.1 from -24.2, still deep in contraction territory. The Australian trade balance printed a surplus of A$2.83bn, far exceeding the A$0.8bn consensus and the prior A$184m. Domestic equities rallied hard, with the ASX 200 up 2.61% to 9,065.10 and BHP jumping 6.19% to A$59.00, while the NZX 50 added 0.84%.
Australian yields pushed higher, with the 2-year up 7 bp to 4.95% and the 10-year up 6 bp to 5.21%.
The Day Ahead
No tier-one Australian or New Zealand data releases are scheduled for today, leaving markets to digest the RBA decision and the weak NZ labour print. Attention turns to second-tier Australian activity indicators later in the week and any RBA commentary following the hike. NZD/USD traders will watch for RBNZ speak after the employment shock materially shifted rate expectations.
Australian housing data remains a key watch item given the WSJ's framing of a deepening housing slump as the RBA tightens further. Regional sentiment will also take a cue from Chinese demand signals for iron ore and coal, with BHP's rally suggesting miners are pricing resilient commodity demand.
Other Economic Notes
Australia's trade surplus strength underscores continued commodity export resilience, though the composition matters for AUD given iron ore and LNG price sensitivity to Chinese demand. The Ai Group index at -19.1 signals manufacturing and construction remain under pressure from higher rates. ↓ p.2