ANZ Macro Daily(Beta Mode)
RBA Minutes, RBNZ FSR Take Center Stage
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| ASX 200 | 9,044.70 | -0.41% |
| NZX 50 | 14,303.77 | +0.92% |
| AUD/USD | 0.67 | -0.97% |
| NZD/USD | 0.55 | -0.77% |
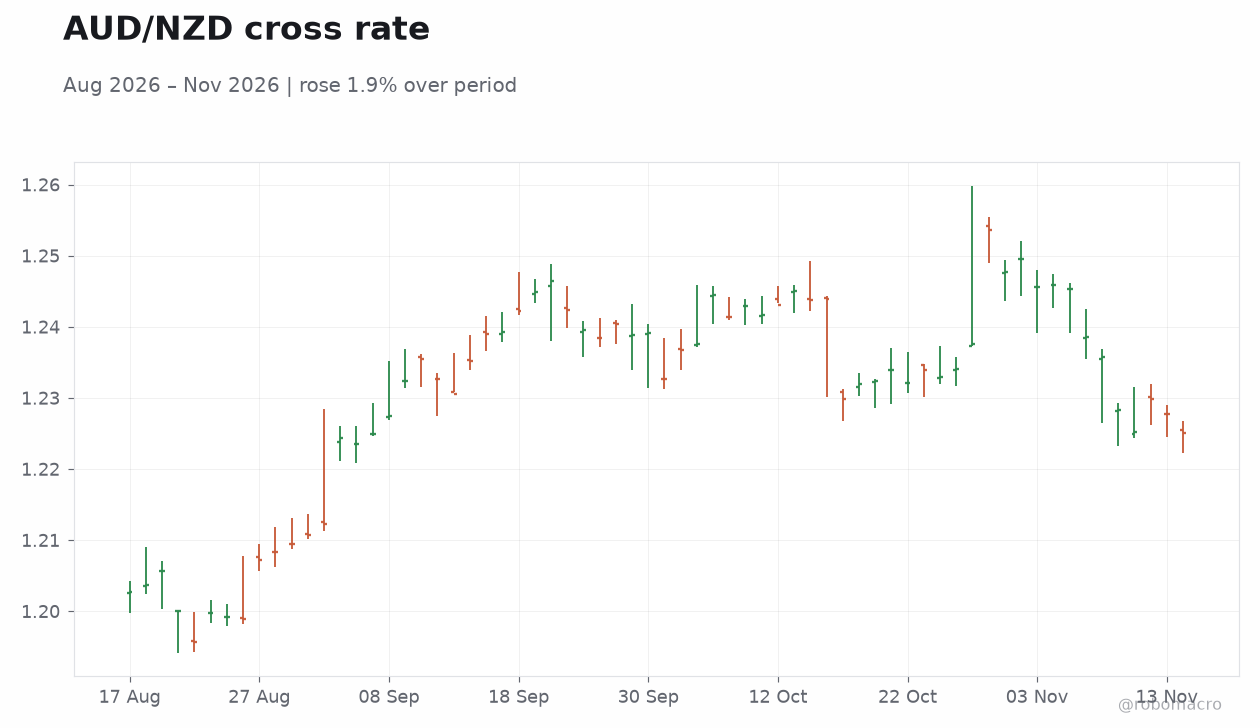
| AUD/NZD | 1.22 | -0.22% |
| BHP | 58.86 | -1.26% |
| Gold | 3,857.20 | -0.75% |
| Brent Crude | 92.37 | -3.62% |
| Bitcoin | 64,951.03 | -0.54% |
| Australia 2Y Govt Yield | 4.81% | +7 bp |
| Australia 10Y Govt Yield | 5.04% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
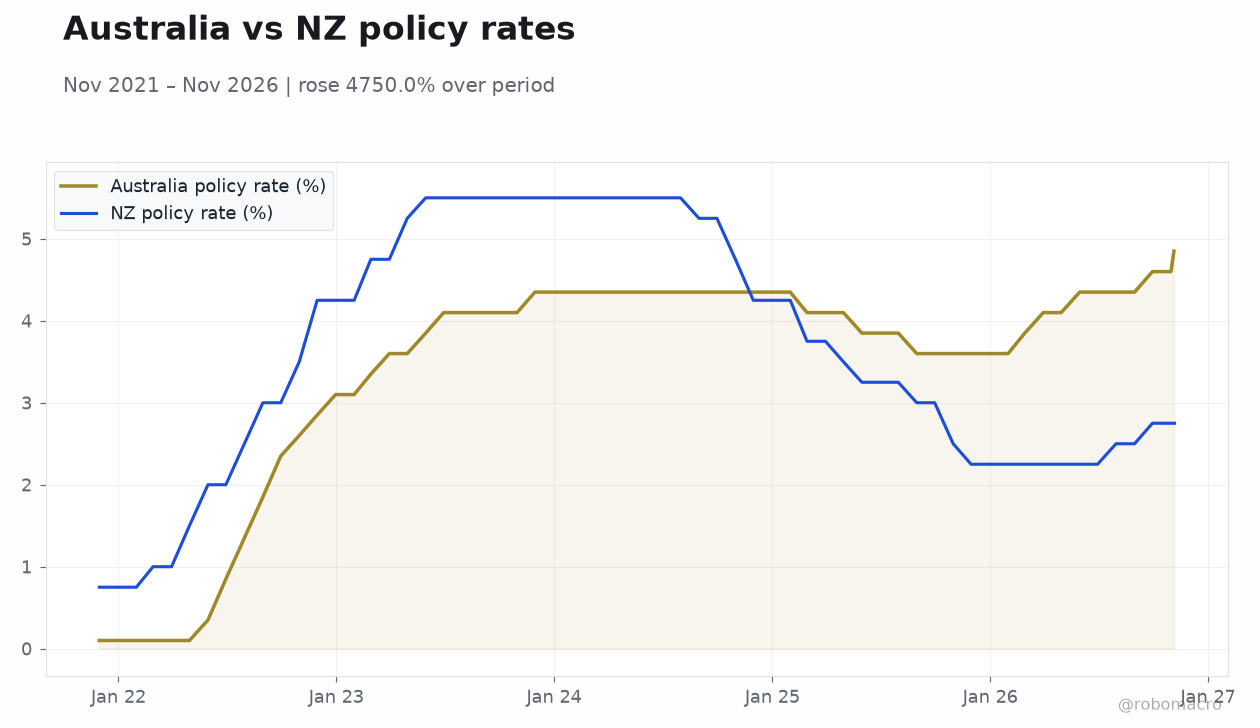 Australia vs NZ policy rates | Type: macro_line | Australia policy rate (%): 4.85 (2026-11-05) | Range: 0.1–4.85 | Trend(5pt): 0.1,3.35,4.35,3.6,4.85 | NZ policy rate (%): 2.75 (2026-11-06) | Range: 0.75–5.5 | Trend(5pt): 0.75,4.75,5.5,3,2.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| RBNZ Financial Stability Report | - | - | 15:00 |
| RBNZ Press Conference | - | - | 19:00 |
| RBA Meeting Minutes | - | - | 19:30 |
- RBA releases minutes of its 3 November decision, which delivered a +25bp hike to a 4.85% cash rate; markets watch for the tightening bias and any signal on a December move.
- RBNZ publishes its Financial Stability Report and holds a press conference, with the OCR at 2.75% after the September hike and a 9 December review pending.
- AUD/USD fell 0.97% to 0.67 and NZD/USD dropped 0.77% to 0.55 as hawkish Fed expectations weighed on both currencies; Australian 2Y and 10Y yields rose 7bp and 5bp respectively.
Yesterday's Recap
Friday's session was risk-off across ANZ markets, with no tier-one data releases in either Australia or New Zealand. The ASX 200 slipped 0.41% to 9,044.70, weighed by BHP's 1.26% decline to 58.86 as iron ore sentiment softened, while the NZX 50 bucked the trend with a 0.92% gain to 14,303.77. Currency markets were the sharper story: AUD/USD fell 0.97% to 0.67 and NZD/USD dropped 0.77% to 0.55, with AUD/NZD easing 0.22% to 1.22 as the kiwi outperformed marginally on the cross.
Australian rates sold off, with the 2-year yield up 7bp to 4.81% and the 10-year up 5bp to 5.04%, reflecting firming expectations for further RBA tightening after the November hike. Commodities added to the negative tone, with Brent crude down 3.62% to 92.37 and gold off 0.75% at 3,857.20. Bitcoin was little changed, down 0.54% at 64,951.
The Day Ahead
The calendar is dominated by central bank communication from both sides of the Tasman. The RBNZ releases its Financial Stability Report at 15:00 ET, followed by a press conference at 19:00 ET — high-impact events that will be scrutinised for the Reserve Bank's read on housing, credit conditions and financial system resilience. The RBA publishes minutes of its 3 November meeting at 19:30 ET, high-impact given the decision delivered a +25bp hike to 4.85%.
Markets will parse the minutes for the committee's inflation assessment and the likelihood of a follow-up move at the 8 December meeting. No Australian or New Zealand data prints are scheduled for tomorrow.
Other Economic Notes
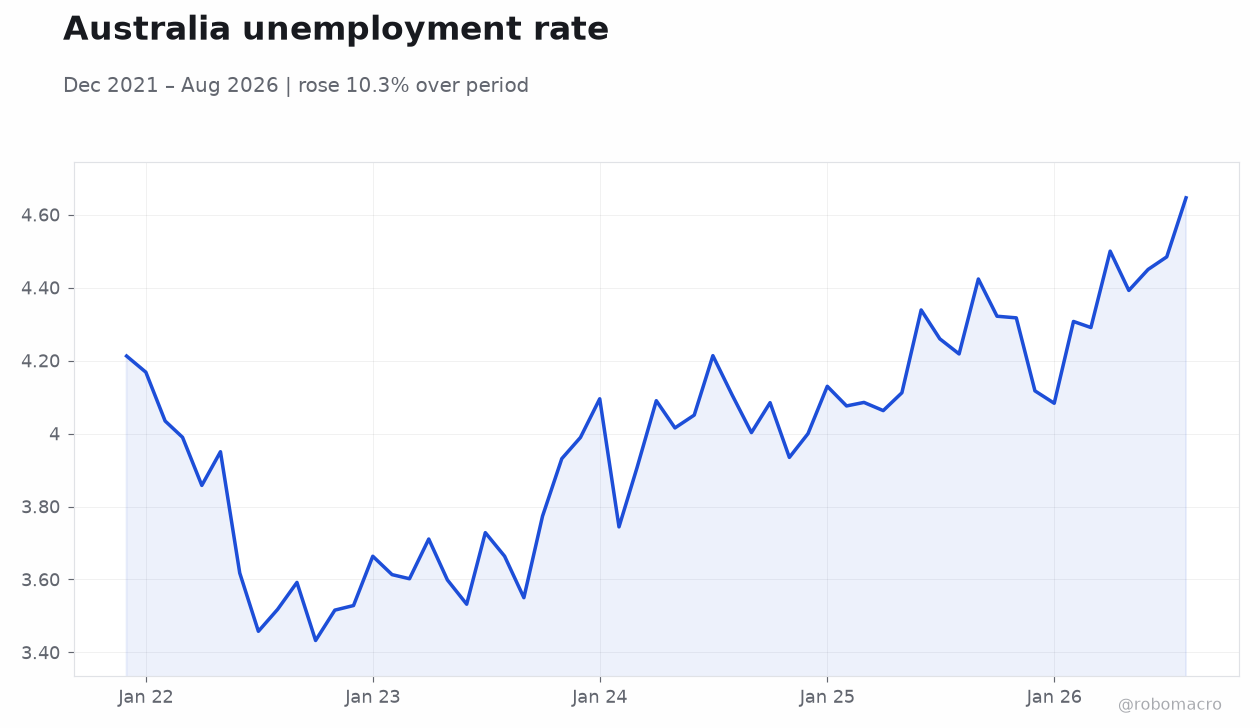
Australian and New Zealand inflation remain above target, with CPI at 3.90% y/y in Australia and 3.70% y/y in New Zealand as of the September quarter. Commentary around the RBA has turned to whether the tightening cycle is complete, with Westpac among the banks arguing the RBA is ready to "clock off" for 2026 — a view the minutes will test. Australia's inflation-targeting credibility is under debate, with critics arguing weak public trust raises the cost of disinflation.
The Australian dollar debt market is having a bumper 2026, with structural shifts among issuers and investors deepening the market. ↓ p.2