ASEAN Macro Daily(Beta Mode)
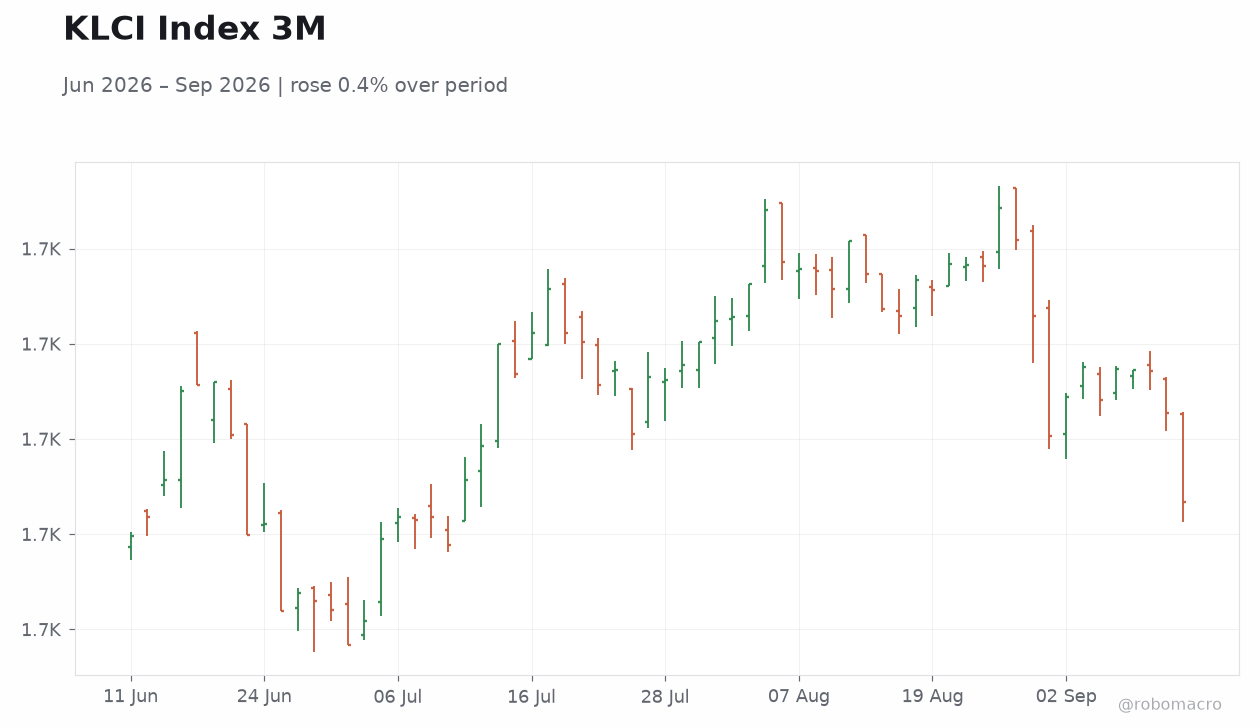
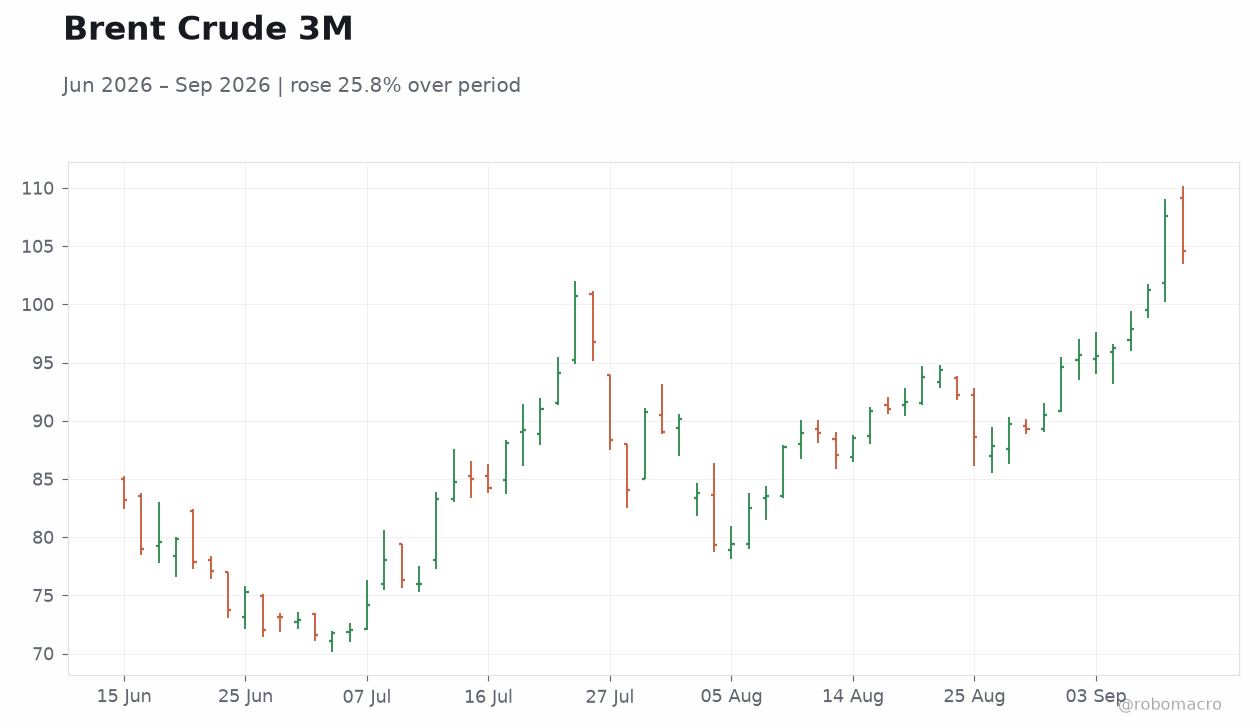
KLCI Slides as Oil Tops $100, Rupiah Swings
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JCI | 6,541.38 | -0.73% |
| KLCI | 1,686.74 | -1.10% |
| STI | 5,695.93 | +0.11% |
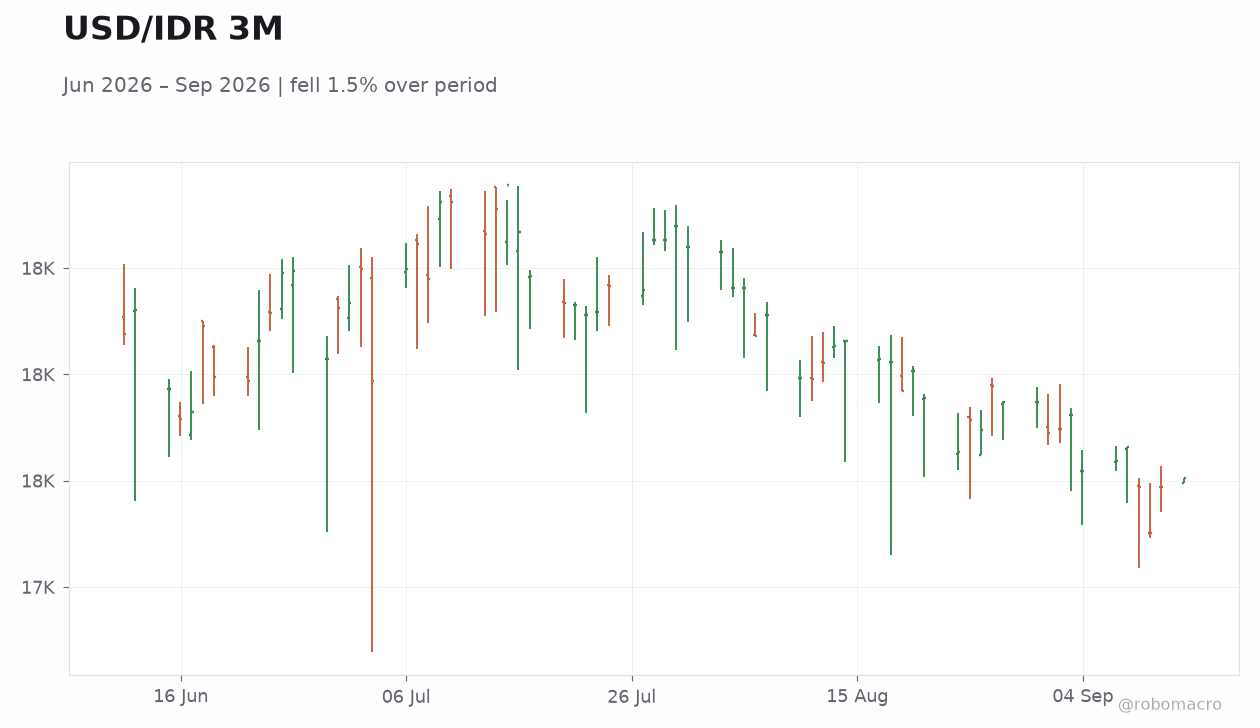
| USD/IDR | 17,606.00 | +0.10% |
| USD/THB | 33.04 | -0.33% |
| USD/MYR | 4.07 | +0.11% |
| USD/PHP | 62.60 | -0.04% |
| USD/SGD | 1.27 | -0.17% |
| Brent Crude | 104.61 | -2.81% |
| Gold | 4,408.90 | +1.02% |
| Bitcoin | 76,976.14 | -0.38% |
| Indonesia 10Y Govt Yield | - | - |
| Thailand 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
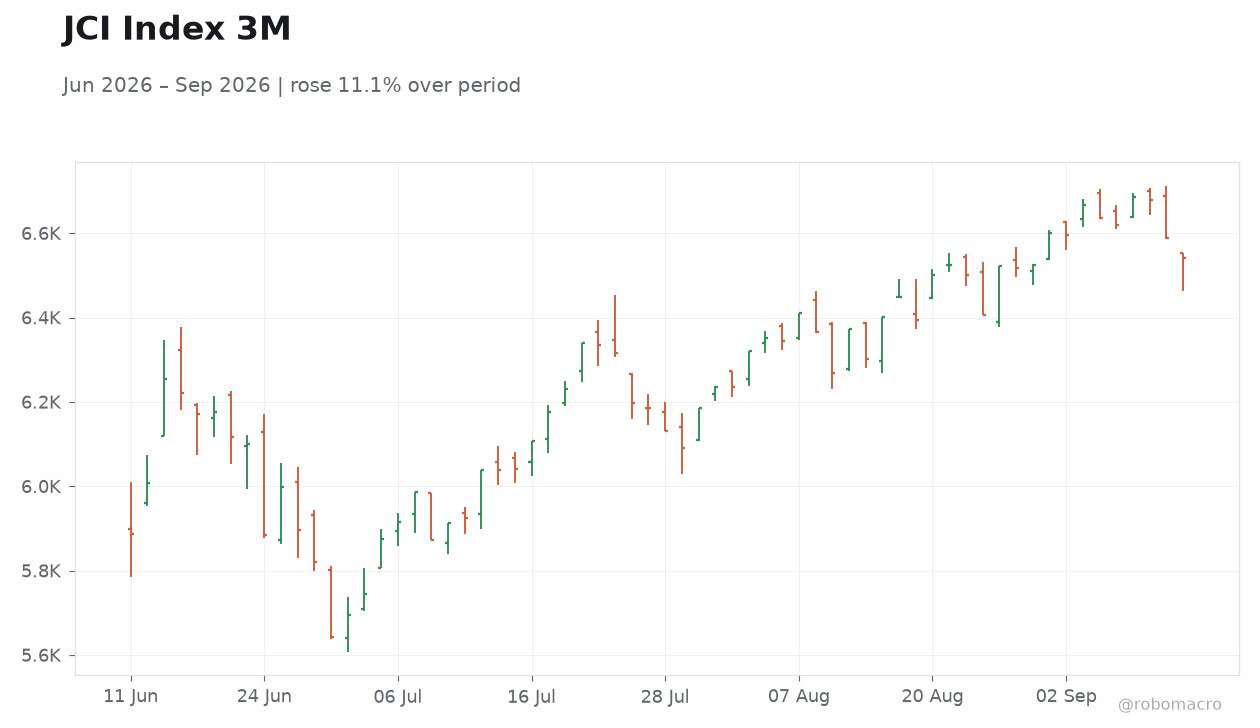 JCI Index 3M | Type: market_hloc | Index Level: 6541 (2026-09-11) | Range: 5643–6686 | Trend(5pt): 5886,5916,6131,6502,6541
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0 | - | 00:00 |
| Inflation Rate Year-over-Year | 1.80 | - | 00:00 |
- Indonesian equities fell 0.73% while KLCI dropped 1.10% amid foreign outflows and oil above $100.
- Bank Indonesia advanced local-currency settlement talks at the BRICS summit as rupiah volatility persisted.
- Malaysia inflation data due 18 September; Thailand regulators tightened stablecoin and illicit-finance rules.
Yesterday's Recap
Equity markets closed mixed across ASEAN on 12 September. JCI fell 0.73% to 6,541.38 while KLCI declined 1.10% to 1,686.74 on foreign equity outflows. STI edged 0.11% higher to 5,695.93.
USD/IDR rose 0.10% to 17,606 while USD/MYR gained 0.11% to 4.07; USD/THB eased 0.33% to 33.04. Brent crude dropped 2.81% to 104.61, lifting gold 1.02% to 4,408.90. Indonesia retail sales rebounded in July yet durability remains uncertain amid high oil prices.
Thailand’s Bank of Thailand and regulators stepped up scrutiny of USDT inflows and proposed daily caps on same-owner stablecoin transfers to curb laundering risks. No economic releases occurred on 12 September.
The Day Ahead
Malaysia will publish July inflation figures on 18 September, covering both month-over-month and year-over-year rates. No other data releases, central-bank meetings or auctions are scheduled across the six ASEAN economies through 14 September. Indonesia continues preparations for a second phase of Russian oil imports while monitoring rupiah pressure.
Thailand’s focus remains on tightening customer due-diligence rules with commercial banks. Vietnam and the Philippines report no near-term macro events. Singapore MAS maintains its exchange-rate band policy with no scheduled review.
Other Economic Notes
Oil above $100 raises Indonesia’s subsidy and current-account risks while supporting export revenues from palm oil and coal. President Prabowo highlighted Indonesia’s BRICS role, reinforcing Bank Indonesia’s push for local-currency trade settlement to reduce USD dependence. PT PP’s restructuring of 18.2 trillion rupiah in bank loans adds to sovereign-wealth-fund Danantara’s cleanup burden.
Thailand’s crypto inflows of 500–600 billion baht in the first half underscore capital-flow management challenges. Broader ASEAN growth remains supported by supply-chain shifts from China, though high oil prices and global tightening weigh on sentiment. Poverty metrics show divergence between official BPS figures at 8.07% and World Bank estimates at 64.1%.