ASEAN Macro Daily(Beta Mode)
Rupiah Weakens as Oil Tops $106
Market Snapshot
| Asset | Level | Change |
|---|---|---|
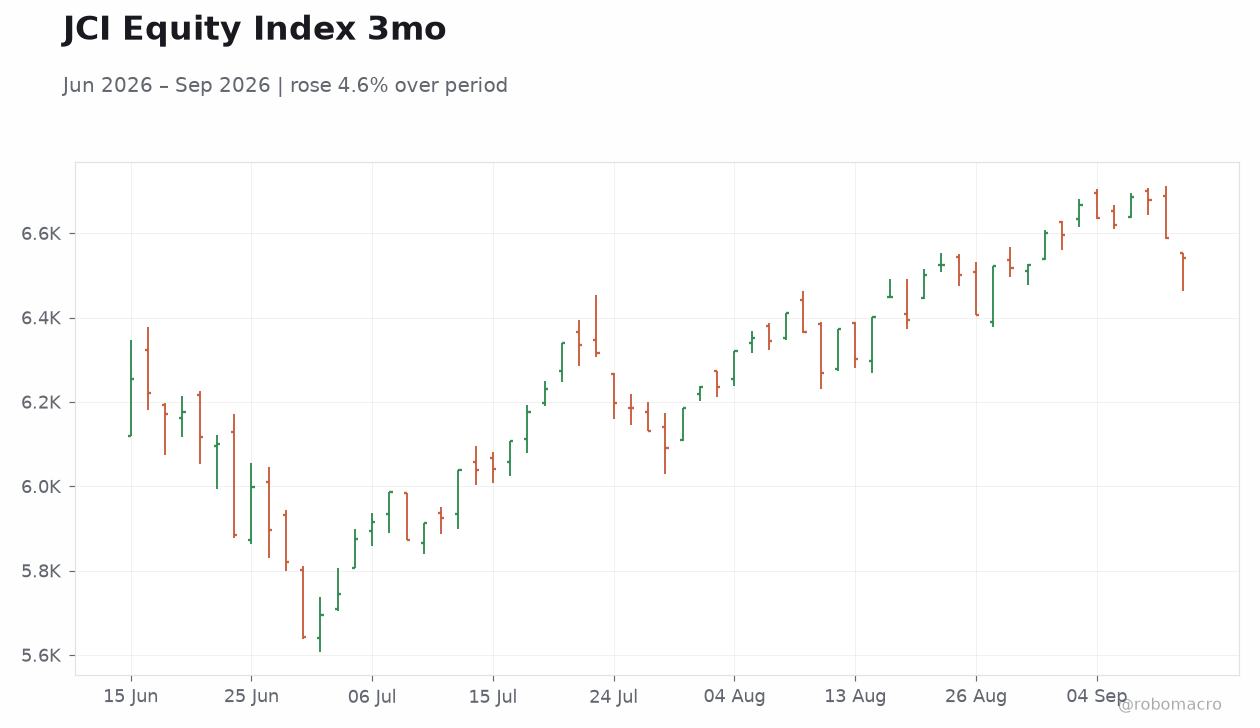
| JCI | 6,541.38 | -0.73% |
| KLCI | 1,686.74 | -1.10% |
| STI | 5,695.93 | +0.11% |
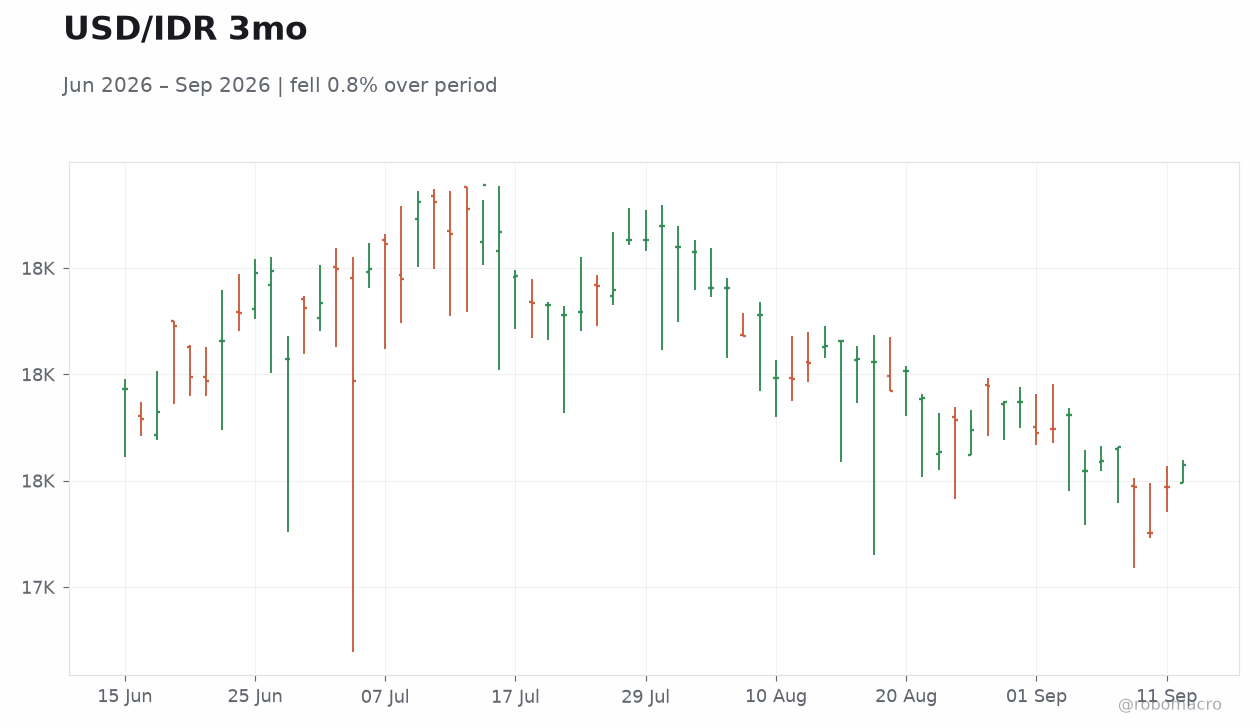
| USD/IDR | 17,630.00 | +0.24% |
| USD/THB | 33.18 | +0.09% |
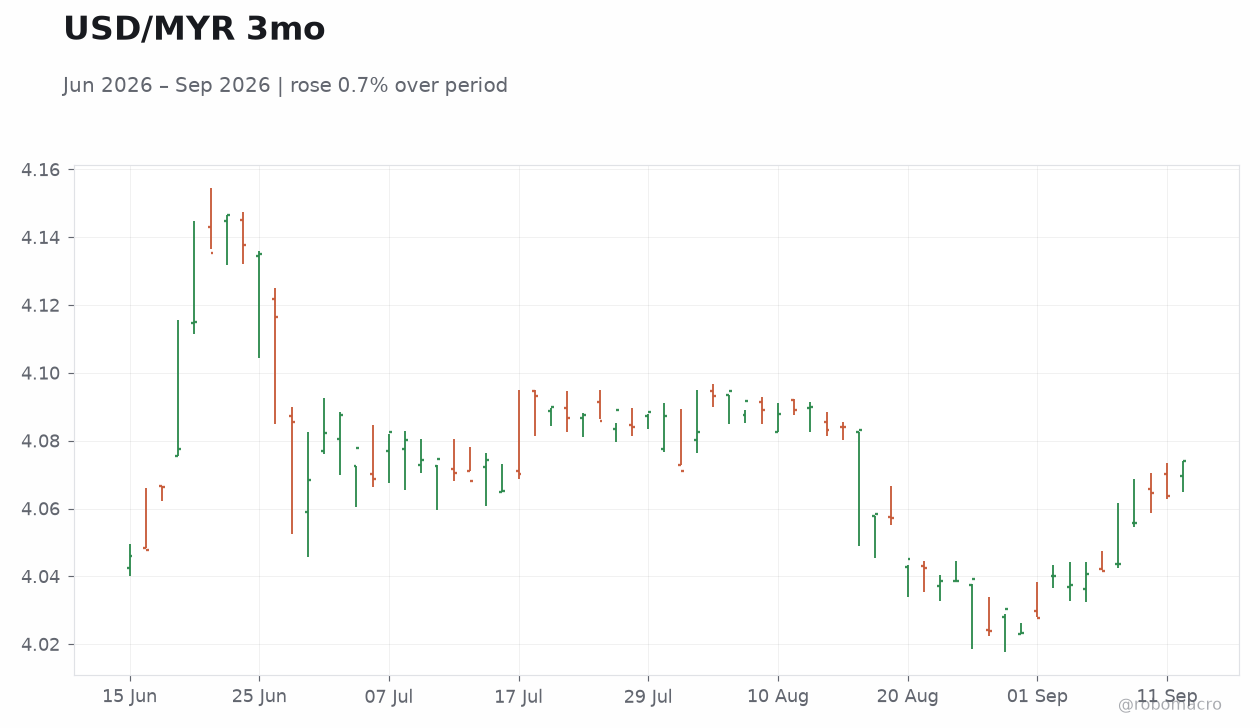
| USD/MYR | 4.07 | +0.25% |
| USD/PHP | 62.82 | +0.31% |
| USD/SGD | 1.27 | +0.16% |
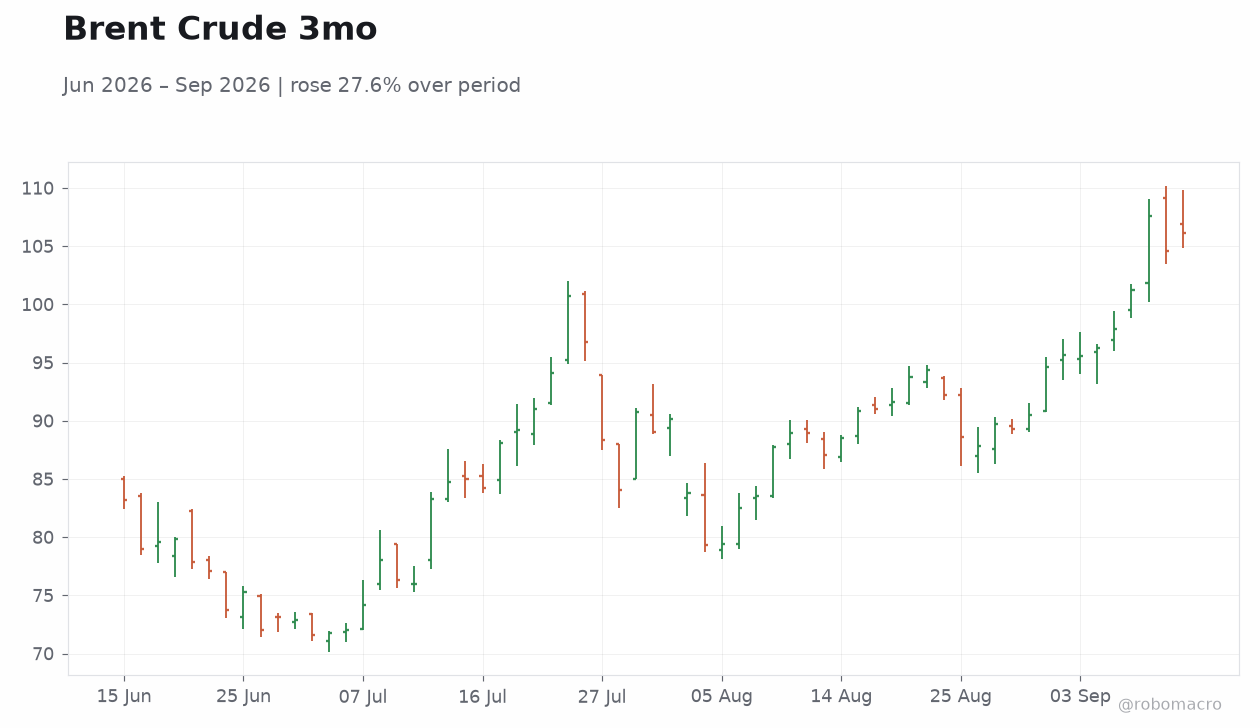
| Brent Crude | 106.15 | +1.47% |
| Gold | 4,340.00 | -1.56% |
| Bitcoin | 78,734.69 | +2.47% |
| Indonesia 10Y Govt Yield | - | - |
| Thailand 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
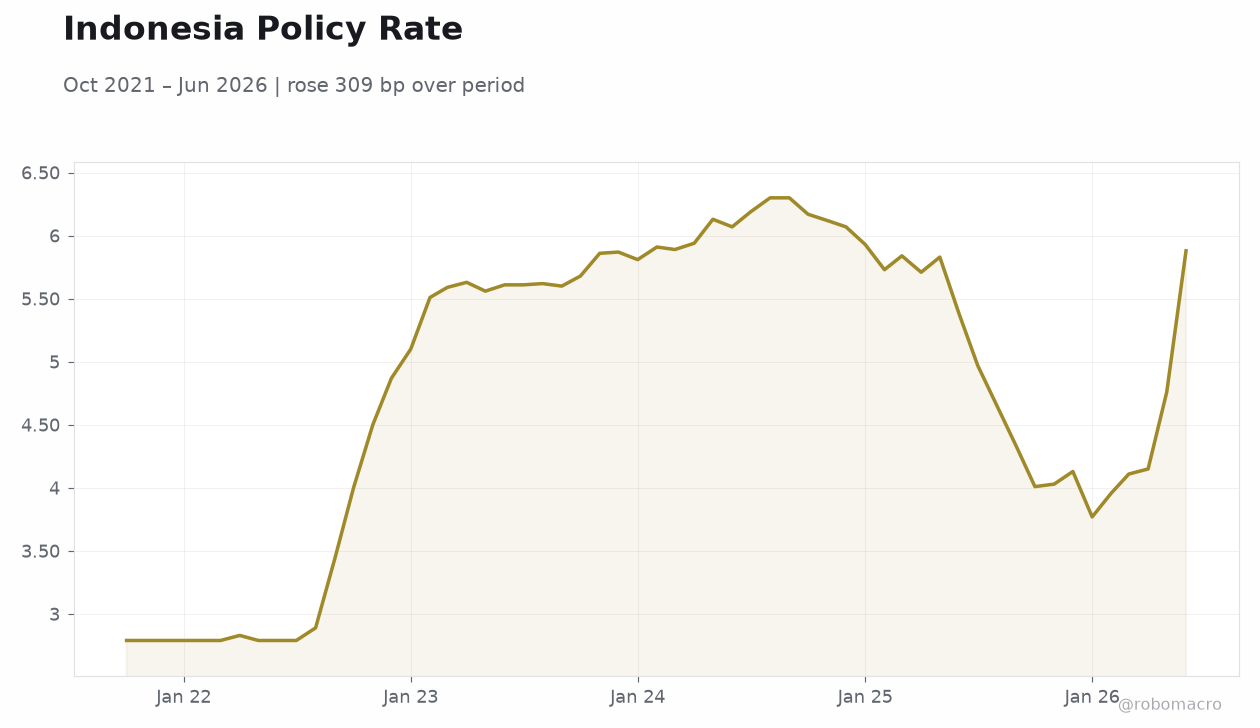 Indonesia Policy Rate | Type: macro_line | Policy Rate %: 5.88 (2026-06-01) | Range: 2.79–6.3 | Trend(5pt): 2.79,4.87,5.91,5.71,5.88
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0 | - | 20:00 |
| Inflation Rate Year-over-Year | 1.80 | 1.80 | 20:00 |
- Indonesia’s rupiah slips 0.24% to 17,630 as Brent crude surges past $106 on supply concerns
- ASEAN equities mixed: KLCI falls 1.10% while STI rises 0.11%; most regional currencies weaken versus USD
- Malaysia August inflation data due 17 September; no major releases across ASEAN yesterday
Yesterday's Recap
Indonesia dominated market moves as the rupiah weakened against a stronger dollar and Brent crude climbed 1.47% to 106.15. USD/IDR rose 0.24% to 17,630 while USD/MYR and USD/PHP also advanced. Indonesia’s JCI fell 0.73% to 6,541.38 and Malaysia’s KLCI dropped 1.10% to 1,686.74.
State-linked builder PT PP announced plans to restructure 18.2 trillion rupiah in bank debt. Bank Indonesia promoted greater use of local currencies in BRICS trade settlements. Thailand’s Bank of Thailand flagged 500–600 billion baht in half-year USDT inflows and signalled tighter scrutiny of crypto-related flows.
Singapore’s STI edged 0.11% higher to 5,695.93. No economic releases occurred on 13 September across the six ASEAN economies. Indonesia’s July retail-sales rebound was noted in commentary but no fresh print was published yesterday.
The Day Ahead
Malaysia will release August inflation figures on 17 September, with consensus expecting the year-over-year rate to hold at 1.8%. No central-bank meetings, bond auctions or major data releases are scheduled for 15–16 September across the six ASEAN economies. Thailand’s focus remains on curbing illicit finance after recent regulatory coordination among eleven agencies.
Indonesia continues to monitor oil-price effects on its current account and retail-sales momentum following the July rebound. Vietnam and the Philippines have no high-impact events listed in the near term. Elevated oil prices above $106 raise import costs for Indonesia and widen its current-account gap, pressuring the rupiah further.
Other Economic Notes
Elevated oil prices above $106 raise import costs for Indonesia and widen its current-account gap, pressuring the rupiah further. Thailand’s tightening of customer checks on crypto inflows highlights growing capital-flow management challenges amid stablecoin adoption. Broader ASEAN supply-chain shifts continue as firms diversify away from China, benefiting Vietnam’s manufacturing FDI while exposing commodity-linked economies such as Indonesia to price volatility.
Regional equity outflows have weighed on the ringgit despite the Bank Negara Malaysia’s hawkish tone. Indonesia remains exposed to oil-price volatility; Brent above 106 raises import costs and widens the current-account gap, according to market commentary.