ASEAN Macro Daily(Beta Mode)
Rupiah Weakens Ahead of BI Policy Outlook
Market Snapshot
| Asset | Level | Change |
|---|---|---|
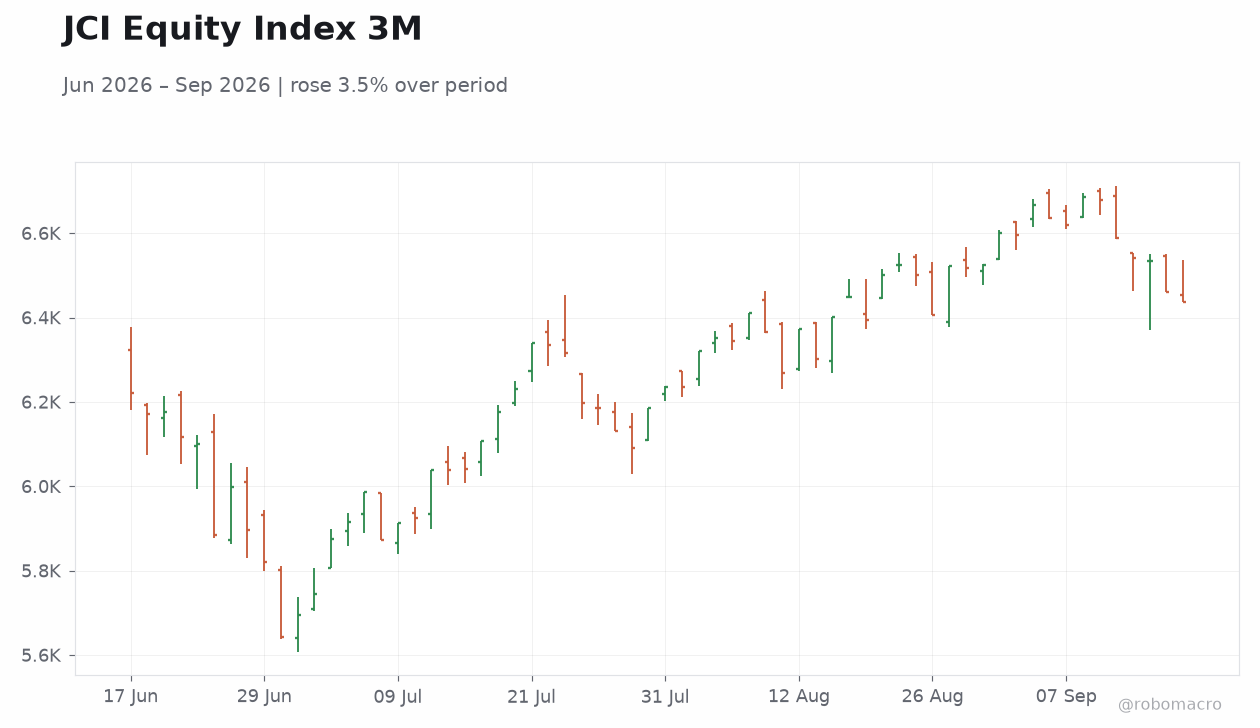
| JCI | 6,436.85 | -0.38% |
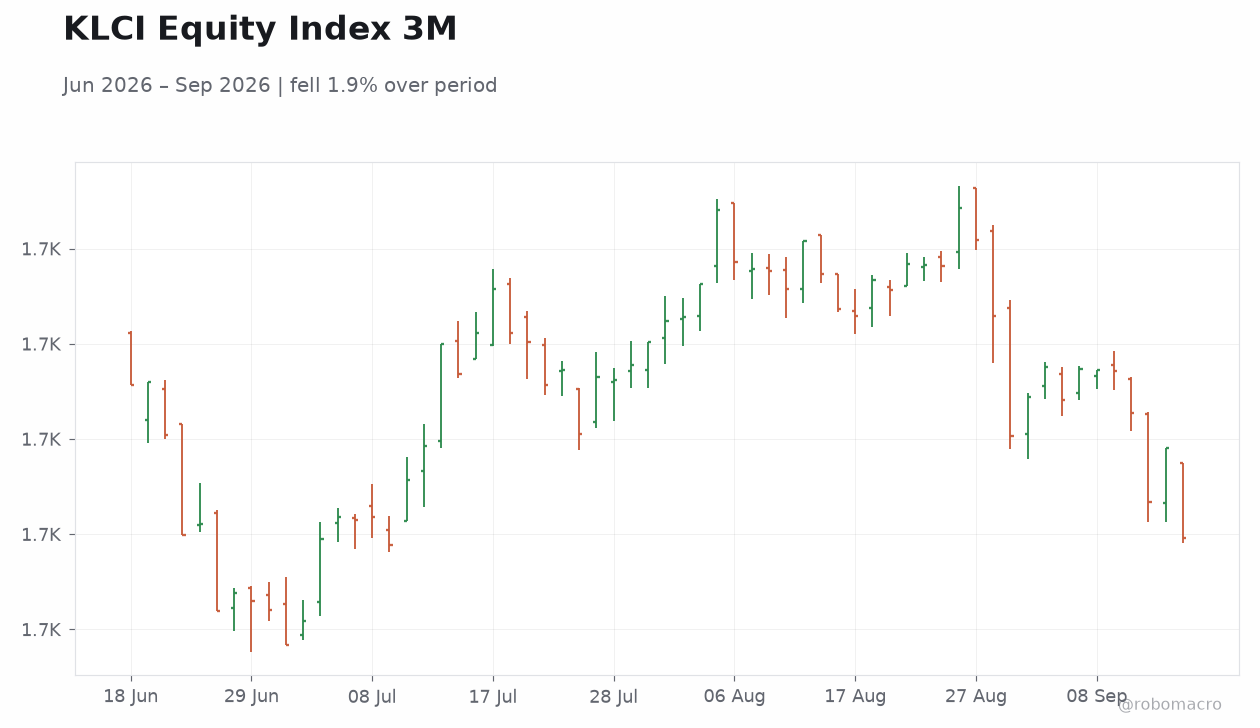
| KLCI | 1,679.21 | -1.11% |
| STI | 5,635.41 | -0.06% |
| USD/IDR | 17,748.00 | +0.47% |
| USD/THB | 33.26 | -0.09% |
| USD/MYR | 4.10 | +1.34% |
| USD/PHP | 62.74 | +0.00% |
| USD/SGD | 1.28 | +0.20% |
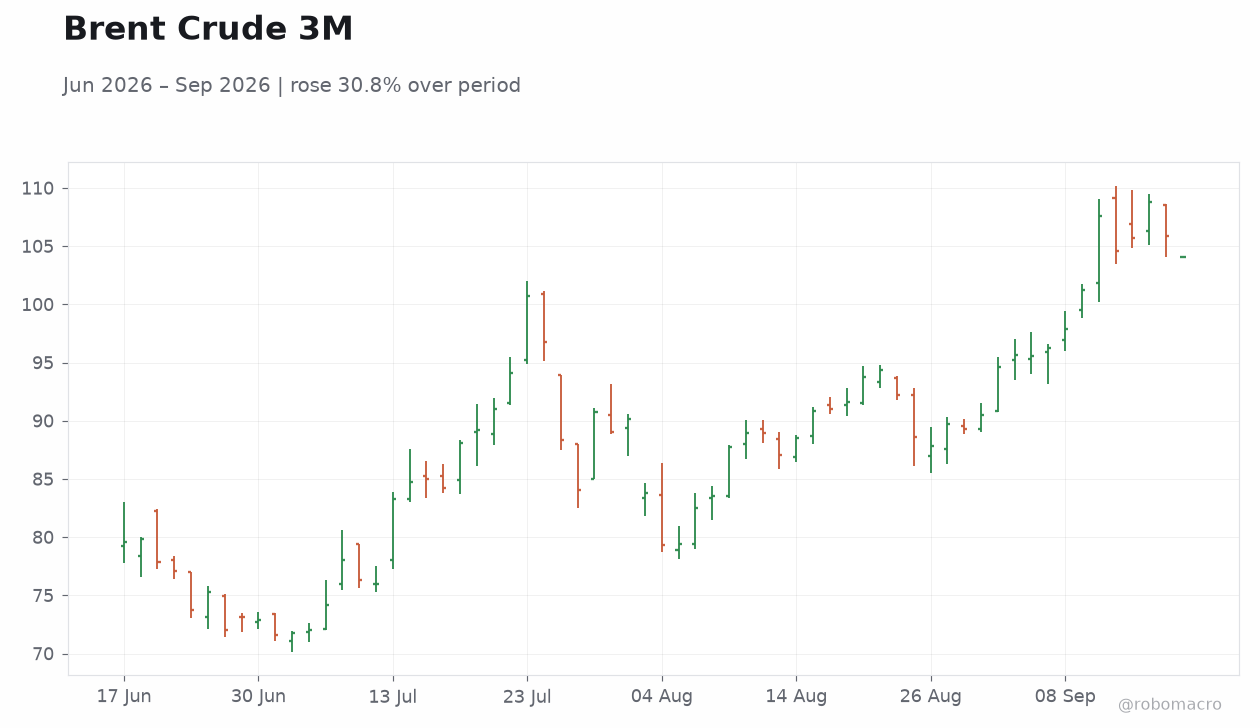
| Brent Crude | 104.09 | -1.64% |
| Gold | 4,380.60 | -0.16% |
| Bitcoin | 76,398.24 | +0.33% |
| Indonesia 10Y Govt Yield | - | - |
| Thailand 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
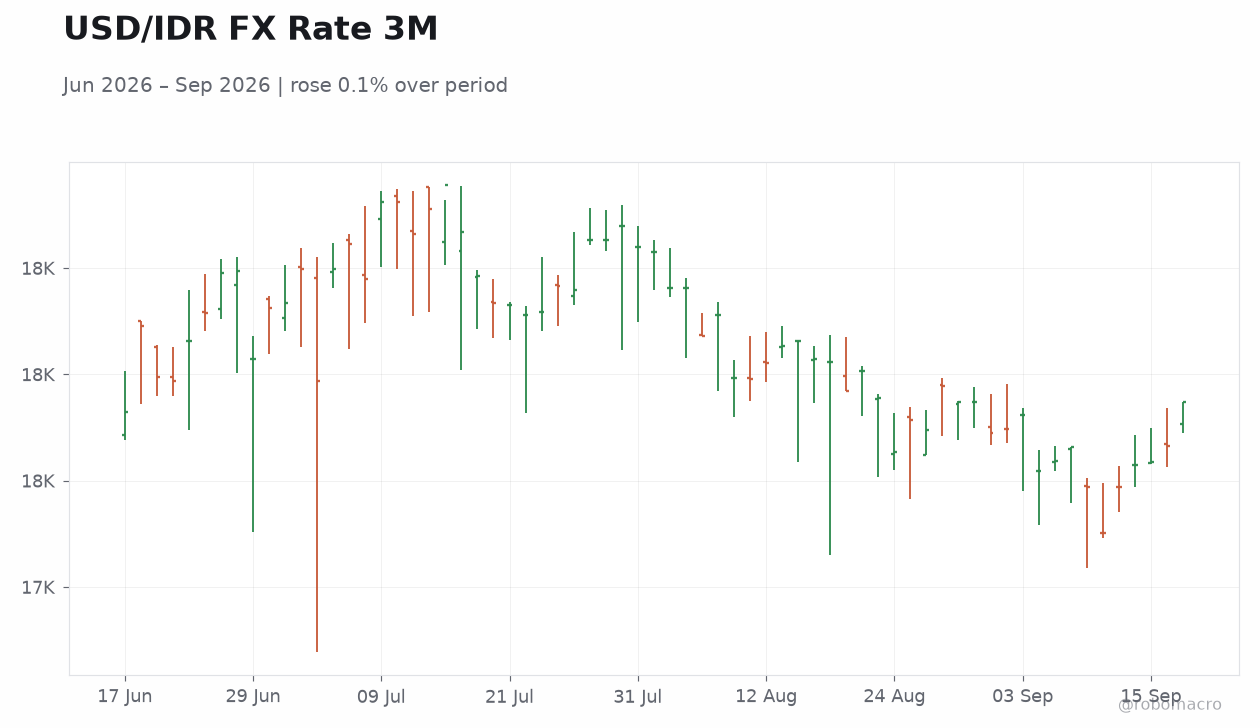 USD/IDR FX Rate 3M | Type: market_hloc | IDR per USD: 1.775e+04 (2026-09-17) | Range: 1.75e+04–1.816e+04 | Trend(6pt): 1.773e+04,1.812e+04,1.804e+04,1.766e+04,1.764e+04,1.775e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0 | - | 00:00 |
| Inflation Rate Year-over-Year | 1.80 | 1.80 | 00:00 |
| Central Bank Interest Rate Decision | 5.75 | - | 03:30 |
- Rupiah slides on Fed hike expectations and Washington news flow
- KLCI drops 1.11% while regional equities finish mixed to lower
- Malaysia inflation prints and BI policy decision dominate the near-term calendar
Yesterday's Recap
Regional equities closed lower on 16 September, with Indonesia’s JCI falling 0.38% to 6,436.85, Malaysia’s KLCI declining 1.11% to 1,679.21 and Singapore’s STI easing 0.06% to 5,635.41. The rupiah came under pressure as USD/IDR rose 0.47% to 17,748 amid reports of a possible final 2026 Fed rate increase and fresh news from Washington. USD/MYR jumped 1.34% to 4.10 while USD/THB slipped 0.09% to 33.26 and USD/SGD added 0.20% to 1.28.
Thailand’s electronics export boom continued to provide only limited support to the baht according to MUFG analysis. Indonesia secured additional crude supplies, including Russian volumes, to safeguard energy security. No major macro data releases occurred across the six ASEAN economies on the day.
The Day Ahead
Malaysia will release August inflation data on 18 September, with the year-over-year rate expected to hold at 1.8%. Bank Indonesia’s policy meeting on 23 September carries heightened market focus given recent rupiah softness. Thailand’s energy minister highlighted efforts to diversify crude imports away from the Middle East.
No bond auctions or high-impact releases are scheduled for the Philippines, Singapore or Vietnam. Traders will also monitor any updates on Malaysia’s bilateral swap arrangement with Japan.
Other Economic Notes
Thailand faces warnings of potential fiscal strain within a decade absent urgent reforms, while the government has signed a global minimum tax information exchange agreement. Indonesia’s cross-border QRIS partnerships are expanding to four additional countries, supporting regional payment connectivity. China-US supply chain shifts continue to underpin manufacturing relocation interest toward Vietnam and Malaysia.
Wildfires in Indonesia threaten both economic output and emerging carbon-market revenues. Brent crude’s 1.64% decline to 104.09 eased some immediate energy-cost pressures across the region.
Global Macro News
Markets priced in a possible final 2026 Fed rate hike, adding to external pressure on ASEAN currencies. The US dollar strengthened against most regional units, with USD/IDR prints near 17,753 cited in local reports. Gold slipped 0.16% to 4,380.60 while Bitcoin edged 0.33% higher to 76,398.24.
Broader risk sentiment remained cautious ahead of the FOMC decision. ↓ p.2