RoboMacro ResearchAlso todaySee the Commodities Daily

ASEAN Macro Daily(Beta Mode)

November 04, 2026 robomacro.com

Rupiah, Ringgit Diverge Ahead of BI, BNM Decisions

JCI5,096.83+0.79%
KLCI1,619.51+0.24%
STI5,303.83-1.36%
USD/IDR18,148.00+0.19%

Market Snapshot

AssetLevelChange
JCI5,096.83+0.79%
KLCI1,619.51+0.24%
STI5,303.83-1.36%
USD/IDR18,148.00+0.19%
USD/THB33.76+0.18%
USD/MYR4.07+0.48%
USD/PHP63.49-0.12%
USD/SGD1.28+0.25%
Brent Crude104.42-0.33%
Gold3,940.20-0.74%
Bitcoin77,730.00+1.37%
Indonesia 10Y Govt Yield--
Thailand 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
No events available
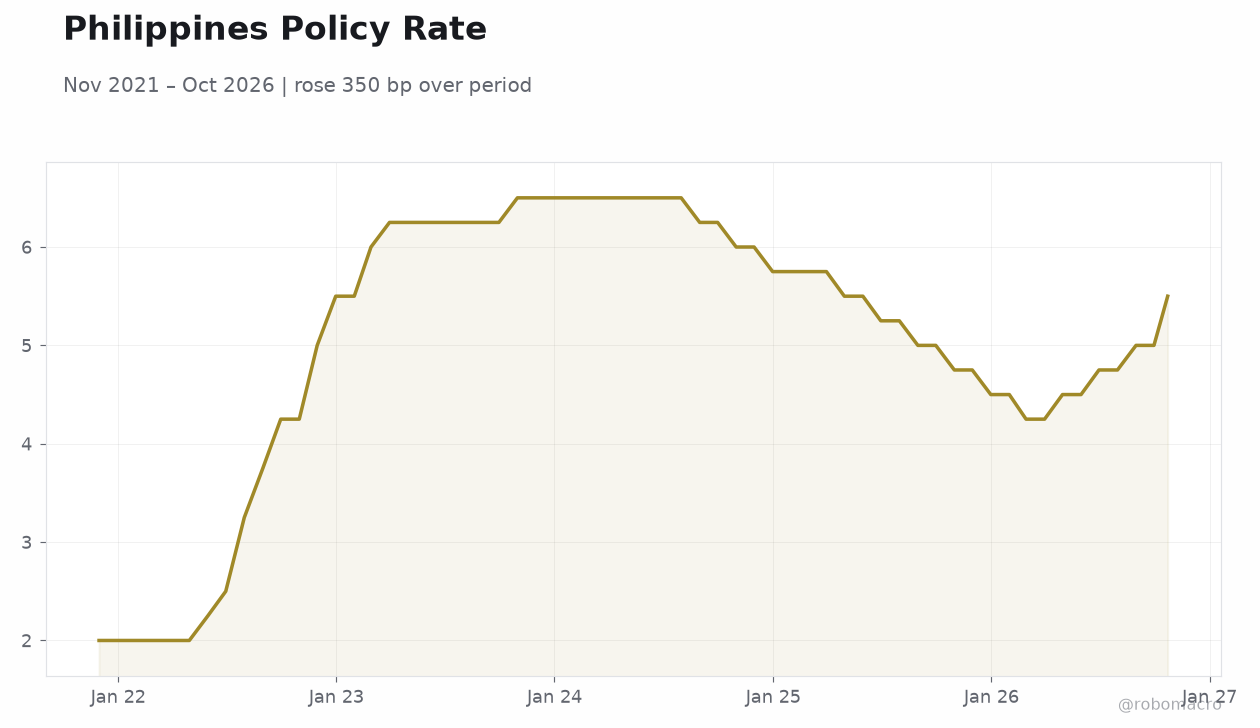
Philippines Policy RatePhilippines Policy Rate | Type: macro_line | BSP policy rate (%): 5.5 (2026-10-23) | Range: 2–6.5 | Trend(5pt): 2,6,6.5,5,5.5

Today's Economic Events

Data Prior Cons Time
Wednesday (2026-11-04)
Inflation Rate Year-over-Year7.20-20:00
GDP Growth Year-over-Year5.29-23:00
  • Indonesian rupiah weakens past 18,100/USD as mixed data and fiscal concerns offset a $3.36bn September trade surplus; BI prioritises FX stability ahead of its 18 November meeting.
  • Malaysian ringgit firms ahead of Bank Negara's OPR decision, with markets pricing "normalisation" even as BNM's policy rate sits at 2.75%.
  • Singapore's STI drops 1.36% as bank shares drag; regional equities mixed, with JCI up 0.79% despite MSCI-related anxiety.

Yesterday's Recap

Indonesia dominated the ASEAN tape, with Bank Indonesia confirming a $3.36bn trade surplus for September and framing it as a buffer for external stability, even as the rupiah weakened on mixed economic figures and persistent fiscal and external risk concerns. USD/IDR pushed to 18,148 (+0.19%), extending its grind higher, while Jakarta's JCI defied the currency softness with a 0.79% gain to 5,096.83. MSCI's warning on Indonesian market accessibility continued to generate pushback from officials and commentators, though it weighed on sentiment and equity flows.

In Malaysia, the ringgit opened higher on expectations of policy normalisation ahead of BNM's decision, with USD/MYR at 4.07 (+0.48% on the day). Singapore was the regional laggard, the STI falling 1.36% to 5,303.83 as bank stocks dragged the index lower. Thailand's baht was steady-to-softer at 33.76/USD (+0.18%), with Bangkok's cabinet approving a steep excise tax hike on fully imported EVs to 35% from 10% effective January — a structural shift for its autos hub.

The Philippine peso was the outlier, firming 0.12% to 63.49/USD even as local commentary debated consumption culture's role in the currency's weakness.

The Day Ahead

The calendar pivots to two tier-one ASEAN prints on Wednesday 4 November: Philippine inflation for October (previous 7.2% y/y) at 20:00 ET and Indonesian Q3 GDP growth (previous 5.29% y/y) at 23:00 ET. The Philippine CPI print is the more market-sensitive of the two, given the peso's recent weakness and the central bank's inflation-fighting posture; a downside surprise would ease pressure on the BSP. Indonesia's GDP release will be scrutinised for domestic demand resilience amid a softer rupiah and tighter fiscal rhetoric, with President Prabowo's recent economy meeting flagging inflation control and budget savings.

Malaysia's BNM decision remains the week's key regional event, with the ringgit already trading on normalisation expectations. Singapore and Thailand have no top-tier data scheduled, leaving FX and equity flows to drive sentiment.
Page 1

ASEAN Macro Daily(Beta Mode)

November 04, 2026 robomacro.com
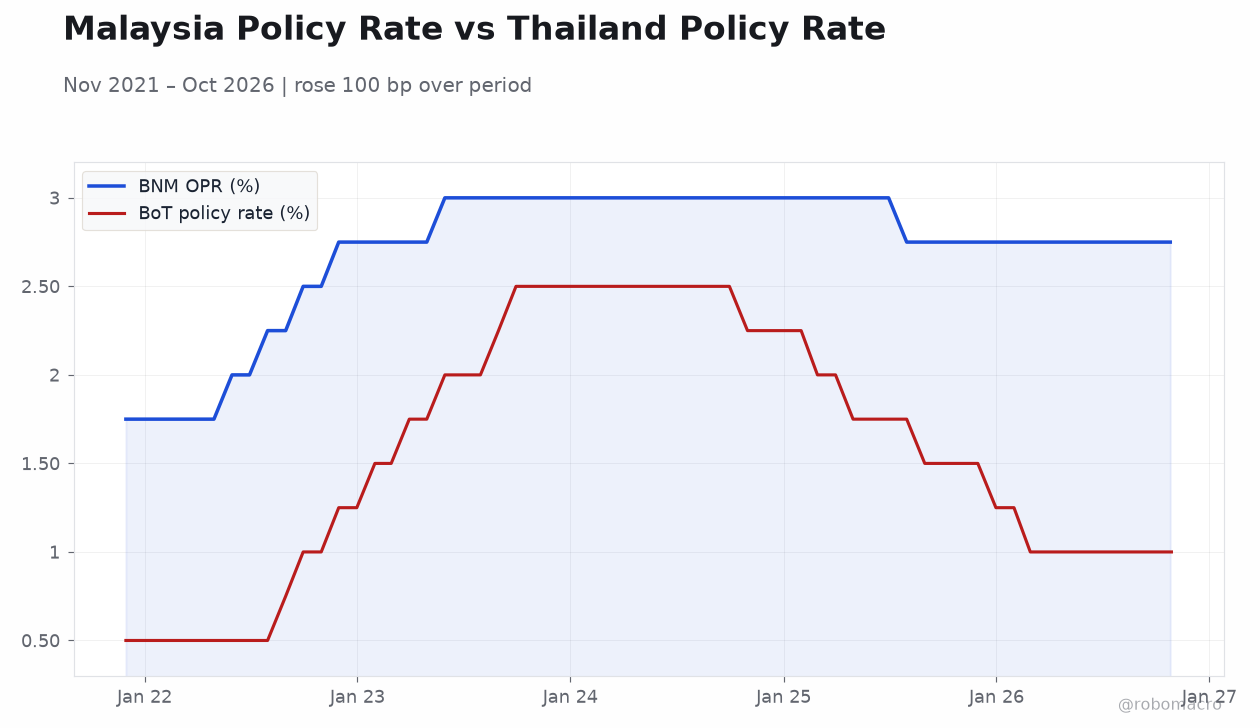
Malaysia Policy Rate vs Thailand Policy Rate Malaysia Policy Rate vs Thailand Policy Rate | Type: macro_line | BNM OPR (%): 2.75 (2026-10-26) | Range: 1.75–3 | Trend(4pt): 1.75,2.75,3,2.75 | BoT policy rate (%): 1 (2026-10-28) | Range: 0.5–2.5 | Trend(5pt): 0.5,1.5,2.5,1.5,1
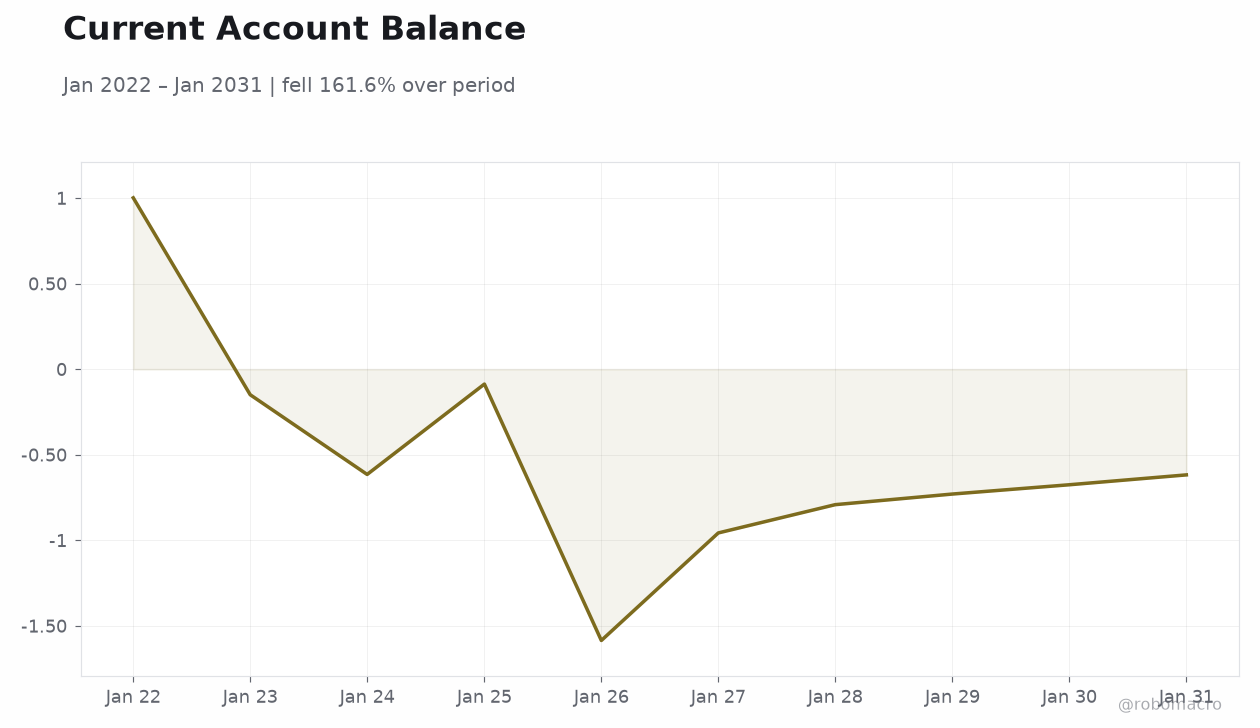
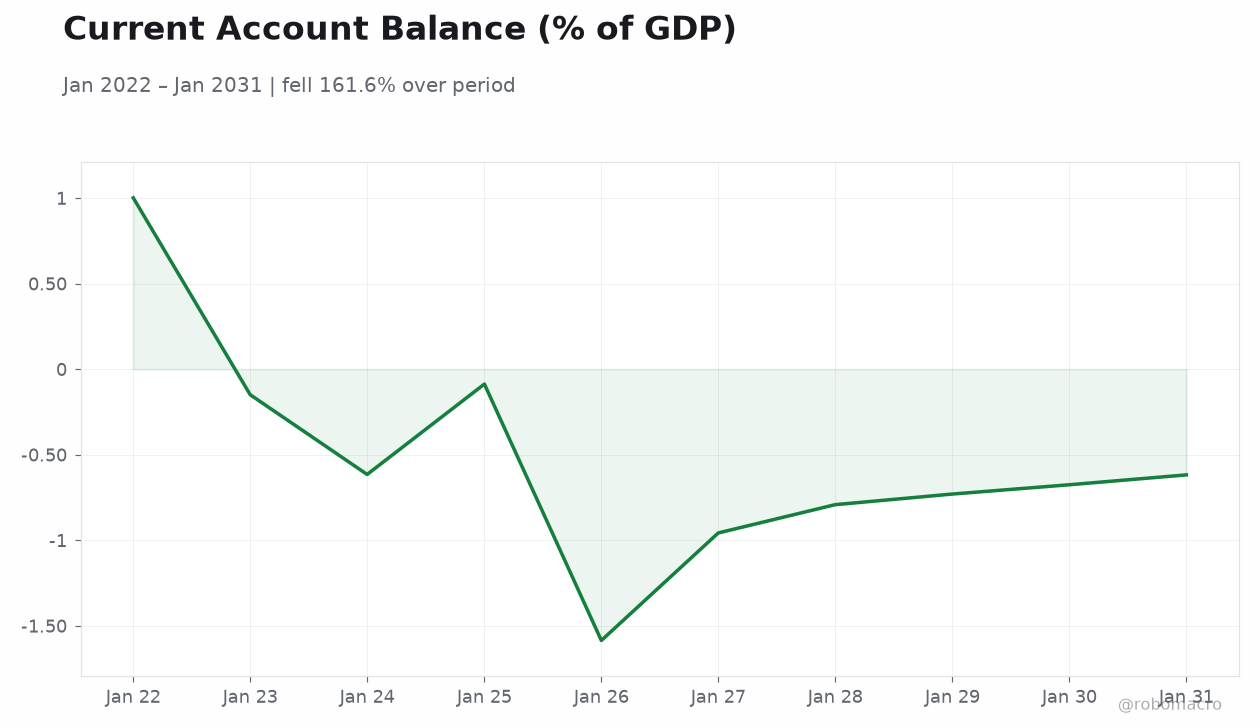
Current Account Balance (% of GDP) Current Account Balance (% of GDP) | Type: macro_line | Current Account Balance (% of GDP): -0.6173 (2031-01-01) | Range: -1.585–1.002 | Trend(6pt): 1.002,-0.6147,-1.585,-0.7914,-0.675,-0.6173
Current Account Balance Current Account Balance | Type: macro_line | Current Account Balance: -0.6173 (2031-01-01) | Range: -1.585–1.002 | Trend(6pt): 1.002,-0.6147,-1.585,-0.7914,-0.675,-0.6173
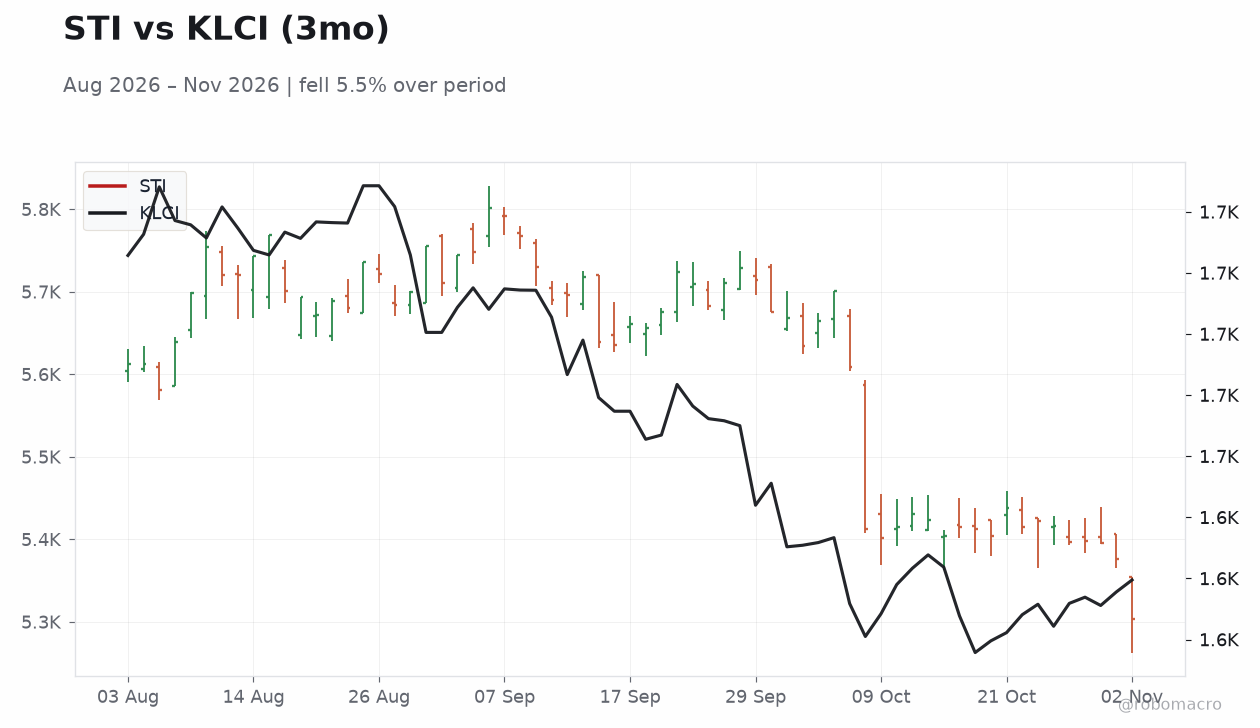
STI vs KLCI (3mo) STI vs KLCI (3mo) | Type: market_hloc | STI: 5304 (2026-11-02) | Range: 5304–5802 | Trend(5pt): 5612,5722,5661,5402,5304 | KLCI: 1620 (2026-11-02) | Range: 1596–1749 | Trend(6pt): 1726,1736,1675,1601,1611,1620

Other Economic Notes

Thailand's decision to raise excise tax on fully imported BEVs to 35% from 10% signals a pivot toward protecting domestic assembly and attracting battery investment — GAC's first overseas battery pack plant opening in Thailand underscores the supply-chain localisation theme. Malaysia continues to attract meaningful FDI, with RM59.5bn (US$14.6bn) in potential investments generated through overseas missions, supporting the ringgit's medium-term outlook; HSBC sees the currency at 4.10-4.20/USD in 2027. Indonesia's fiscal trajectory remains a swing factor: Prabowo's directive on APBN savings and inflation control suggests consolidation pressure, which markets are reading alongside MSCI's governance warning.

The Philippines' remittance-dependent model is under debate as the peso's weakness draws scrutiny of consumption-led growth.

Global Macro News

Global risk appetite remains fragile, with Brent crude at $104.42 (-0.33%) still elevated enough to keep imported inflation risks alive for ASEAN energy importers like Thailand and the Philippines. Gold at $3,940.20 (-0.74%) and Bitcoin at $77,730 (+1.37%) suggest mixed hedging demand rather than a clean risk-off signal. US election uncertainty is explicitly cited by Malaysian market participants as a source of volatility this week, layered on top of the BNM decision.

A firmer dollar backdrop is evident across ASEAN FX, with only the peso resisting the trend. China-US supply chain shifts remain the structural undercurrent for Vietnam, Malaysia, and Thailand's manufacturing ambitions. For ASEAN central banks, the combination of a strong dollar, elevated oil, and uneven domestic demand argues against premature easing.

Sponsored by Arbitrage Search
Page 2

ASEAN Macro Daily(Beta Mode)

November 04, 2026 robomacro.com

Continuation

ASEAN Central Banks Watch

Bank Indonesia holds at 5.75% (set 18 June 2026), with its most recent decision a hold on 21 October and the next meeting on 18 November; BI is explicitly prioritising rupiah stability, and with USD/IDR above 18,100, intervention risk is elevated. Bank Negara Malaysia's policy rate stands at 2.75% ahead of its decision this week, with the ringgit firming on "normalisation" expectations — a signal markets expect a hawkish tilt or hold rather than easing. The Bank of Thailand holds at 1.00% (set 25 February 2026), most recently holding on 28 October, with the next meeting 23 December; Thai CPI at 2.53% keeps it within tolerance, limiting urgency.

The BSP faces a peso near 63.49/USD and October CPI due Wednesday, with the 7.2% prior print framing a difficult balancing act. MAS, which uses a NEER exchange-rate band rather than interest rates, is watching SGD at 1.28/USD; the currency's modest softening is consistent with a stable policy stance. The SBV remains the region's growth-oriented outlier, managing the dong with an eye on Vietnam's export competitiveness.

Divergence is clear: BI defensive, BNM cautious, BoT accommodative, BSP data-dependent, MAS neutral, SBV growth-first.

Sponsored by Arbitrage Search
Page 3