ASEAN Macro Daily(Beta Mode)
Rupiah Record Low Spurs BI Intervention
Market Snapshot
| Asset | Level | Change |
|---|---|---|
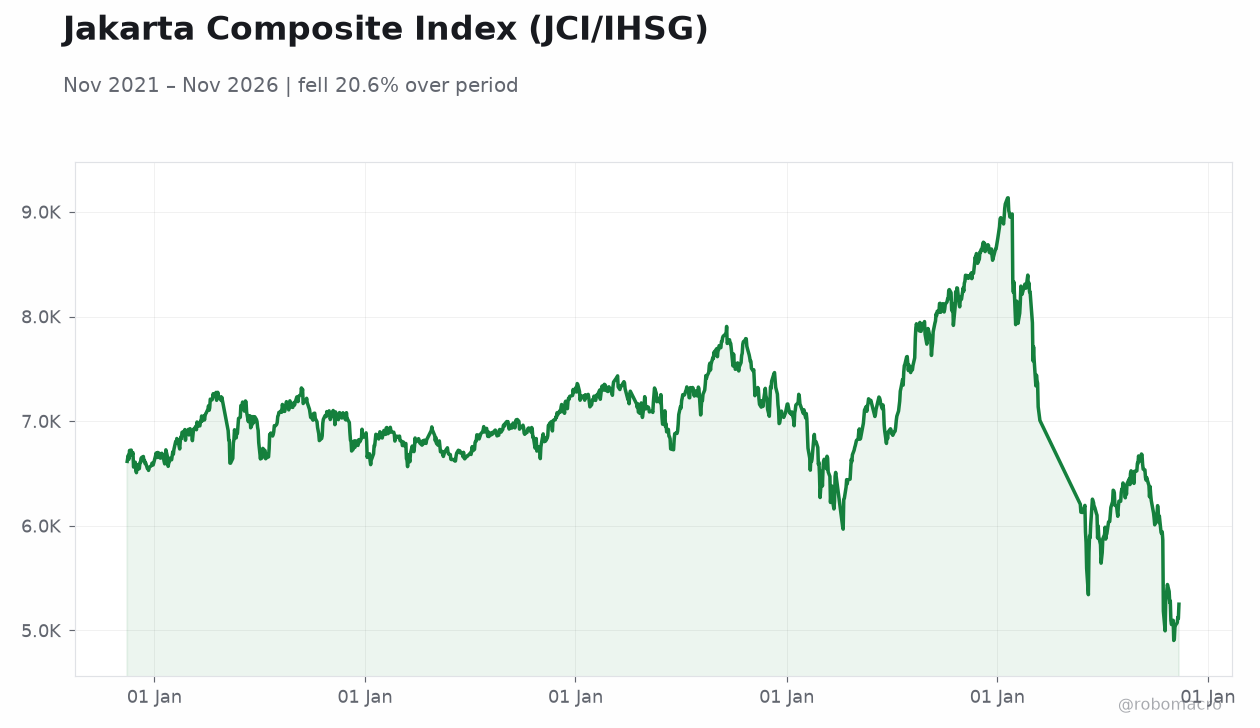
| JCI | 5,115.04 | -0.21% |
| KLCI | 1,595.19 | -0.55% |
| STI | 5,289.66 | +0.59% |
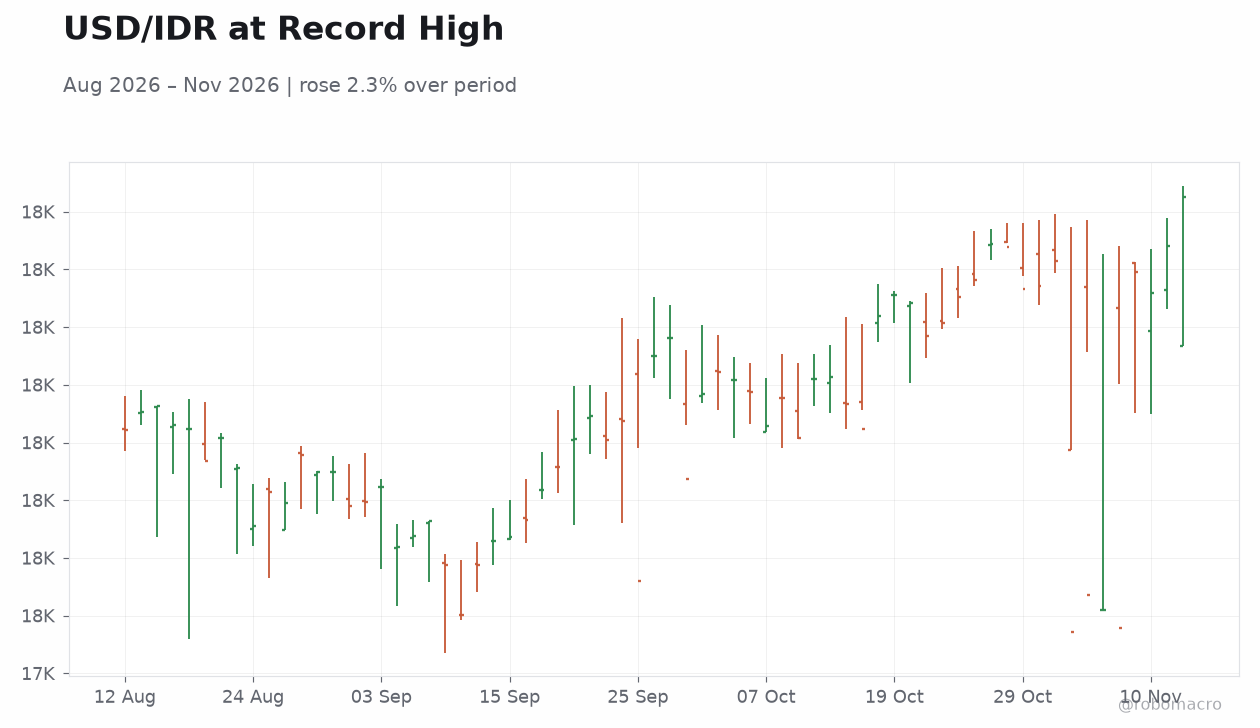
| USD/IDR | 18,225.00 | +0.47% |
| USD/THB | 33.90 | +0.93% |
| USD/MYR | 4.08 | +0.56% |
| USD/PHP | 63.76 | +1.30% |
| USD/SGD | 1.29 | +0.31% |
| Brent Crude | 95.77 | +3.24% |
| Gold | 3,881.70 | -2.97% |
| Bitcoin | 71,359.93 | -3.52% |
| Indonesia 10Y Govt Yield | - | - |
| Thailand 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
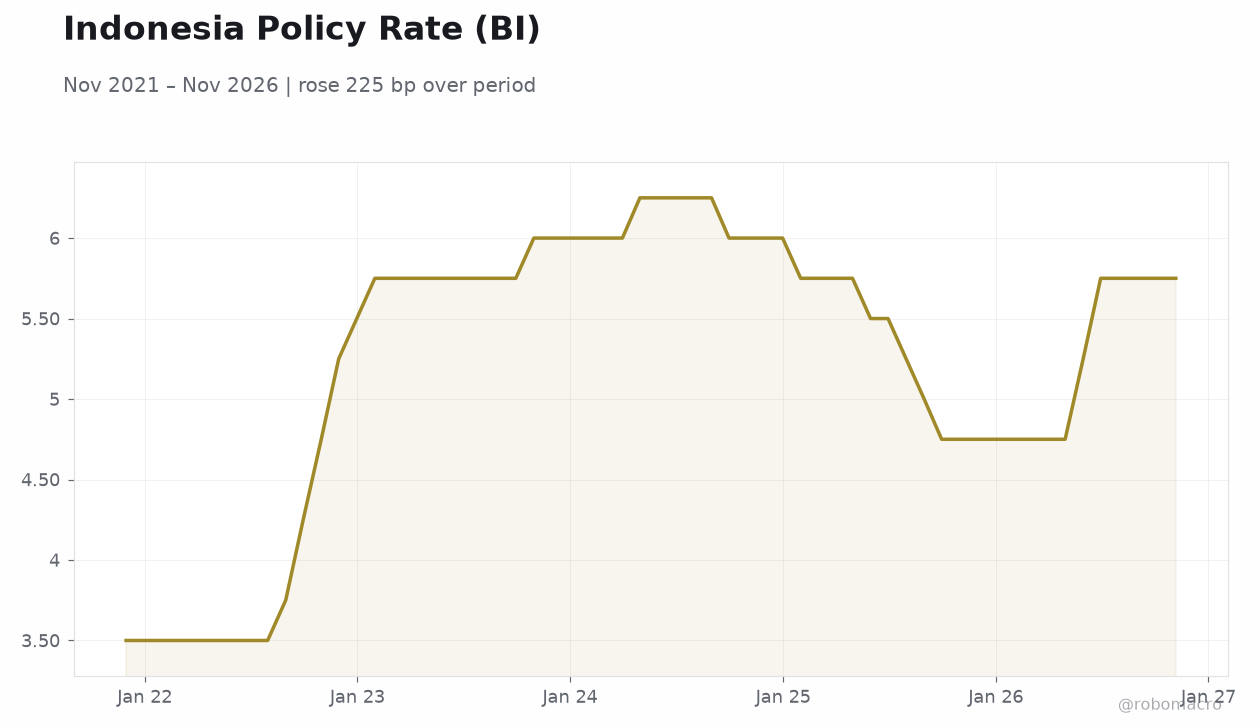 Indonesia Policy Rate (BI) | Type: macro_line | BI policy rate (%): 5.75 (2026-11-06) | Range: 3.5–6.25 | Trend(5pt): 3.5,5.75,6.25,5,5.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Indonesian rupiah slides to a record low past 18,241/USD, forcing Bank Indonesia to intervene as MSCI index concerns and domestic political uncertainty compound dollar pressure.
- Regional FX broadly weaker against a surging dollar; PHP leads losses at +1.30%, THB +0.93%, MYR +0.56%, while Singapore's STI is the lone equity bright spot at +0.59%.
- Brent crude jumps 3.24% to $95.77 while gold and Bitcoin retreat sharply, signalling risk-off rotation into energy and the dollar.
Yesterday's Recap
The Indonesian rupiah dominated ASEAN markets yesterday, sliding to a record low of 18,241/USD before Bank Indonesia confirmed currency interventions to stabilise the pair; the rupiah closed around 18,225, down 0.47% on the day and now Asia's worst-performing currency this year. The selloff reflects a confluence of a broad dollar rally, mounting MSCI index-inclusion concerns, and domestic political turbulence, with Jakarta officials pushing back against comparisons to the 1998 crisis. Indonesian equities tracked the stress, with the JCI easing 0.21% to 5,115.04, though a resilient trade surplus continues to underpin the external account into 2026.
Elsewhere in the region, the Philippine peso posted the sharpest move among ASEAN currencies, with USD/PHP climbing 1.30% to 63.76. Malaysia's KLCI fell 0.55% to 1,595.19 and the ringgit edged weaker to 4.08 despite optimism over an investment-cycle-driven recovery in 2027. Singapore was the outlier, with the STI gaining 0.59% to 5,289.66 even as USD/SGD firmed 0.31% to 1.29.
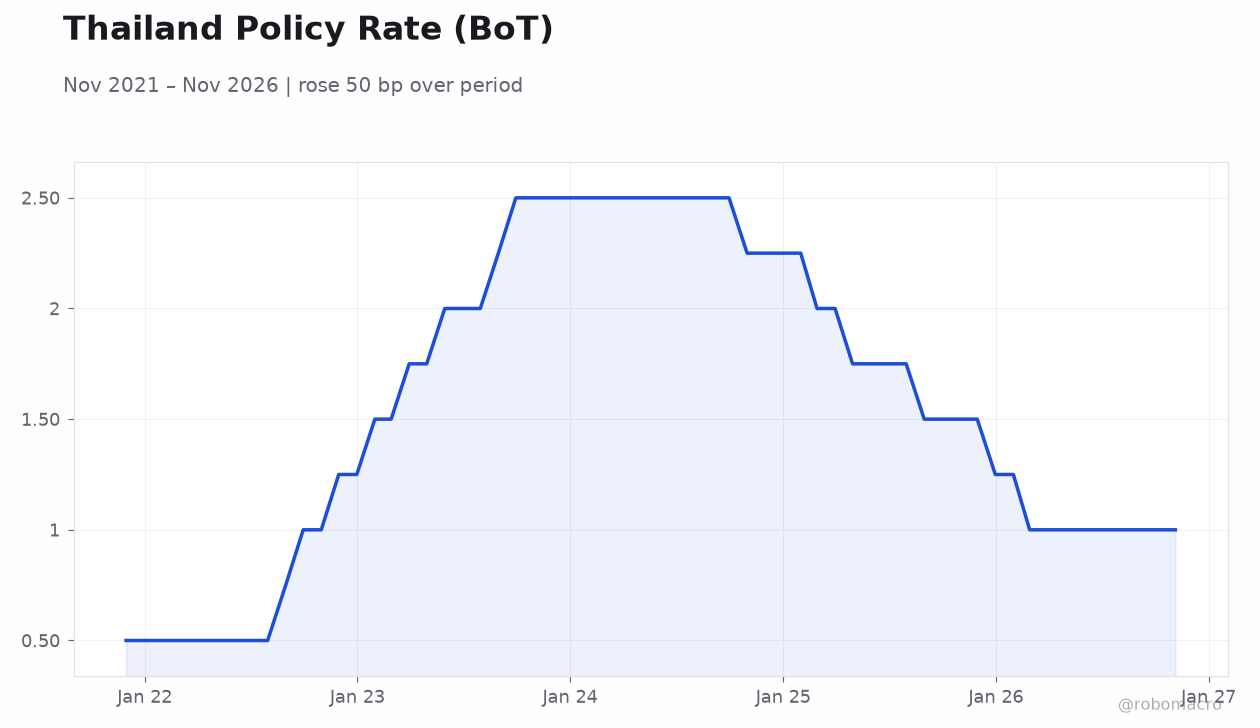
Thai markets saw the baht weaken 0.93% to 33.90 amid continued debate over prolonged low rates.
The Day Ahead
The ASEAN calendar is light today, with no scheduled tier-one data releases across the six economies, leaving markets to digest the rupiah's record low and the broader dollar move. Attention turns to Bank Indonesia's next policy meeting on 18 November, which will be the first test of how the central bank balances FX defence against its 5.75% policy rate. Thailand's next BoT decision is not due until 23 December, so near-term baht direction will be driven by external flows and the central bank's financial-stability commentary.
Malaysia and the Philippines have no scheduled prints, keeping focus on ringgit and peso spillover from US midterm developments and dollar momentum. Singapore's MAS will continue to manage the SGD NEER band passively, with no policy event on the immediate horizon.
Other Economic Notes
Indonesia's trade surplus remains a key buffer for the rupiah, with export competitiveness supporting the external account into 2026 even as portfolio outflows pressure the currency. The MSCI downgrade concerns are a structural risk — any index reclassification would trigger passive outflows and compound the rupiah's vulnerability. ↓ p.2