ASEAN Macro Daily(Beta Mode)
BI Hikes to 6% to Defend Rupiah
Market Snapshot
| Asset | Level | Change |
|---|---|---|
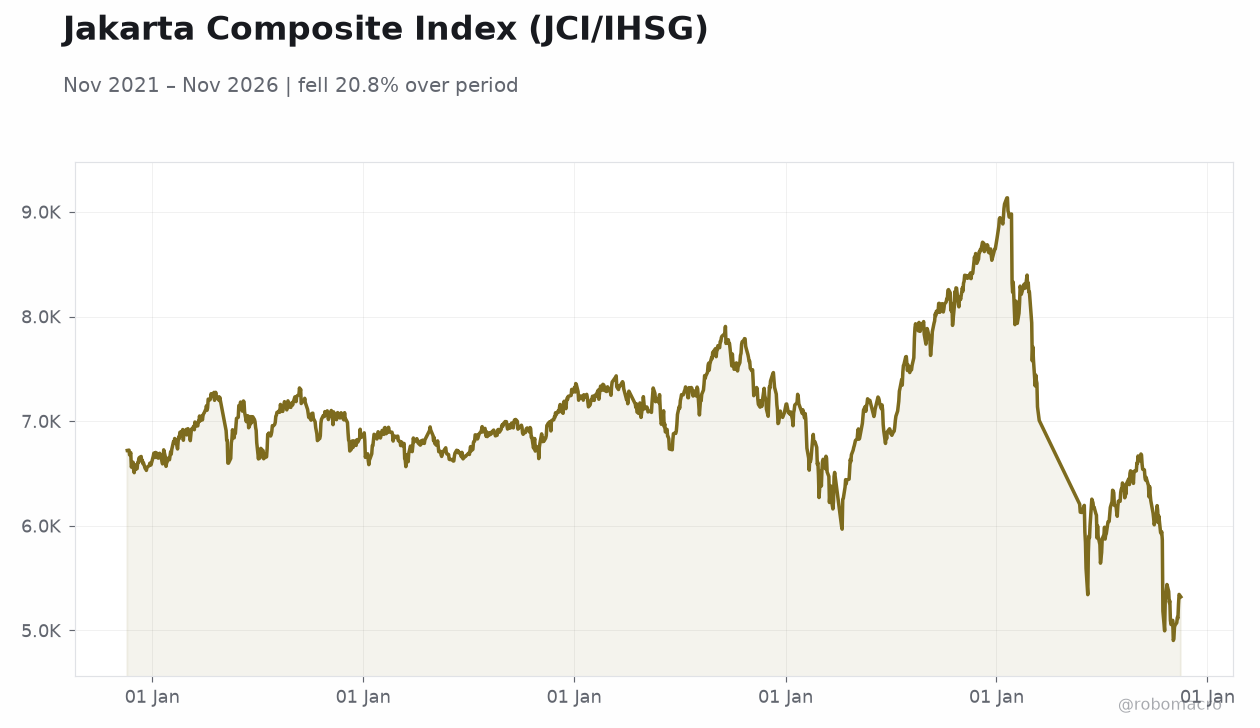
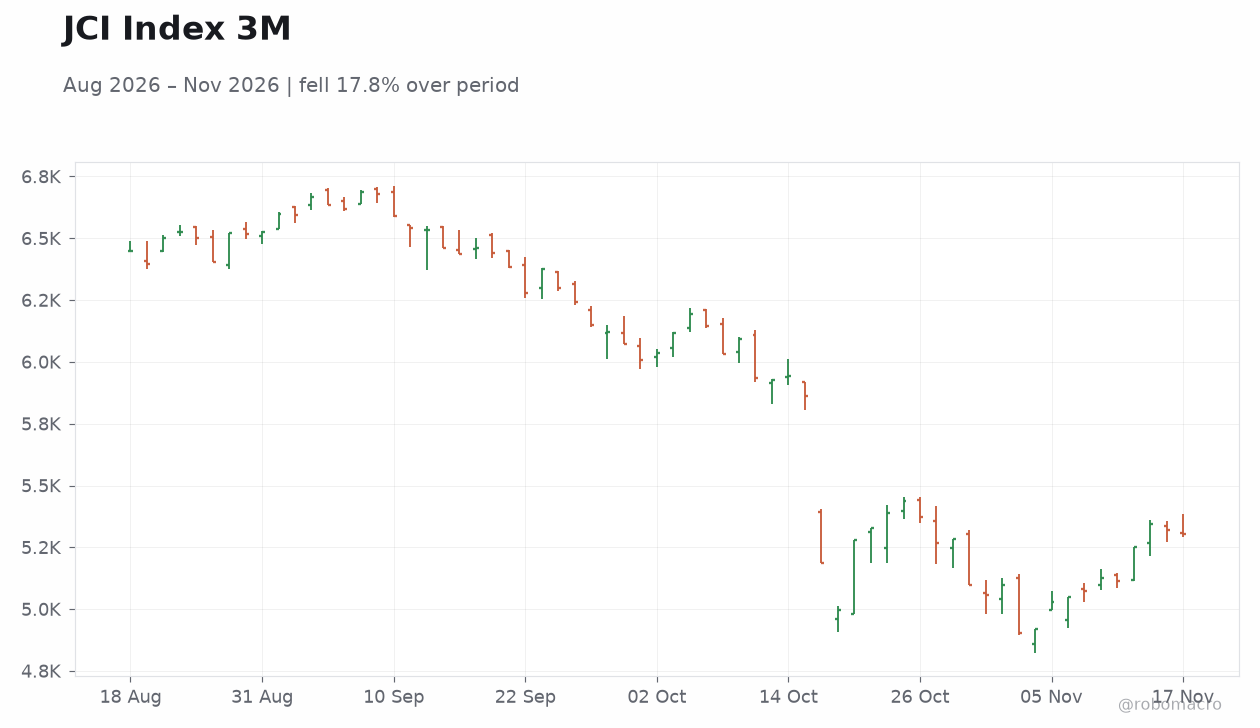
| JCI | 5,304.75 | -0.30% |
| KLCI | 1,575.15 | -0.81% |
| STI | 5,109.13 | -1.43% |
| USD/IDR | 18,158.00 | +3.20% |
| USD/THB | 33.94 | +0.18% |
| USD/MYR | 4.11 | +0.51% |
| USD/PHP | 63.64 | -0.35% |
| USD/SGD | 1.29 | +0.03% |
| Brent Crude | 88.78 | -4.68% |
| Gold | 3,738.30 | -3.26% |
| Bitcoin | 62,781.25 | -3.26% |
| Indonesia 10Y Govt Yield | - | - |
| Thailand 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Central Bank Interest Rate Decision | 5.75 | 5.75 | 6 |
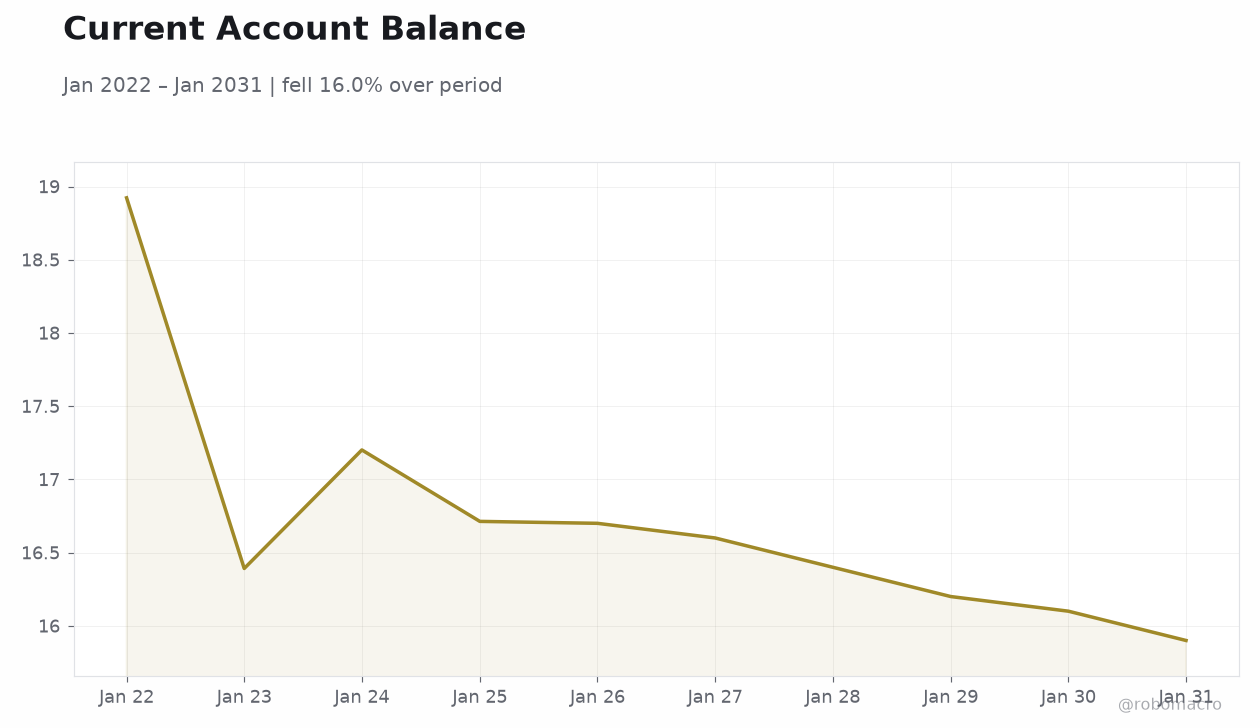 Current Account Balance | Type: macro_line | Current Account Balance: 15.9 (2031-01-01) | Range: 15.9–18.92 | Trend(6pt): 18.92,17.2,16.7,16.4,16.1,15.9
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0.10 | - | 23:00 |
| Inflation Rate Year-over-Year | 1.80 | 2 | 23:00 |
- Bank Indonesia surprises markets with 25bp rate hike to 6.00%
- Rupiah slides 3.2% versus USD despite aggressive tightening
- Malaysian October inflation prints due later today
Yesterday's Recap
Bank Indonesia raised its policy rate 25bp to 6.00%, exceeding consensus expectations of a hold at 5.75%. The move came as the rupiah approached multi-year lows, prompting the central bank to resume tightening after the June hike. Equity markets across ASEAN closed lower, with the JCI falling 0.30%, the KLCI declining 0.81%, and the STI dropping 1.43%.
The USD/IDR pair jumped 3.20% to 18,158, while the USD/MYR rose 0.51% and the USD/THB gained 0.18%. Brent crude fell 4.68% and gold declined 3.26%, adding to regional risk-off sentiment. Thailand’s Q3 GDP growth of 2.9% and Malaysia’s 5.5% expansion provided some offset but failed to lift broader sentiment.
The Day Ahead
Malaysia will release October inflation figures at 23:00 ET, with the year-over-year rate expected at 2.0% after 1.8% in September. Month-over-month price changes will also be published. No other high-impact ASEAN data releases are scheduled.
Market participants will watch the prints for clues on Bank Negara Malaysia’s policy path ahead of its next meeting. Regional FX desks remain focused on follow-through from the Indonesian rate decision and any further rupiah intervention signals.
Other Economic Notes
Malaysia’s diversified economy continues to support steady growth, with the central bank noting reduced reliance on the AI sector amid global chip curbs. Thailand’s Q3 expansion ranked fifth among major ASEAN peers, highlighting uneven recovery momentum across the region. Indonesia’s large external debt stock of $458.9 billion faces added pressure from the weaker rupiah, raising refinancing risks for corporates.
Supply-chain shifts from China continue to favor Vietnam and Malaysia as manufacturing alternatives, though near-term capital flow volatility remains elevated.
Global Macro News
US Treasury yields rose amid expectations of sustained policy rates, weighing on emerging-market currencies including the rupiah. President Trump’s announcement that Thailand will eliminate tariffs on US exports under a new deal could support Thai trade balances over time. MAS and the Bundesbank advanced wholesale CBDC testing for euro-SGD settlement, underscoring Singapore’s role in cross-border innovation.
↓ p.2