Andeans Macro Daily(Beta Mode)
Brent Surges as Andean Currencies Diverge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
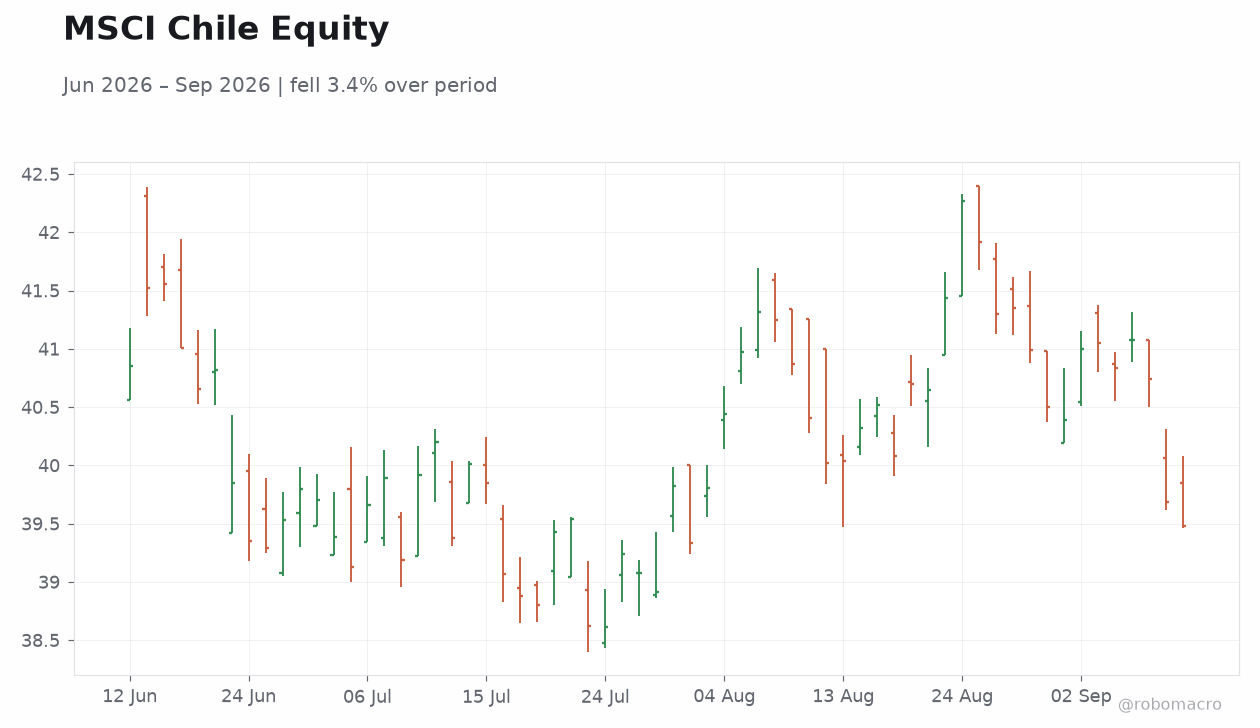
| MSCI Chile | 39.48 | -0.53% |
| MSCI Peru | 90.72 | -0.07% |
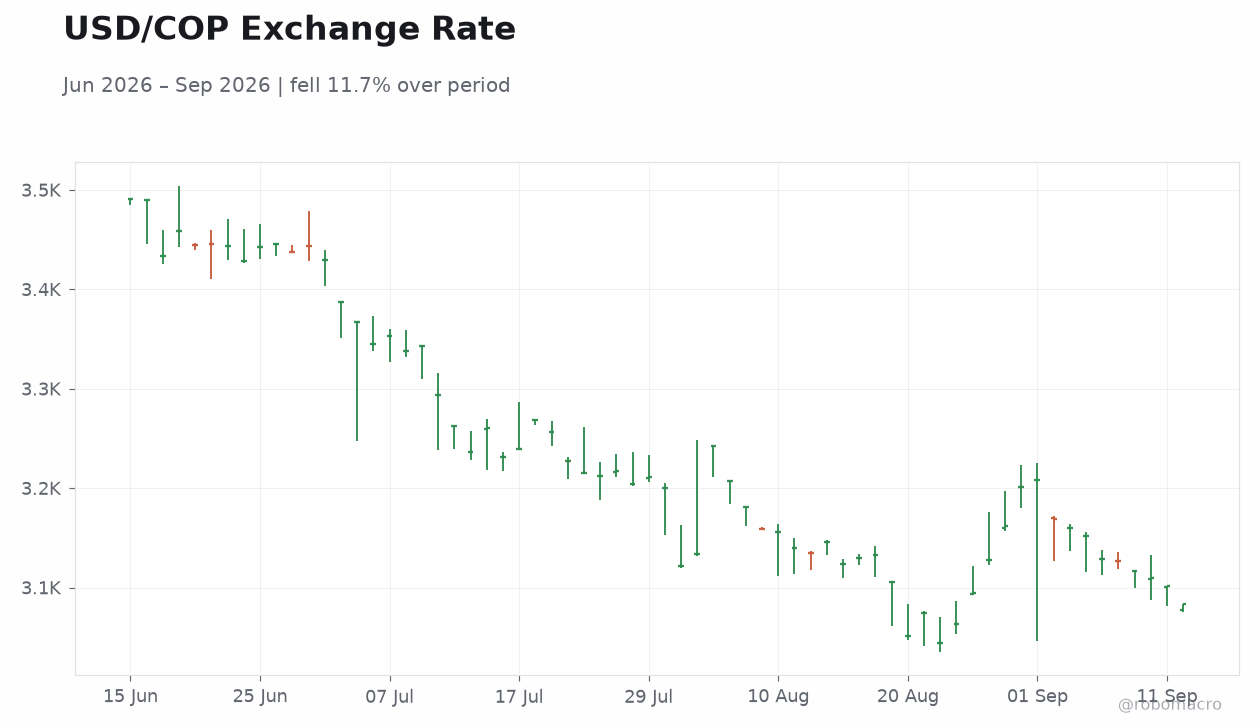
| USD/COP | 3,083.86 | -0.57% |
| USD/CLP | 947.15 | +0.73% |
| USD/PEN | 3.36 | +3.38% |
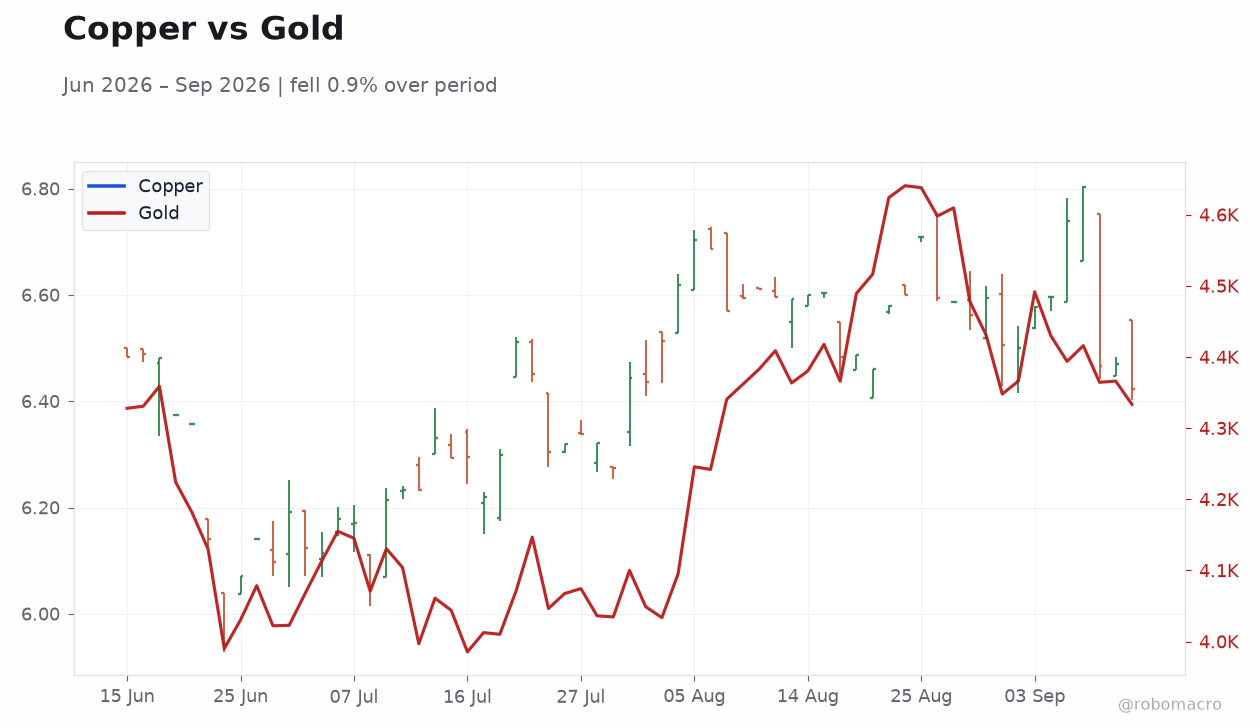
| Copper | 6.42 | -0.75% |
| Gold | 4,334.60 | -0.72% |
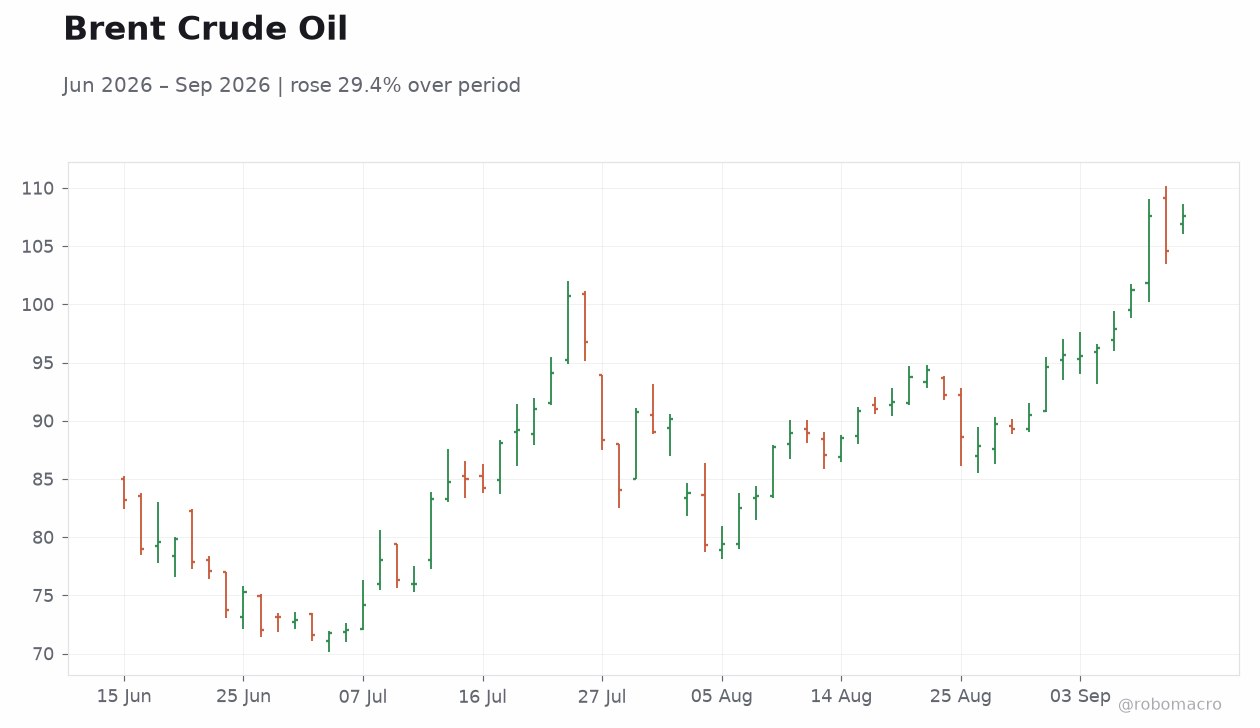
| Brent Crude | 107.54 | +2.80% |
| Bitcoin | 77,772.65 | +1.22% |
| Colombia 10Y Govt Yield | - | - |
| Chile Short-term Rate | 4.50% | +0.00% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
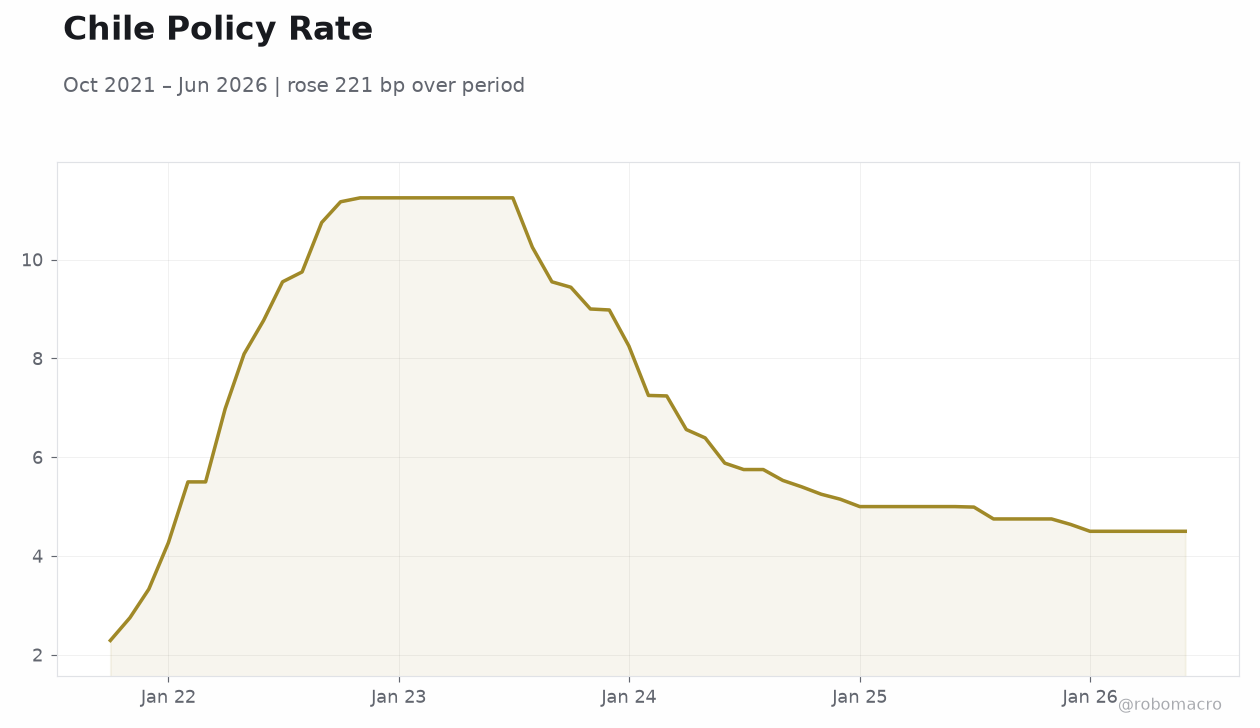 Chile Policy Rate | Type: macro_line | Short-term rate %: 4.5 (2026-06-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MSCI Chile fell 0.53% while Colombia held flat and Peru eased 0.07% amid commodity swings.
- USD/COP declined 0.57% as COP strengthened, but USD/CLP rose 0.73% and USD/PEN jumped 3.38%.
- Brent crude climbed 2.80% to 107.54, supporting Colombia’s fiscal outlook, while copper slipped 0.75%.
Yesterday's Recap
Equity benchmarks across the Andean bloc closed mixed to lower on September 13 with no economic data releases in Colombia, Chile or Peru. MSCI Chile declined 0.53% to 39.48 as copper prices fell 0.75% to 6.42, pressuring mining revenues that underpin fiscal balances in both Chile and Peru. MSCI Peru slipped 0.07% to 90.72 while MSCI Colombia remained unchanged at 9.02.
Currency markets showed sharp divergence: USD/COP dropped 0.57% to 3,083.86, delivering modest relief to Colombian importers, whereas USD/CLP rose 0.73% to 947.15 and USD/PEN surged 3.38% to 3.36, eroding local purchasing power. Brent crude’s 2.80% advance to 107.54 bolstered Colombia’s oil-linked current account and royalty income, partially offsetting the peso’s appreciation in local-currency terms. Gold’s 0.72% decline to 4,334.60 had limited immediate fiscal impact but reduced export earnings for Peruvian and Colombian gold producers.
Chile’s short-term policy rate stayed at 4.50% with no central-bank announcements.
The Day Ahead
The calendar remains empty of scheduled releases for Colombia, Chile and Peru through September 15, leaving markets without fresh CPI, GDP or trade-balance prints. Traders will monitor global commodity flows, particularly copper and oil, for signals on export receipts and fiscal balances. Any unexpected central-bank comments from BanRep, BCCh or BCRP could shift rate-path expectations given the region’s divergent inflation trajectories.
Sovereign bond auctions are also absent, keeping focus on secondary-market yields and FX volatility. Regional equity flows may stay light absent domestic catalysts.
Other Economic Notes
Andean economies remain highly sensitive to commodity price swings, with Chile and Peru exposed to copper and Colombia to oil. Lower copper prices compress mining royalties and widen fiscal gaps in the two largest producers, while elevated Brent supports Colombia’s external accounts. Persistent inflation differentials continue to drive divergent monetary-policy paths, with Colombia maintaining a tighter stance than Chile.
FX reserve management and intervention policies remain key buffers against sudden capital-flow reversals. Lithium development in Chile adds a longer-term structural theme that could eventually diversify export revenues beyond copper.