Andeans Macro Daily(Beta Mode)
Andean FX Weakens as USD Strength Persists
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
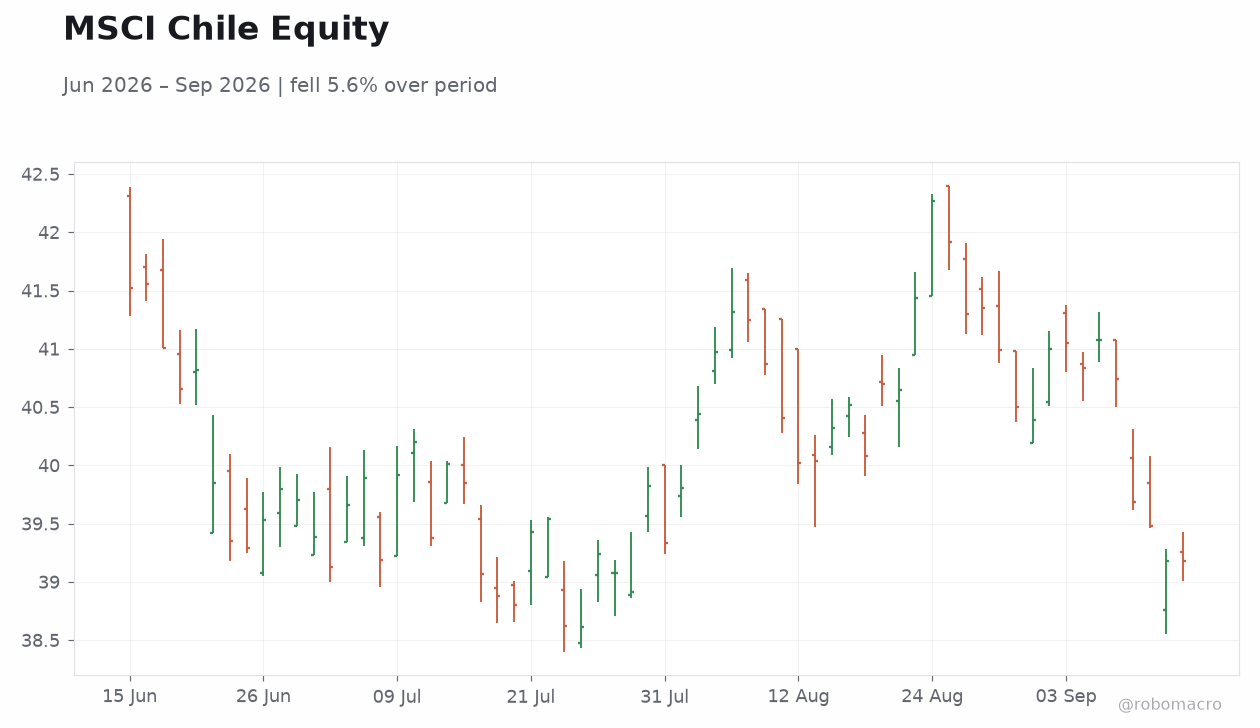
| MSCI Chile | 39.13 | -0.13% |
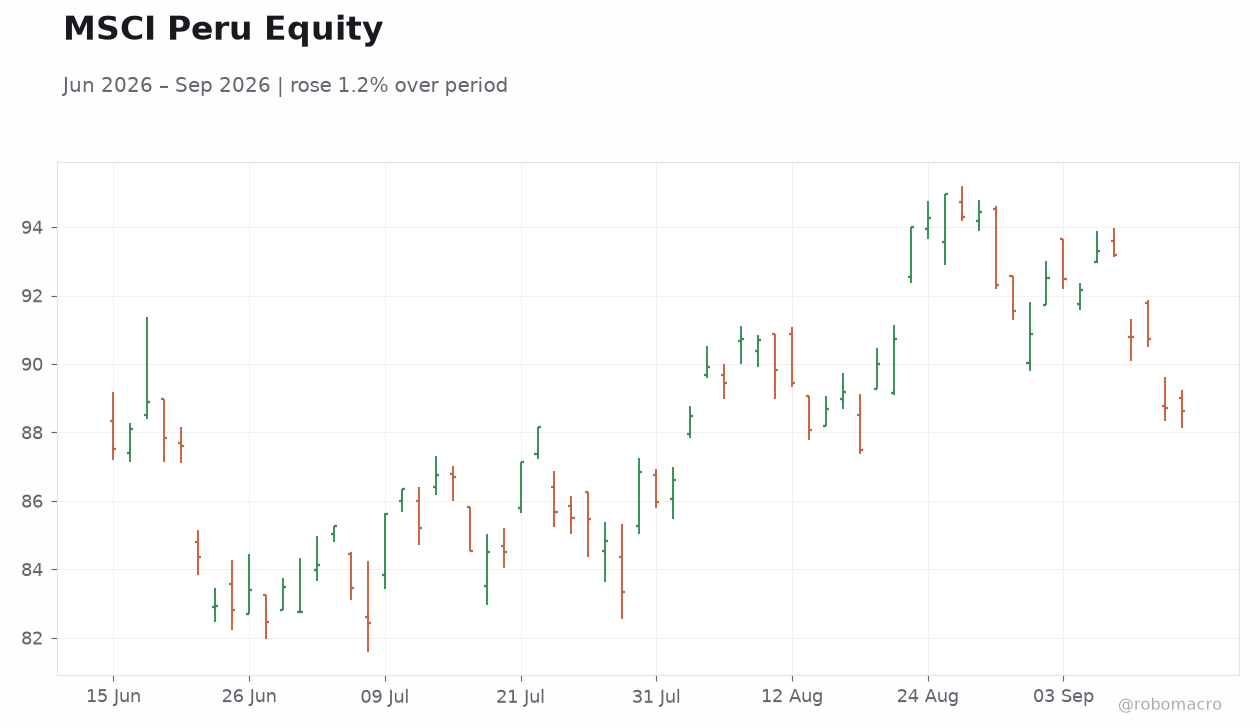
| MSCI Peru | 89.02 | +0.35% |
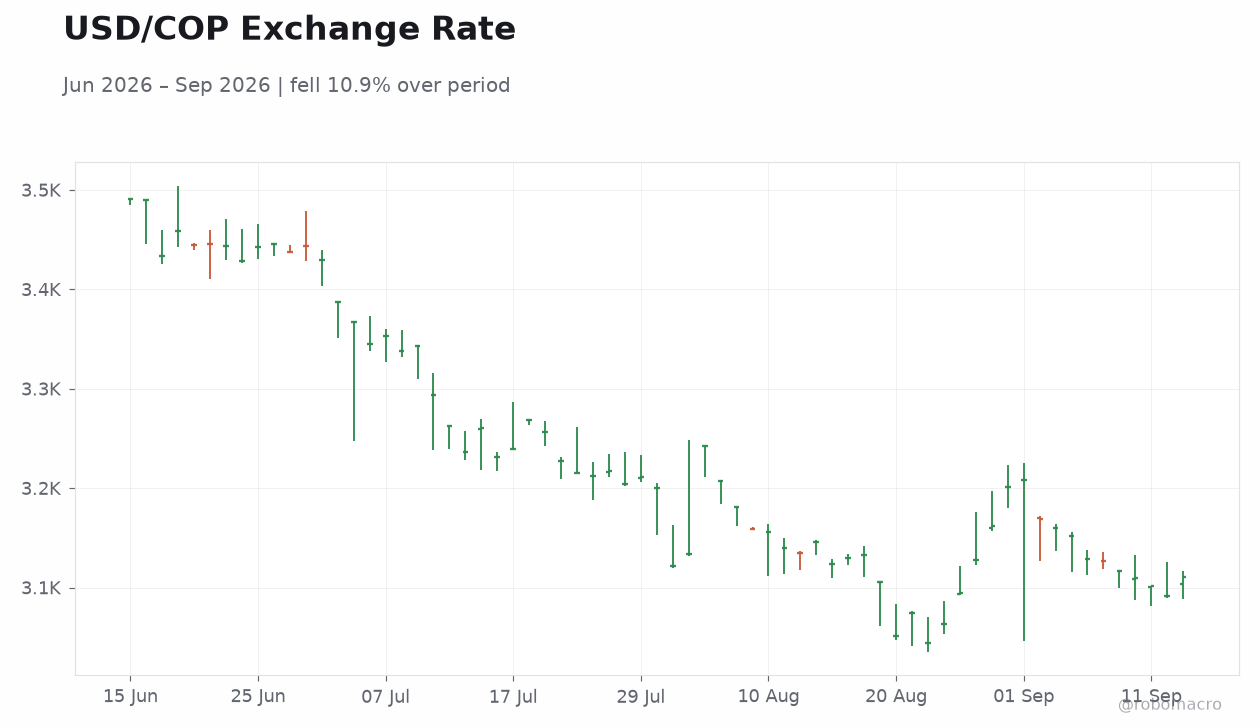
| USD/COP | 3,112.49 | +0.67% |
| USD/CLP | 955.27 | +2.08% |
| USD/PEN | 3.36 | +3.24% |
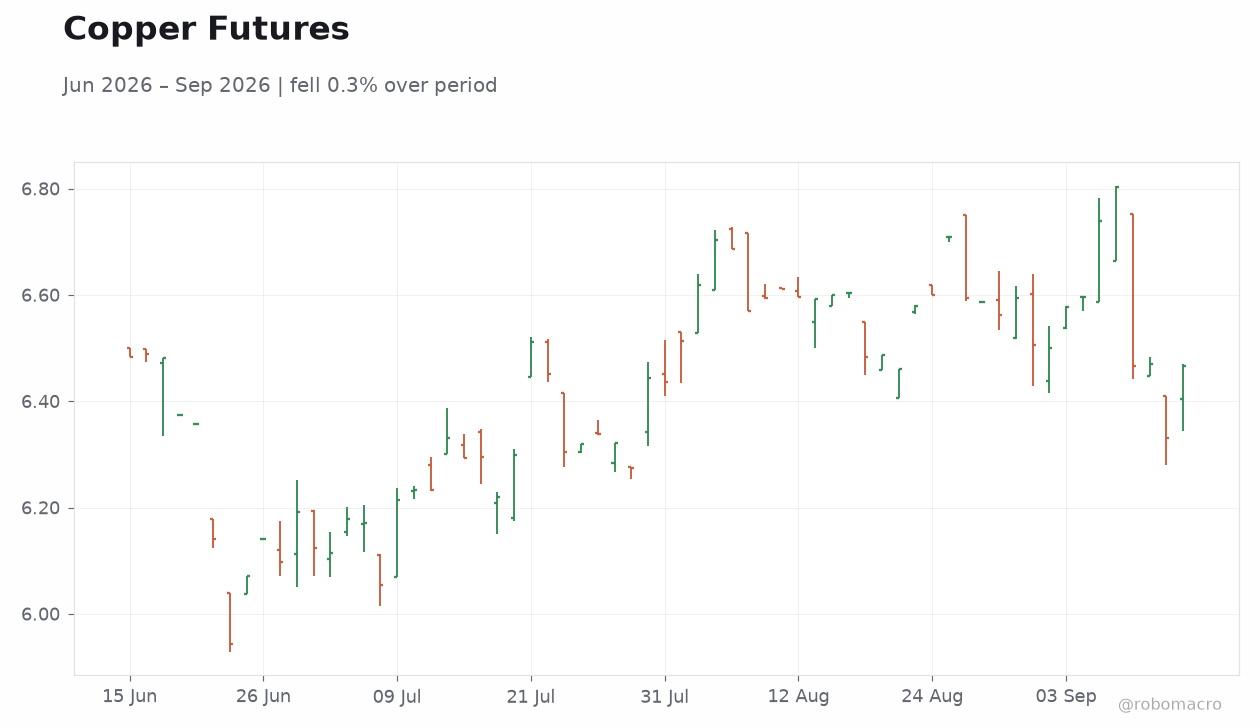
| Copper | 6.46 | +2.12% |
| Gold | 4,347.00 | -0.11% |
| Brent Crude | 108.62 | +2.78% |
| Bitcoin | 75,945.00 | -2.84% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | 6.48% | +10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
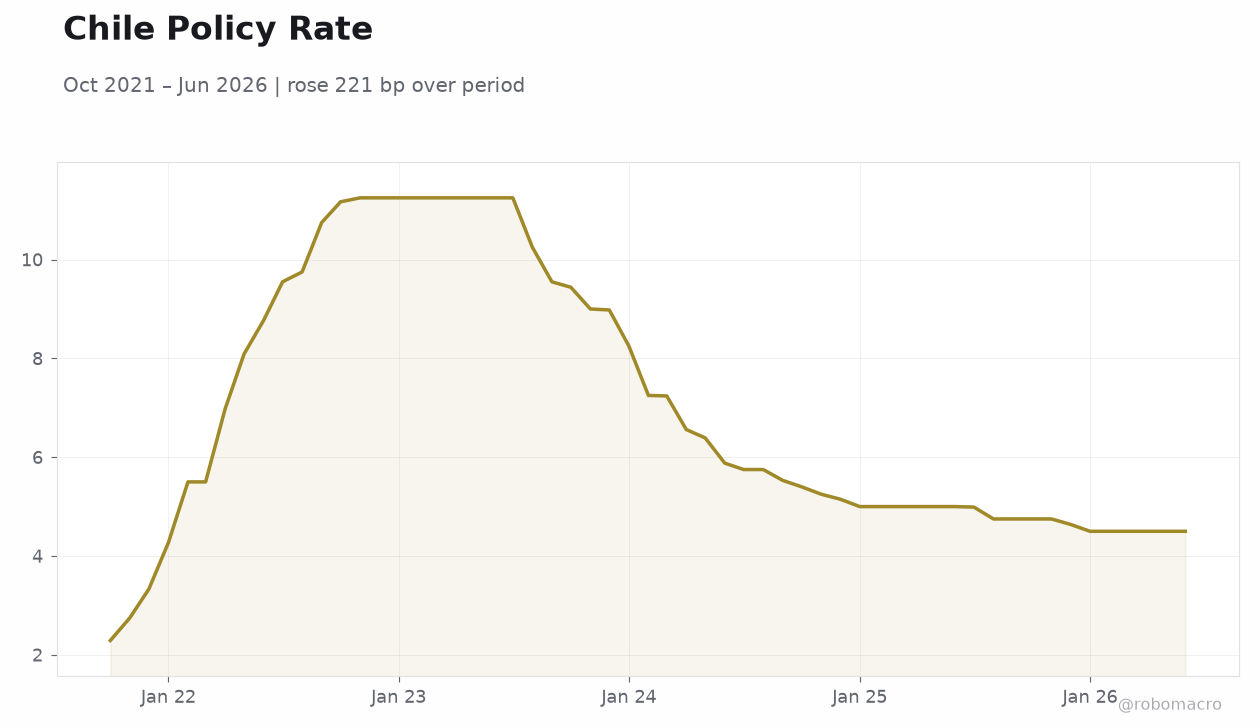 Chile Policy Rate | Type: macro_line | Rate %: 4.5 (2026-06-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- PEN, CLP and COP all weaken sharply against USD amid broad dollar gains
- Copper and Brent rally supports Chile and Peru fiscal positions while Colombia benefits from oil
- MSCI Peru edges higher while Chile slips and Colombia holds flat; Peru 10Y yield rises 10 bp
Yesterday's Recap
Equity markets showed modest divergence across the Andean region on September 14. MSCI Peru rose 0.35 percent to 89.02 while MSCI Chile fell 0.13 percent to 39.13 and MSCI Colombia remained unchanged at 9.02. Currency moves dominated price action as USD/PEN surged 3.24 percent to 3.36, USD/CLP climbed 2.08 percent to 955.27 and USD/COP advanced 0.67 percent to 3,112.49.
Commodity support proved uneven: copper gained 2.12 percent to 6.46 and Brent crude rose 2.78 percent to 108.62, while gold eased 0.11 percent to 4,347.00. Peru’s 10-year government yield increased 10 basis points to 6.48 percent. No macroeconomic releases occurred in Colombia, Chile or Peru, leaving market moves driven by external USD momentum and commodity price shifts.
The absence of domestic data kept attention on external balances and mining revenues for Chile and Peru alongside oil-related flows for Colombia.
The Day Ahead
No economic releases, central-bank meetings or sovereign auctions are scheduled for September 15-16 across Colombia, Chile and Peru. Market participants will therefore monitor external drivers including copper and oil price trajectories that directly affect fiscal and current-account balances. USD strength against PEN, CLP and COP is likely to remain the dominant theme given the lack of offsetting domestic catalysts.
Chile’s mining sector stands to benefit from the copper advance while Colombia’s oil revenues receive support from Brent’s gain. Peru’s external position could see modest relief from higher metal prices despite the sharp PEN depreciation. Attention will also turn to any follow-through on Peru’s diplomatic efforts for US tariff relief, which could influence medium-term trade flows if progress materializes.
Other Economic Notes
Copper’s advance provides direct fiscal relief to Chile and Peru through higher mining royalties and export receipts, though volume data remain absent. Brent’s rise offers Colombia incremental support for oil-linked revenues and external accounts. The broad USD appreciation against all three Andean currencies risks widening current-account pressures and could complicate inflation dynamics in import-dependent sectors.
↓ p.2