Andeans Macro Daily(Beta Mode)
Copper Rally Bolsters Andean Currencies
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
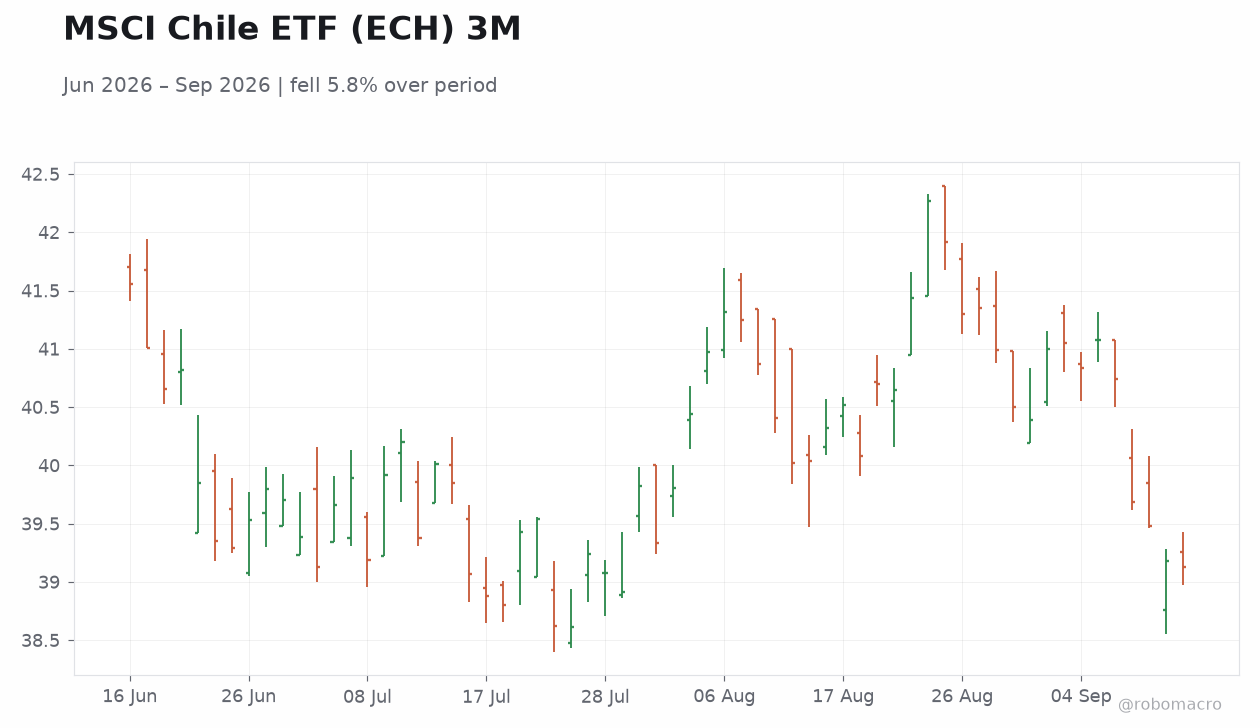
| MSCI Chile | 39.13 | -0.13% |
| MSCI Peru | 88.52 | -0.21% |
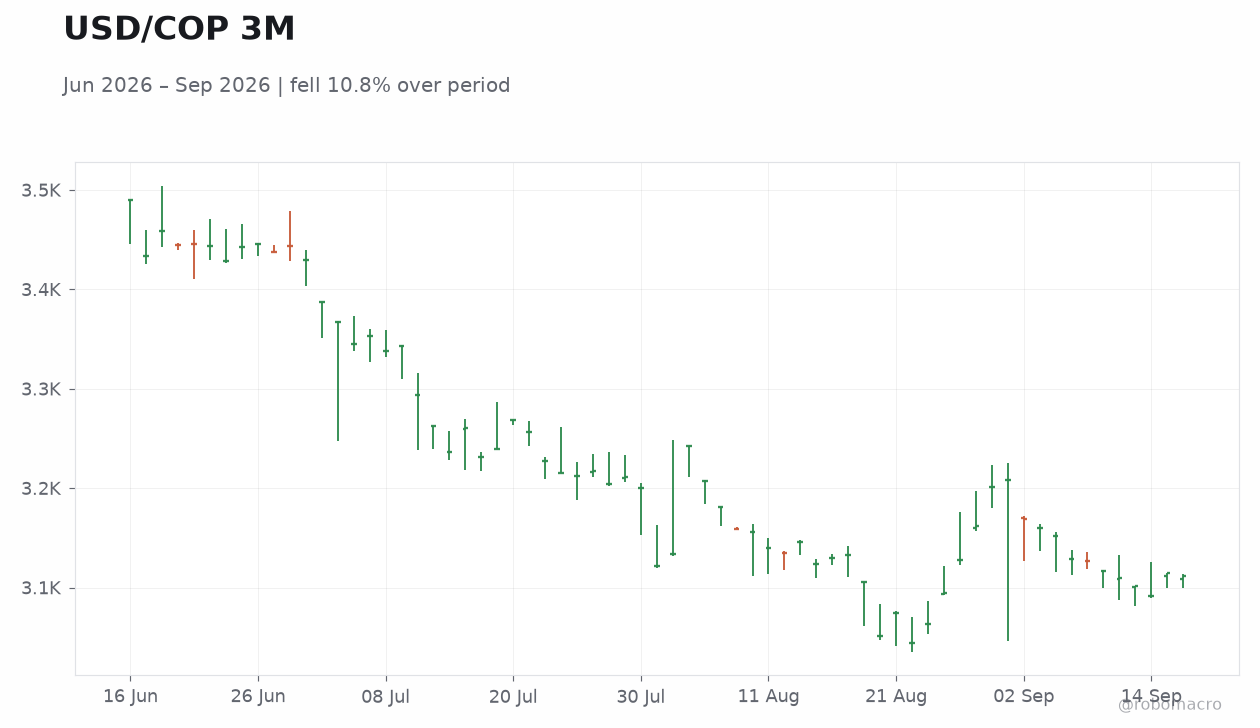
| USD/COP | 3,111.80 | -0.09% |
| USD/CLP | 952.05 | -0.30% |
| USD/PEN | 3.35 | -0.21% |
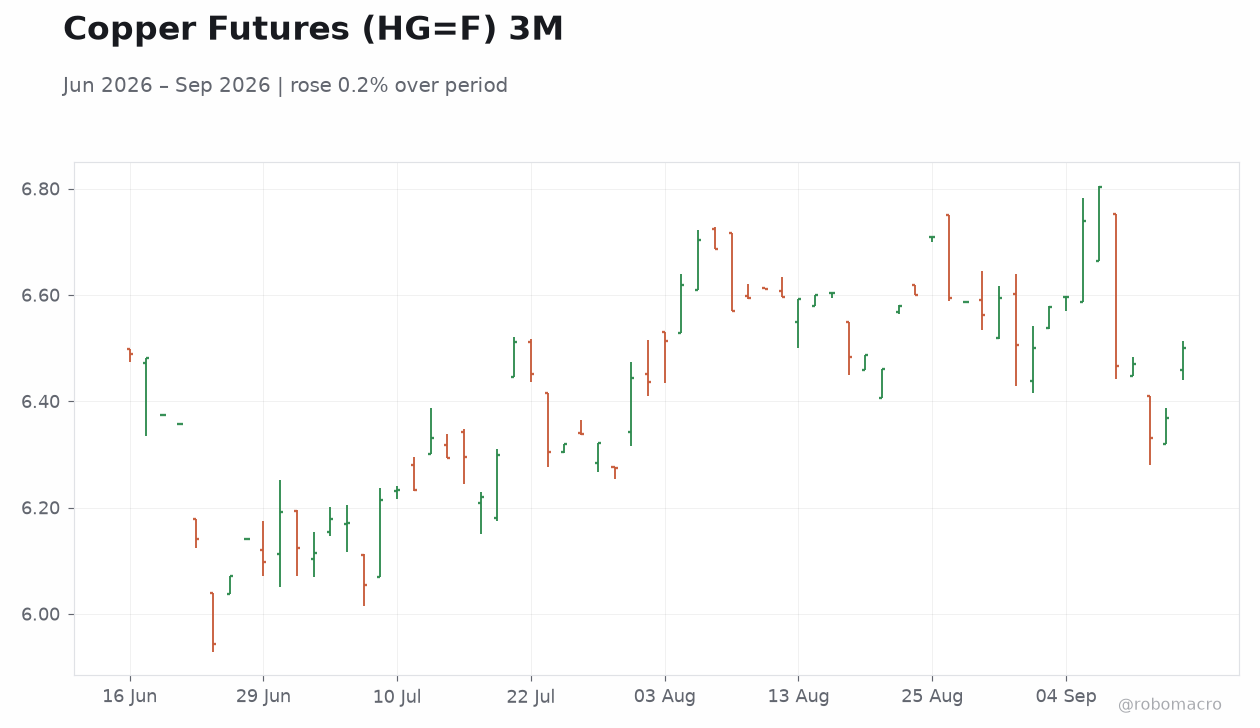
| Copper | 6.50 | +2.10% |
| Gold | 4,391.40 | +1.35% |
| Brent Crude | 107.13 | -1.49% |
| Bitcoin | 75,889.98 | +0.37% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | 6.48% | +10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
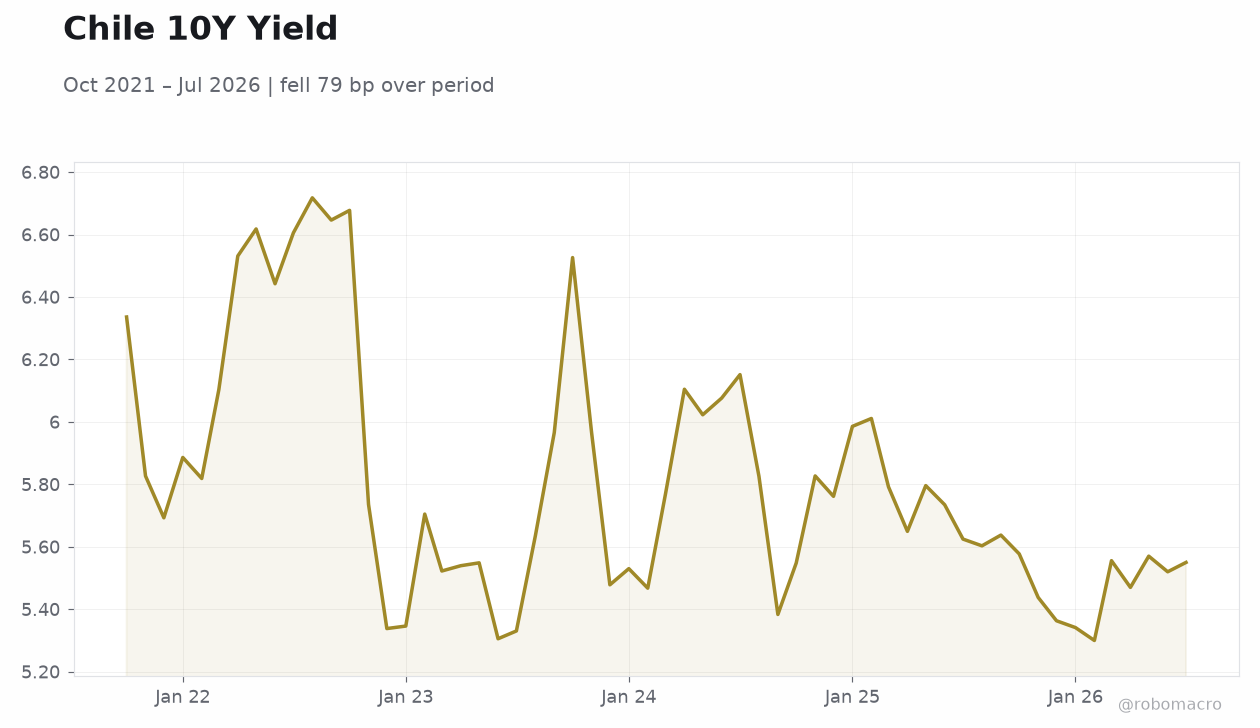 Chile 10Y Yield | Type: macro_line | Yield %: 5.55 (2026-07-01) | Range: 5.3–6.718 | Trend(6pt): 6.336,5.338,5.468,5.649,5.52,5.55
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MSCI Chile and Peru declined modestly while Colombia held flat amid commodity swings
- COP, CLP and PEN all firmed against the USD on higher copper and gold prices
- Peru 10-year yield rose 10 bp to 6.48% as Brent crude fell 1.49%
Yesterday's Recap
Equity indices closed mixed to lower on September 15. MSCI Colombia ended unchanged at 9.02. MSCI Chile fell 0.13% to 39.13 while MSCI Peru declined 0.21% to 88.52.
Currencies strengthened modestly, with USD/COP at 3,111.80 (-0.09%), USD/CLP at 952.05 (-0.30%) and USD/PEN at 3.35 (-0.21%). Copper advanced 2.10% to 6.50, lifting export receipts and fiscal balances in Chile and Peru. Gold rose 1.35% to 4,391.40, benefiting Peru and Colombia, where Aguia Resources reported record August output at its Santa Barbara project.
Brent crude dropped 1.49% to 107.13, weighing on Colombia’s oil-linked revenues. Peru’s 10-year sovereign yield increased 10 bp to 6.48%. No CPI, GDP, trade-balance, industrial-production, employment, retail-sales, or fiscal releases were reported for Colombia, Chile, or Peru on September 15.
The commodity configuration favored Andean FX stability, as evidenced by the modest appreciation of COP, CLP, and PEN.
The Day Ahead
No macroeconomic releases, central-bank meetings or sovereign auctions are scheduled for September 16-17 across Colombia, Chile and Peru. Markets will therefore focus on external commodity prices and any global risk signals. Copper and gold movements remain the primary drivers for CLP and PEN.
Oil price changes will continue to influence COP and Colombia’s external accounts. Regional equity flows may respond to broader EM sentiment rather than domestic data. The absence of local prints leaves commodity volatility as the dominant variable for near-term price action in the three currencies.
Other Economic Notes
Higher copper prices directly improve current-account and fiscal positions in Chile and Peru through mining royalties and tax receipts. Gold strength provides additional support for Colombia and Peru, offsetting softer oil revenues in the former. Commodity volatility underscores the region’s external vulnerability, with limited domestic buffers from absent data prints.
Andean FX resilience yesterday reflected these price gains rather than policy shifts. Record gold grades at the Santa Barbara project add a further positive impulse to Colombian mining receipts and investor sentiment toward the sector.