Andeans Macro Daily(Beta Mode)
Copper Rally Lifts Peru as Sol Weakens Sharply
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 38.95 | -0.46% |
| MSCI Peru | 89.27 | +0.85% |
| USD/COP | 3,122.91 | +0.02% |
| USD/CLP | 953.58 | -0.14% |
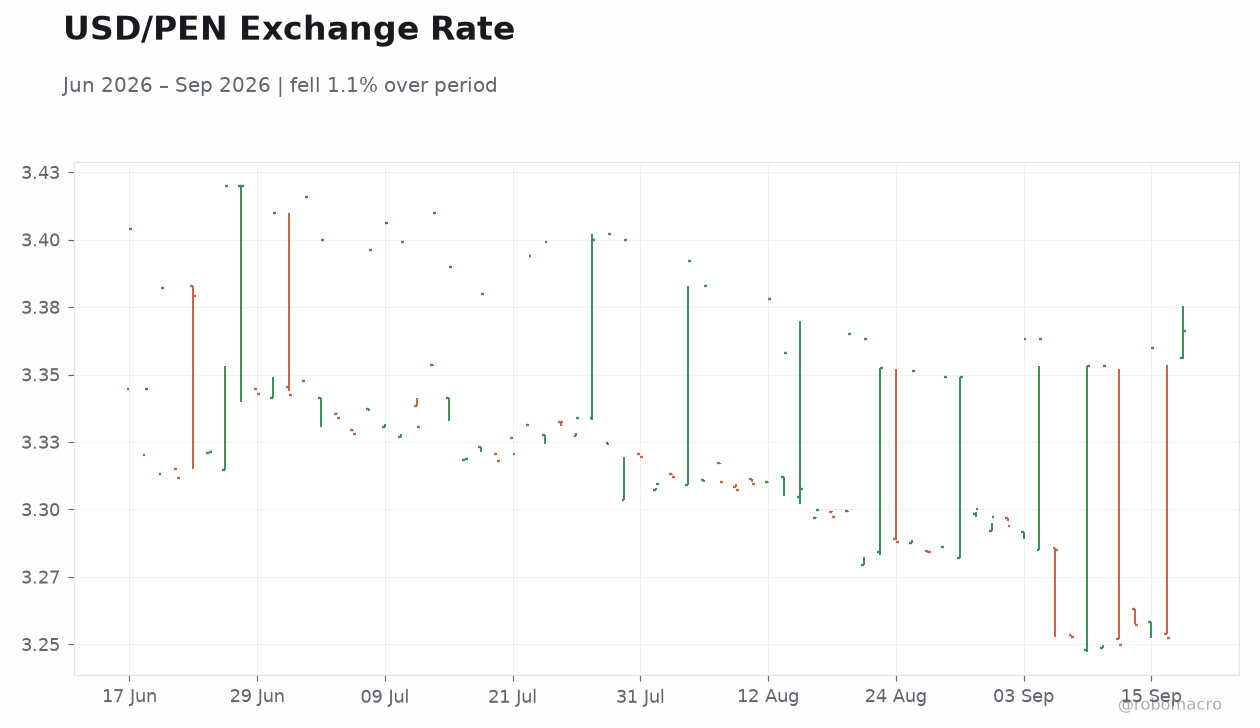
| USD/PEN | 3.37 | +3.73% |
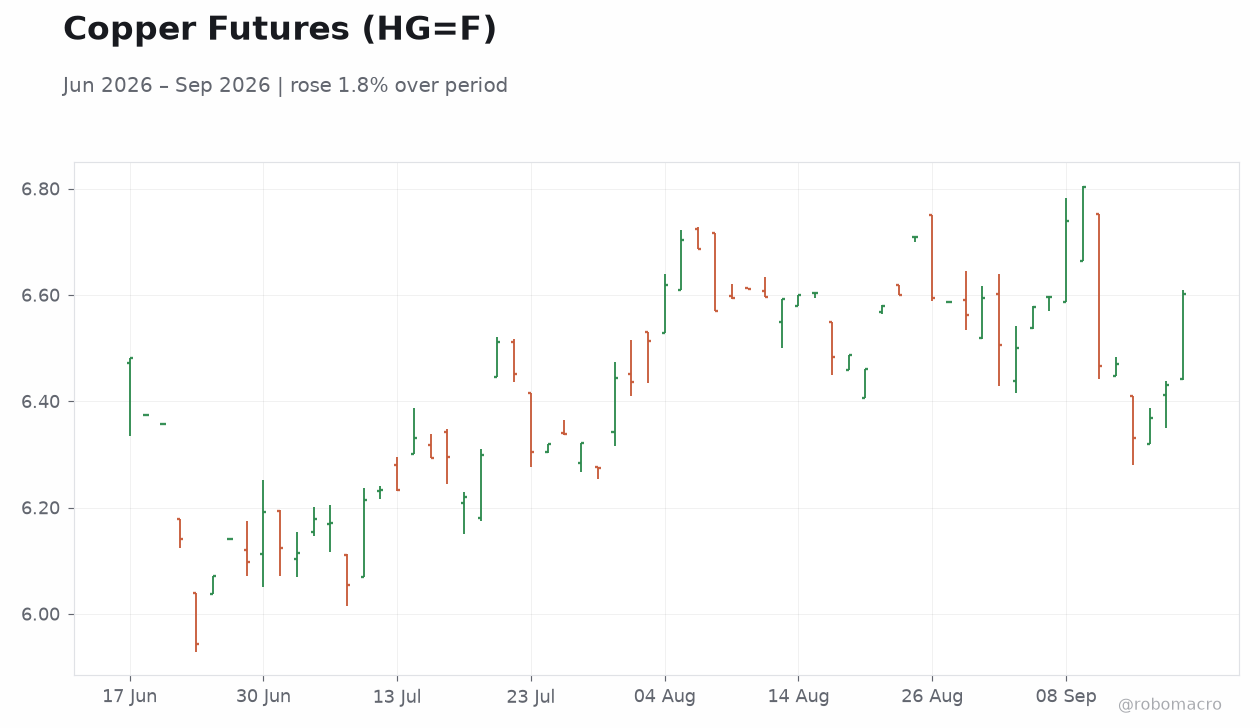
| Copper | 6.61 | +2.71% |
| Gold | 4,378.30 | -0.21% |
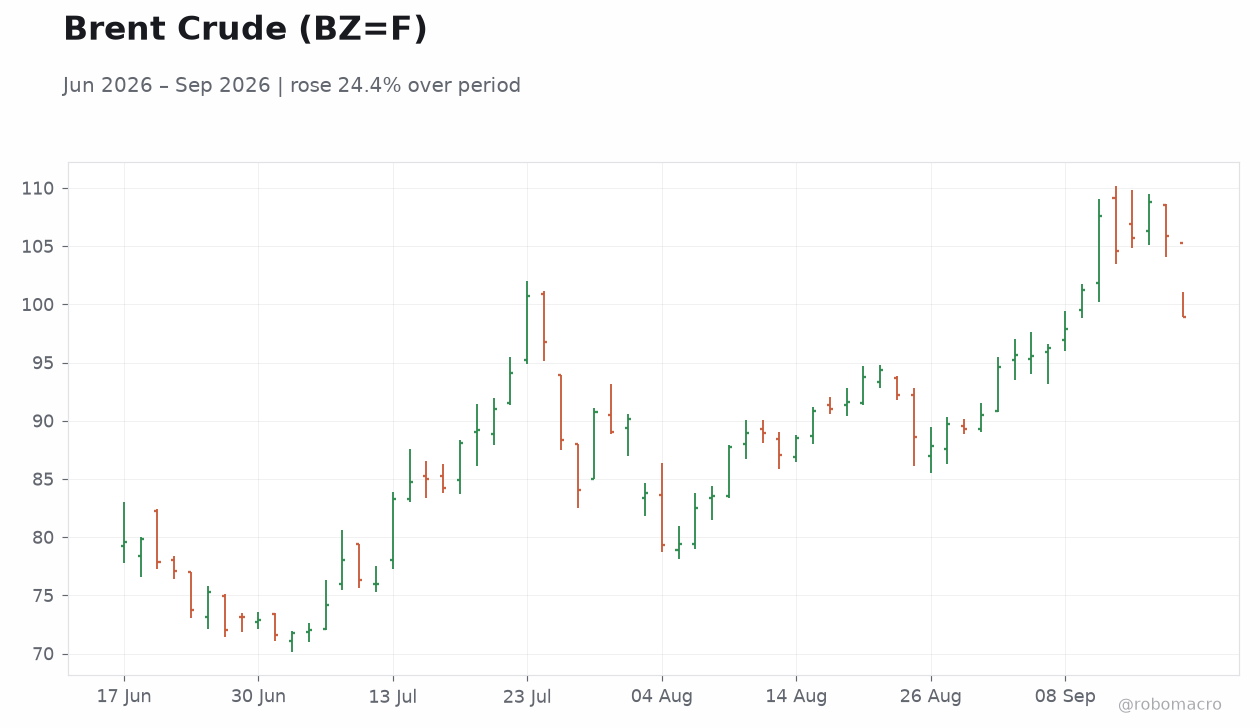
| Brent Crude | 99.05 | -6.41% |
| Bitcoin | 76,328.87 | +0.23% |
| Colombia 10Y Govt Yield | 12.66% | +7 bp |
| Peru 10Y Govt Yield | 6.59% | +11 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
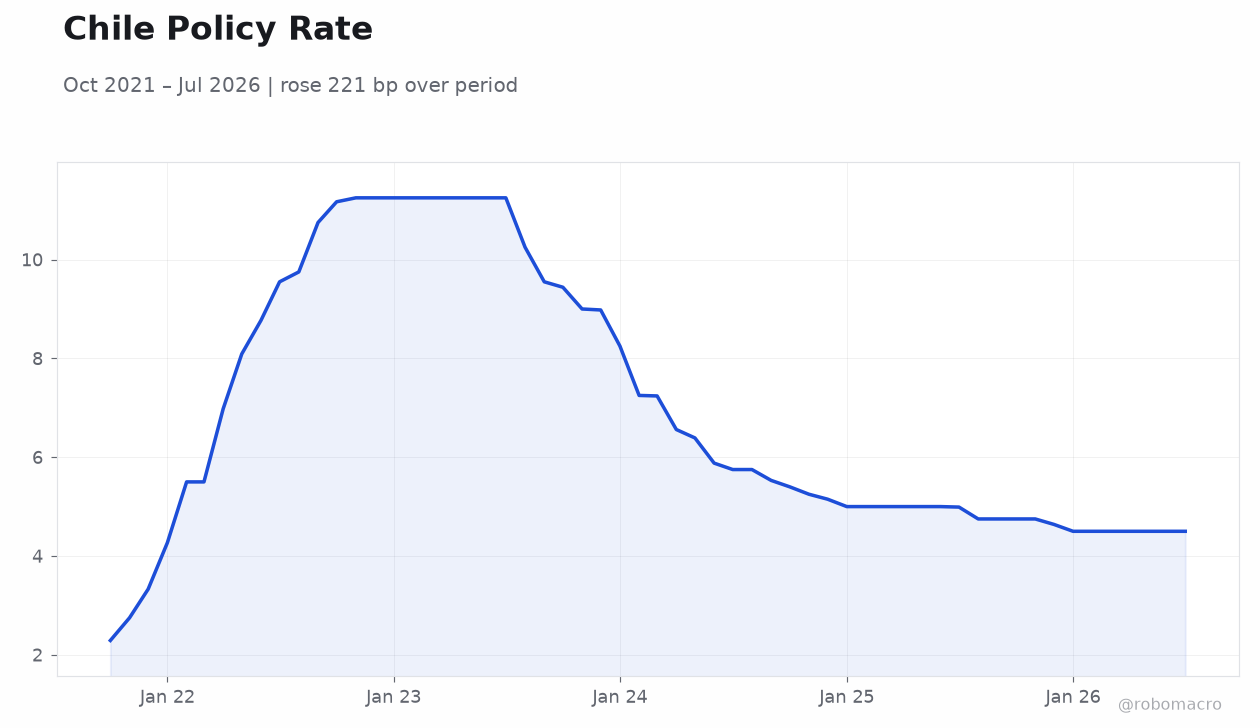
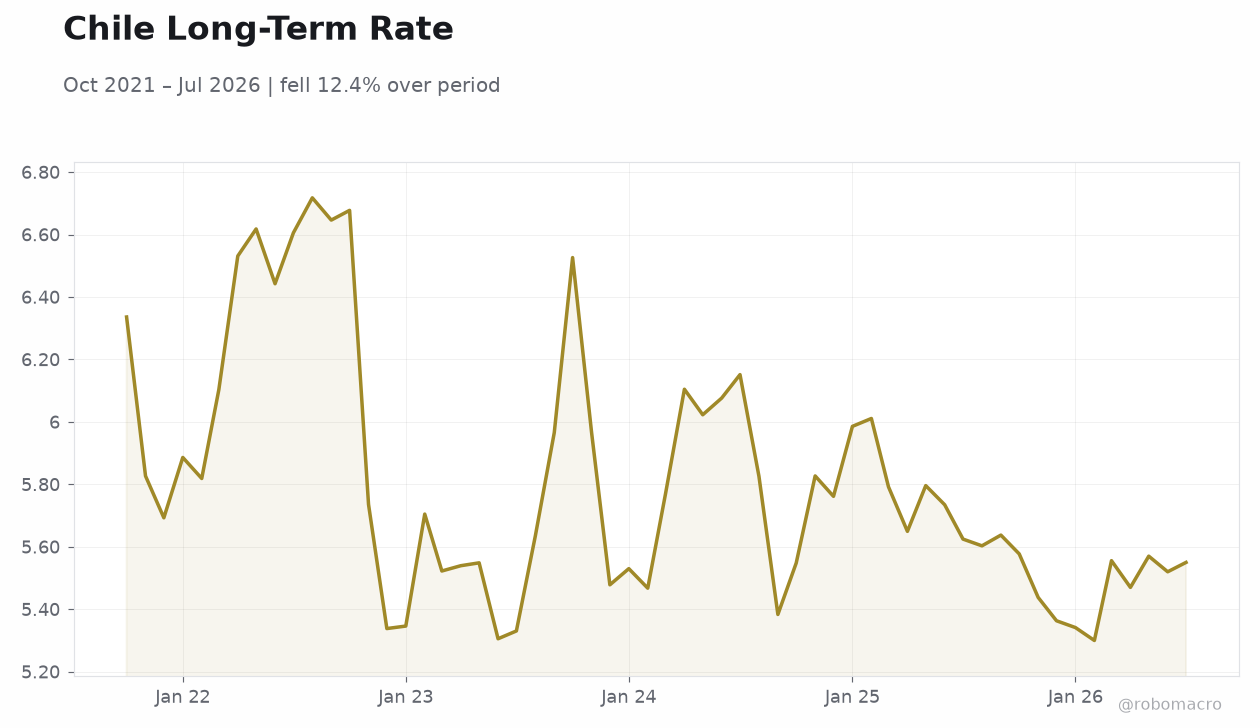 Chile Long-Term Rate | Type: macro_line | Yield %: 5.55 (2026-07-01) | Range: 5.3–6.718 | Trend(6pt): 6.336,5.338,5.468,5.649,5.52,5.55
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MSCI Peru rose 0.85% while Chile equities fell 0.46% and Colombia held flat amid mixed commodity moves.
- USD/PEN surged 3.73% to 3.37 as the sol depreciated sharply; Colombia 10Y yields rose 7 bp to 12.66% and Peru 10Y yields climbed 11 bp to 6.59%.
- Copper jumped 2.71% to 6.61, supporting Chile and Peru mining revenues, while Brent crude dropped 6.41% to 99.05, pressuring Colombia’s fiscal accounts.
Yesterday's Recap
Equity markets showed regional divergence on September 16 with MSCI Peru advancing 0.85% to 89.27 on copper strength while MSCI Chile declined 0.46% to 38.95 and MSCI Colombia remained unchanged at 9.02. FX markets recorded a sharp 3.73% jump in USD/PEN to 3.37, reflecting notable sol depreciation, whereas USD/COP edged 0.02% higher to 3,122.91 and USD/CLP eased 0.14% to 953.58. Commodity prices moved in opposing directions as copper surged 2.71% to 6.61, bolstering export revenues for Chile and Peru, while Brent crude plunged 6.41% to 99.05, weighing on Colombia’s oil-linked fiscal position, and gold slipped 0.21% to 4,378.30.
Sovereign yields increased across the board with Colombia’s 10-year yield rising 7 bp to 12.66% and Peru’s 10-year yield advancing 11 bp to 6.59%. No macroeconomic data releases occurred in Colombia, Chile or Peru, leaving market participants to focus solely on commodity price signals and external flows. Record August gold output at Aguia Resources’ Santa Barbara project in Colombia offered a positive note for future royalty streams though it did not yet alter aggregate export figures.
The Day Ahead
The economic calendar remains empty for Colombia, Chile and Peru with no CPI prints, GDP releases, trade balances, central-bank meetings or sovereign auctions scheduled. Market attention will therefore stay on global commodity prices, particularly copper and Brent crude, given their direct fiscal and current-account implications for the three economies. Copper’s recent advance should continue to support mining royalties and tax receipts in Chile and Peru while any further Brent weakness could widen Colombia’s fiscal gap through lower Ecopetrol revenues.
FX markets may see continued volatility in the PEN after yesterday’s sharp move, with COP and CLP likely to track broader risk sentiment. Investors will also monitor any updates on lithium-related projects in Chile that could influence medium-term capital flows.
Other Economic Notes
Copper’s 2.71% rally provides direct fiscal relief to Chile and Peru where mining exports dominate current-account balances and government revenue through royalties and taxes. Sustained higher prices should widen fiscal surpluses and eventually support local currencies, though immediate FX reactions remained muted. ↓ p.2