Andeans Macro Daily(Beta Mode)
Chile, Peru Stocks Rise as Copper Climbs
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
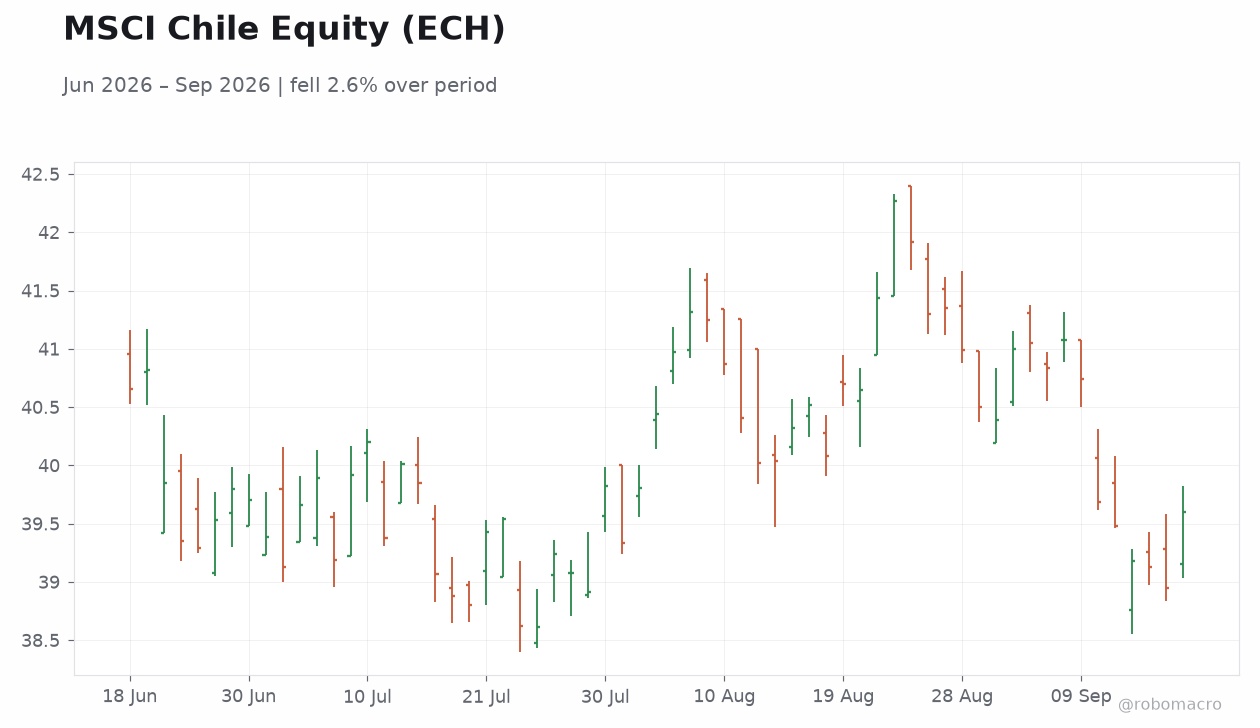
| MSCI Chile | 39.60 | +1.67% |
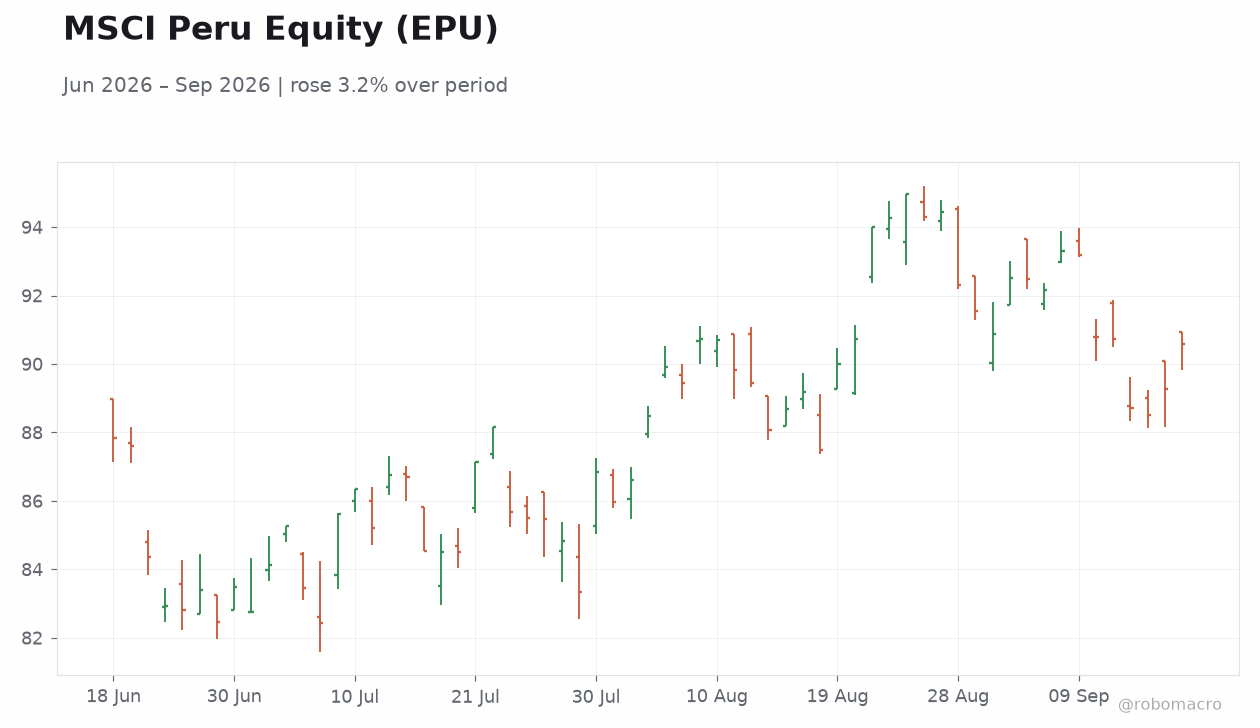
| MSCI Peru | 90.60 | +1.49% |
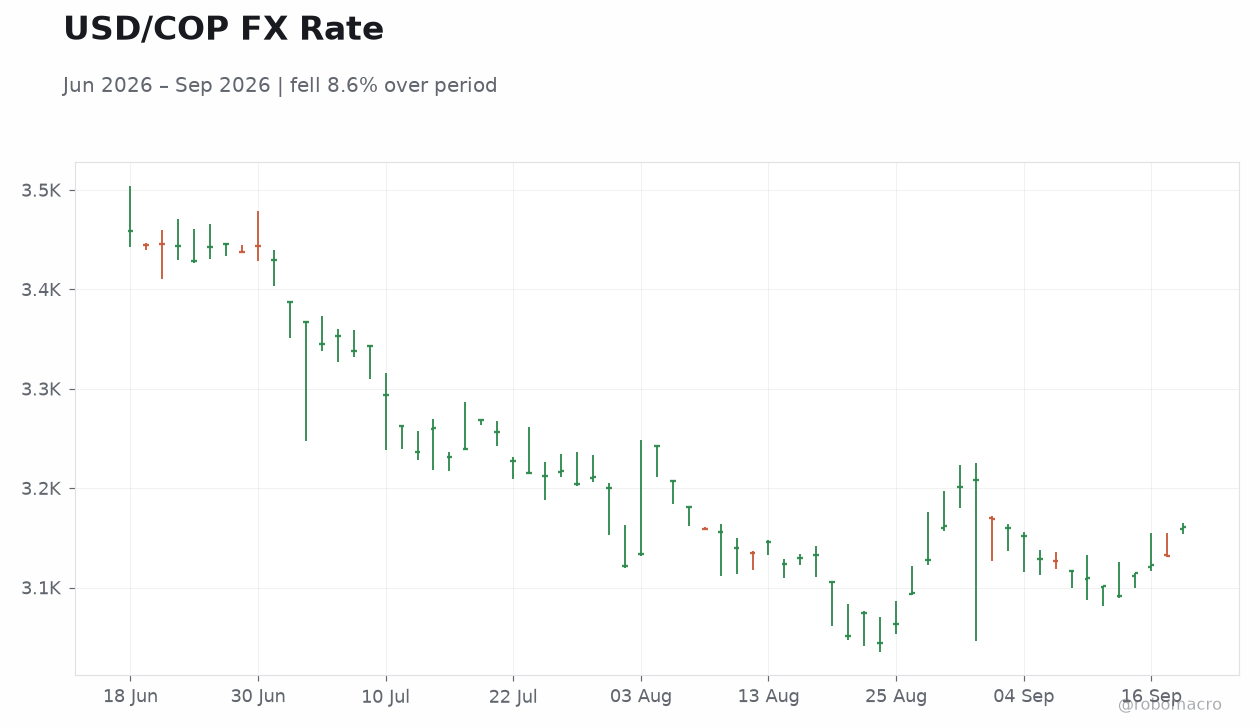
| USD/COP | 3,160.95 | +0.92% |
| USD/CLP | 960.65 | +0.69% |
| USD/PEN | 3.37 | +0.49% |
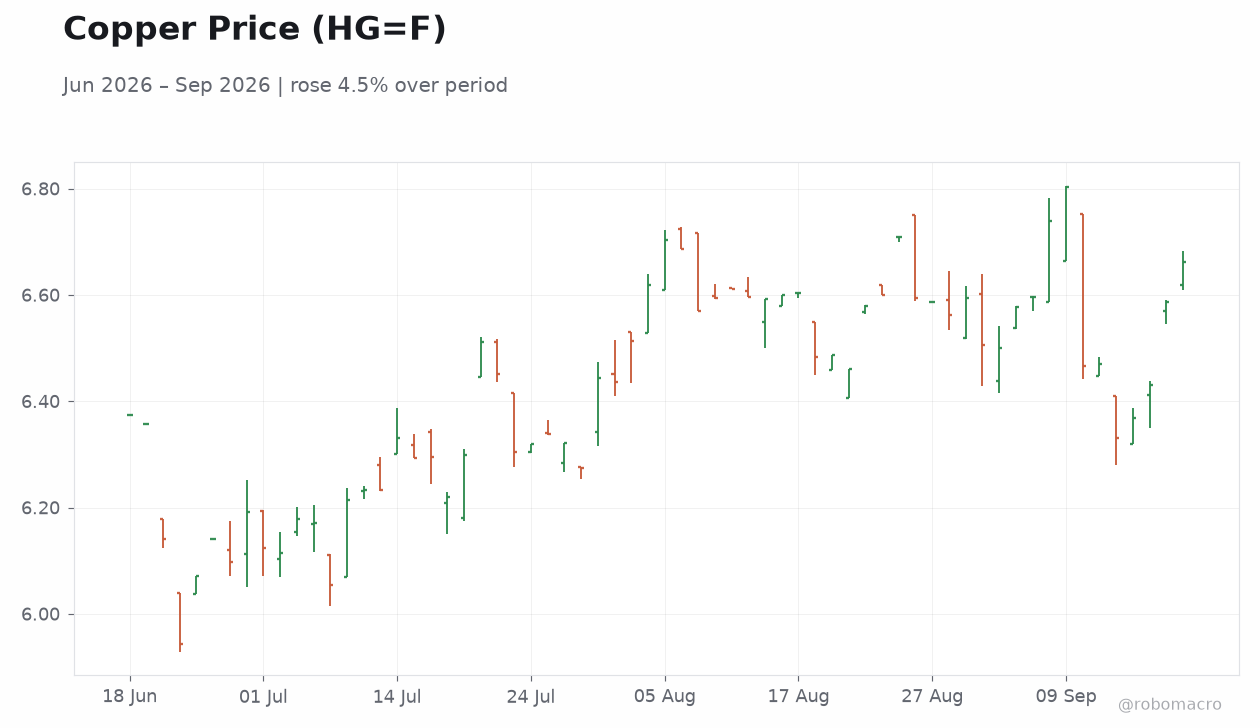
| Copper | 6.66 | +1.06% |
| Gold | 4,425.70 | +0.59% |
| Brent Crude | 98.63 | -5.91% |
| Bitcoin | 78,051.96 | +2.16% |
| Colombia 10Y Govt Yield | 12.66% | +7 bp |
| Peru 10Y Govt Yield | 6.60% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
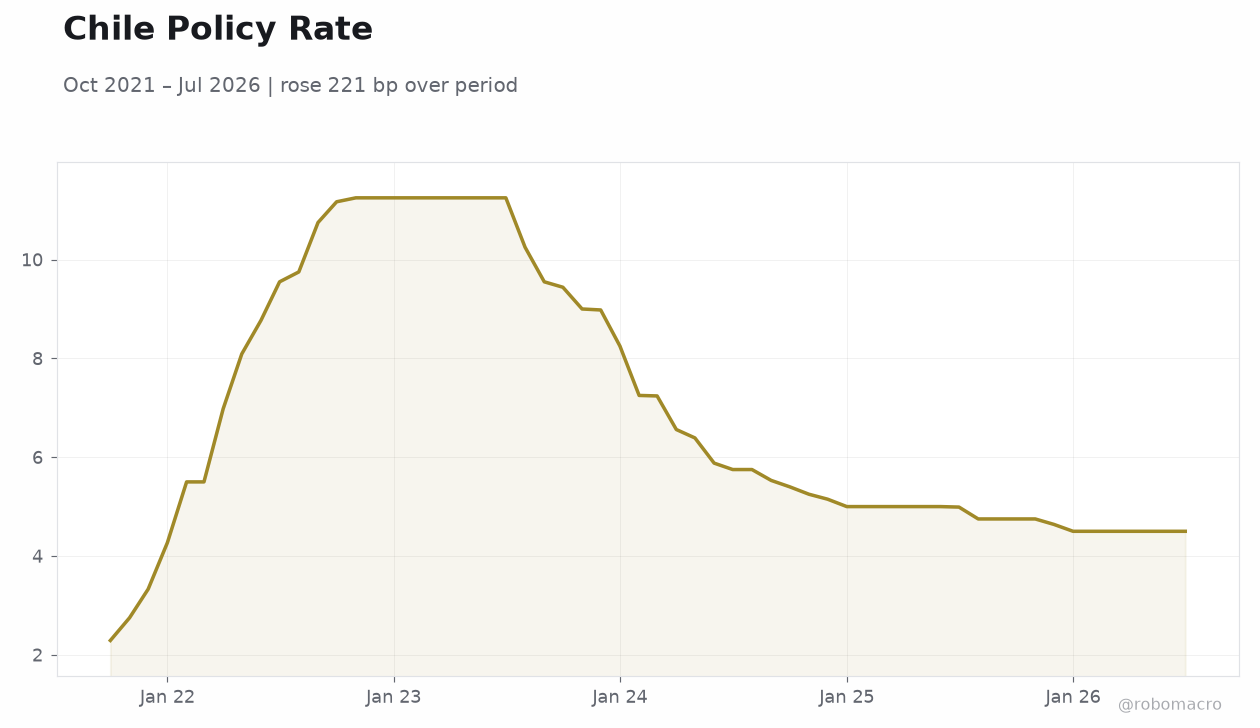 Chile Policy Rate | Type: macro_line | Rate %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MSCI Chile rose 1.67% and MSCI Peru gained 1.49% while MSCI Colombia stayed flat.
- USD/COP climbed 0.92%, USD/CLP rose 0.69% and USD/PEN advanced 0.49% as Brent crude fell 5.91%.
- Colombia 10Y yield increased 7 bp to 12.66% and Peru 10Y yield edged 1 bp higher to 6.60%.
Yesterday's Recap
No macroeconomic releases occurred in Colombia, Chile or Peru on 17 September. Equity markets showed divergence, with MSCI Chile and MSCI Peru posting solid gains while MSCI Colombia remained unchanged. All three Andean currencies depreciated against the dollar, led by the Colombian peso.
Copper advanced 1.06% to 6.66, supporting export revenues in Chile and Peru, whereas Brent crude’s sharp decline weighed on Colombia’s oil-linked fiscal receipts. Sovereign yields moved higher, with Colombia’s 10-year yield rising 7 bp to 12.66% and Peru’s 10-year yield increasing 1 bp to 6.60%. Gold’s modest 0.59% gain offered limited support to mining sectors across the region.
The absence of data left market participants focused on commodity price signals and external rate expectations. Copper’s advance aligns with signs of Chinese buying that lifted the metal after recent consolidation, directly benefiting the terms of trade for Chile and Peru.
The Day Ahead
The economic calendar remains empty across Colombia, Chile and Peru for the next three days. No CPI prints, GDP figures, trade balances or central-bank meetings are scheduled. Market attention will therefore stay on commodity price movements and any global risk signals.
Copper and oil volatility will continue to drive sentiment in Chile, Peru and Colombia respectively. FX traders will monitor USD strength and any shifts in external monetary policy expectations. Thin data flow raises the possibility of range-bound trading until the next batch of indicators appears.
Chile’s consideration of an ethanol-gasoline blend to ease fuel costs amid fiscal strains adds a domestic policy angle that could interact with sustained high copper prices to stabilize budget balances.
Other Economic Notes
Copper’s advance supports fiscal balances in Chile and Peru through higher royalty and tax collections. Sustained strength in the metal would ease pressure on Chile’s budget even as the government considers an ethanol-gasoline blend to reduce fuel costs. Brent’s steep drop raises downside risks for Colombia’s oil revenues and could widen the fiscal gap if prices remain low.
↓ p.2