Andeans Macro Daily(Beta Mode)
Colombia's Austerity Plan Eases Market Concerns
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 39.45 | -0.38% |
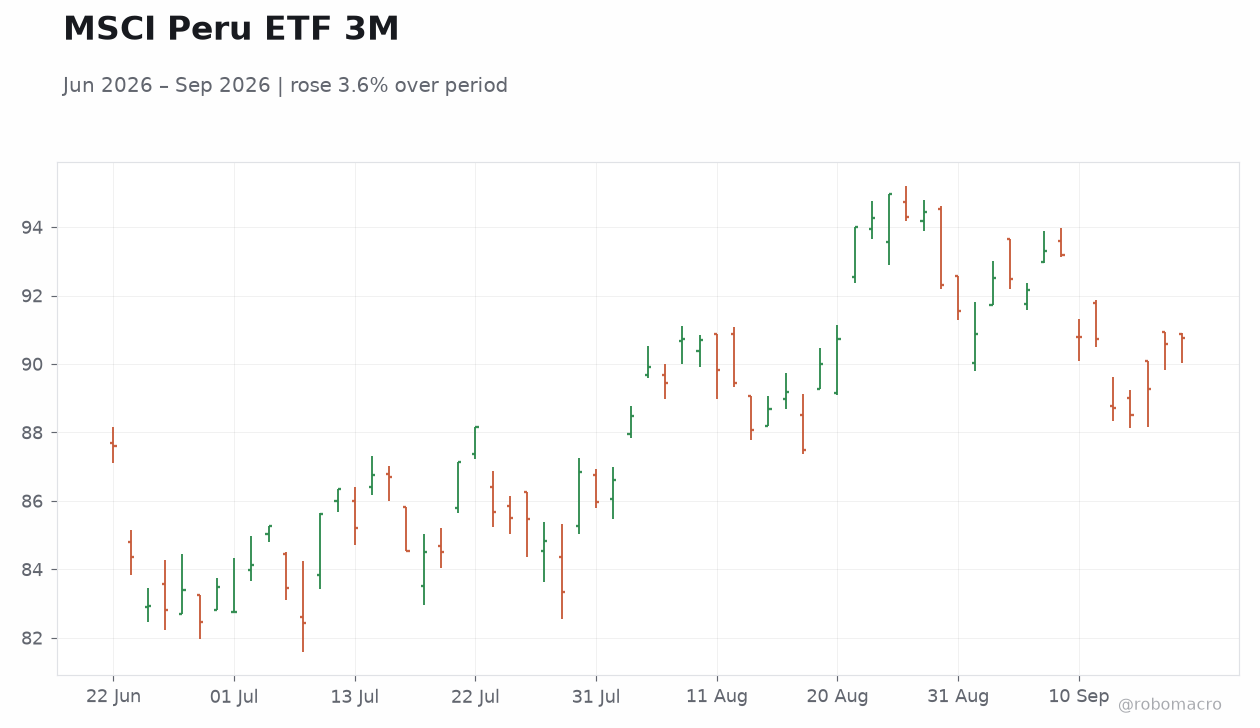
| MSCI Peru | 90.75 | +0.17% |
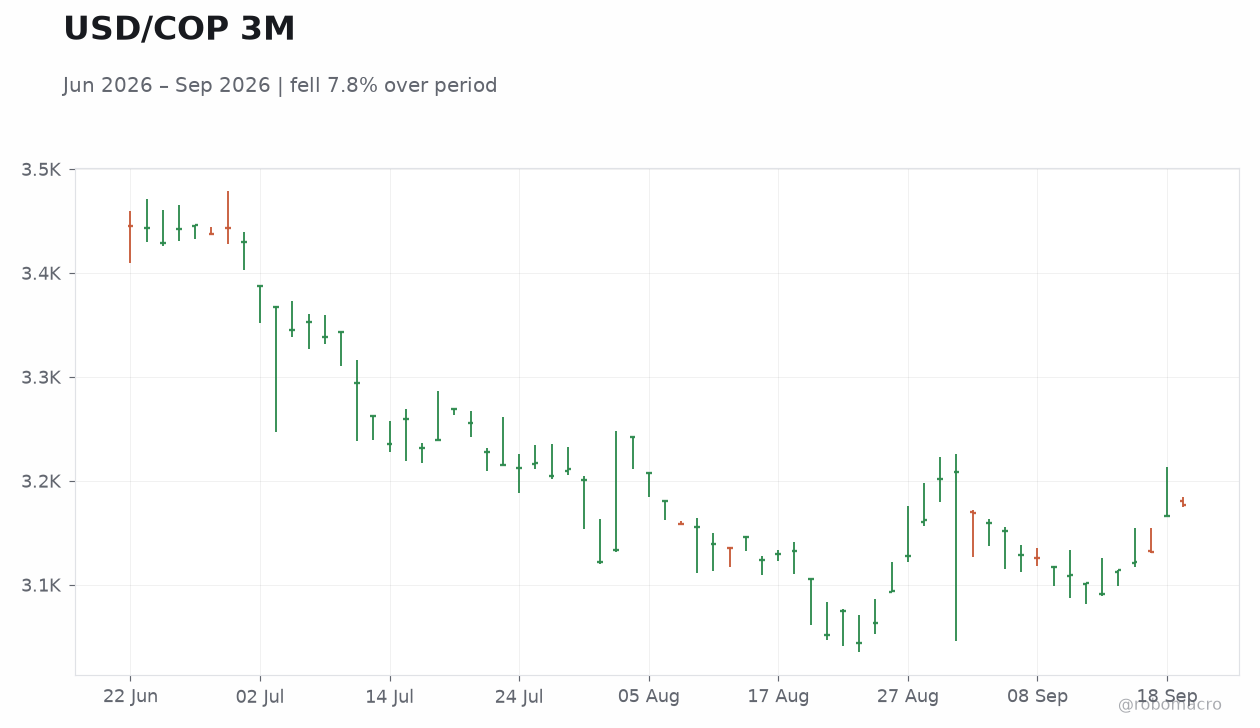
| USD/COP | 3,176.44 | +0.31% |
| USD/CLP | 953.80 | -0.65% |
| USD/PEN | 3.37 | +2.96% |
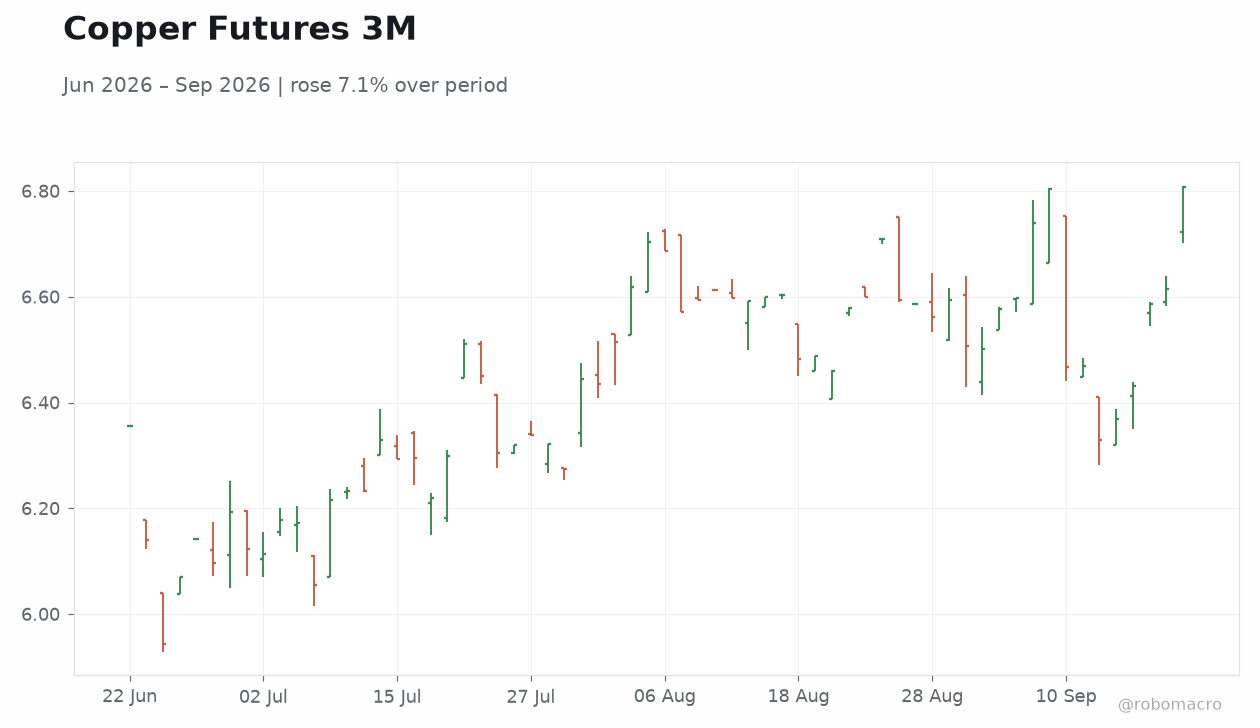
| Copper | 6.81 | +2.93% |
| Gold | 4,397.60 | -0.62% |
| Brent Crude | 97.02 | -6.59% |
| Bitcoin | 84,728.50 | +4.42% |
| Colombia 10Y Govt Yield | 12.66% | +7 bp |
| Peru 10Y Govt Yield | 6.59% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
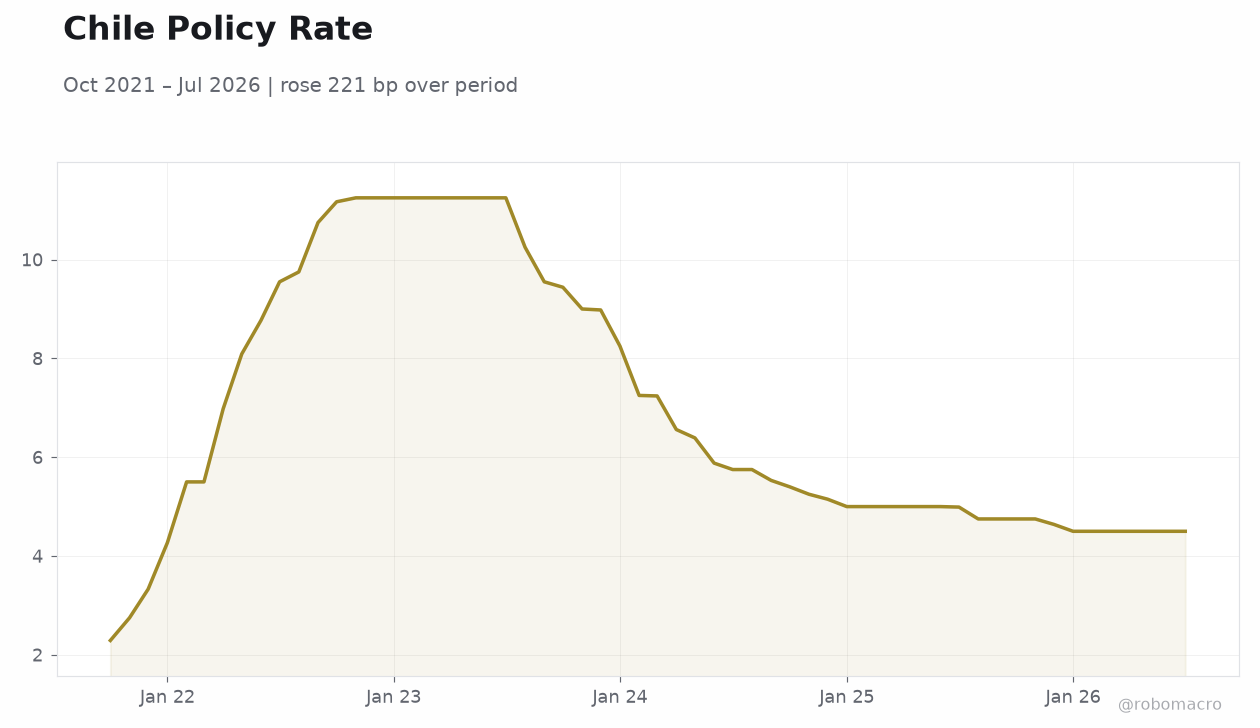 Chile Policy Rate | Type: macro_line | Rate %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Colombia finance officials pitch austerity to Wall Street, signaling lower external borrowing needs.
- Copper surges 2.93% to 6.81, lifting Peru equities while Chile debt attracts record foreign inflows.
- Brent crude drops 6.59% to 97.02, pressuring Colombia fiscal outlook amid stable regional yields.
Yesterday's Recap
No macroeconomic releases occurred across Colombia, Chile or Peru on September 20. MSCI Colombia held steady at 9.02 while MSCI Chile declined 0.38% to 39.45 and MSCI Peru advanced 0.17% to 90.75. USD/COP rose 0.31% to 3,176.44 and USD/PEN jumped 2.96% to 3.37, whereas USD/CLP fell 0.65% to 953.80.
Colombia’s 10-year government yield climbed 7 bp to 12.66%. Peru’s 10-year yield eased 1 bp to 6.59%. Colombia’s new finance chief presented an austerity plan to investors in New York, projecting roughly half the previously budgeted external borrowing for next year and easing concerns after the recent budget shock.
Foreign investors increased holdings of Chilean government debt to record levels, reflecting renewed confidence in the country’s fiscal stance amid broader “Sell America” flows. Copper’s 2.93% advance supported modest gains in Peru’s equity index, while Chile’s equity market lagged despite the commodity rally. Brent’s 6.59% decline weighed on Colombia’s fiscal position given oil’s weight in exports and government revenue.
Gold’s 0.62% decline to 4,397.60 carried limited immediate impact on Andean producers.
The Day Ahead
No scheduled economic data releases or central bank meetings appear on the calendar for Colombia, Chile or Peru. Markets will likely monitor copper and oil price swings for signals on fiscal and current-account balances. Chile’s large copper sector stands to gain from higher export revenues and royalty receipts.
Peru’s mining trade balance could receive support from improved volumes and prices. Colombia’s fiscal position remains sensitive to the Brent decline given oil’s weight in government revenue. Investors may also track any follow-up comments from Colombian officials after the Wall Street meetings.
Bitcoin’s 4.42% rise to 84,728.50 reflects broader risk-on flows that could indirectly benefit regional equities.
Other Economic Notes
Copper’s advance supports improved fiscal balances in Chile and Peru through higher mining export earnings. Brent’s sharp drop weighs on Colombia’s current account and budget outlook. Gold’s 0.62% decline to 4,397.60 carries limited immediate impact on Andean producers.
↓ p.2