Andeans Macro Daily(Beta Mode)
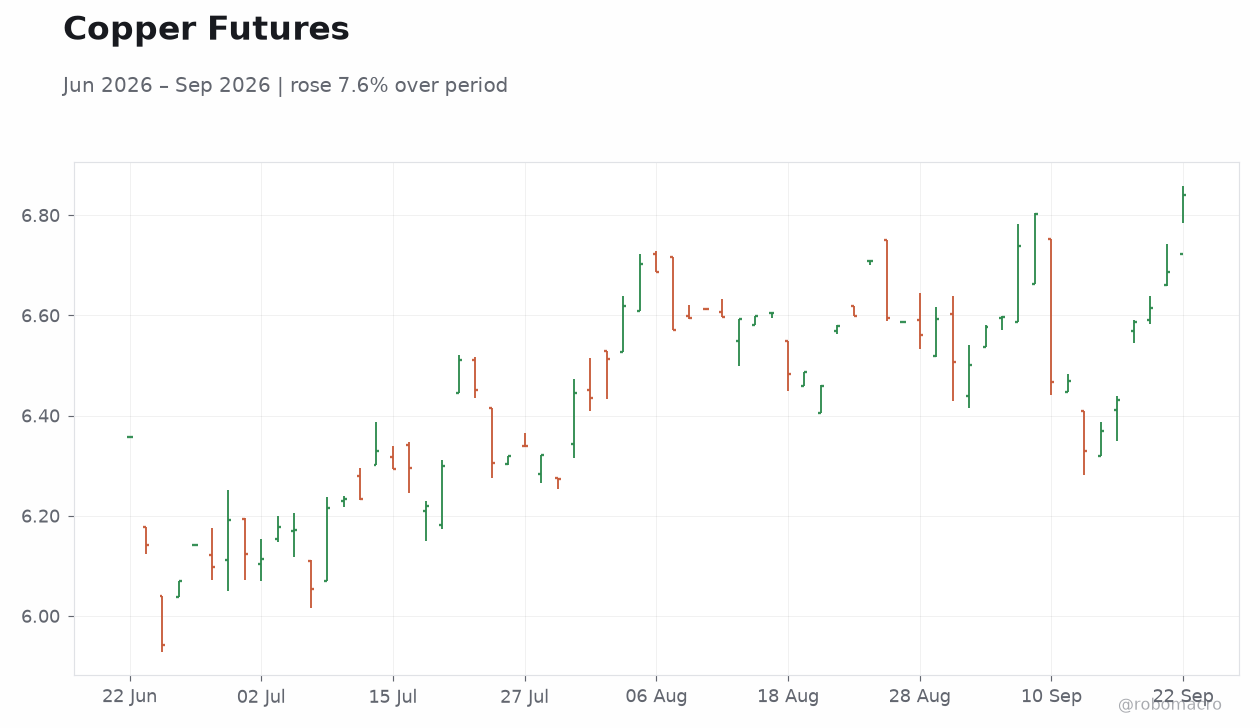
Copper Rally Lifts Chile, Peru Markets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
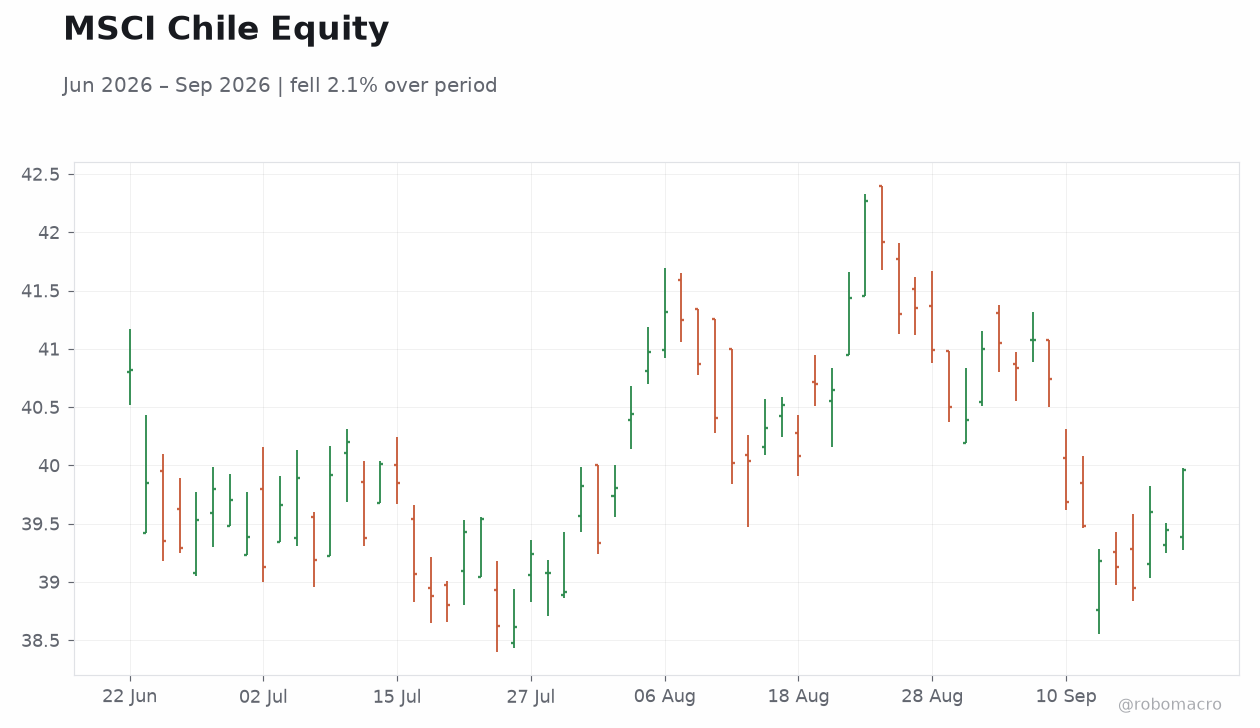
| MSCI Chile | 39.96 | +1.29% |
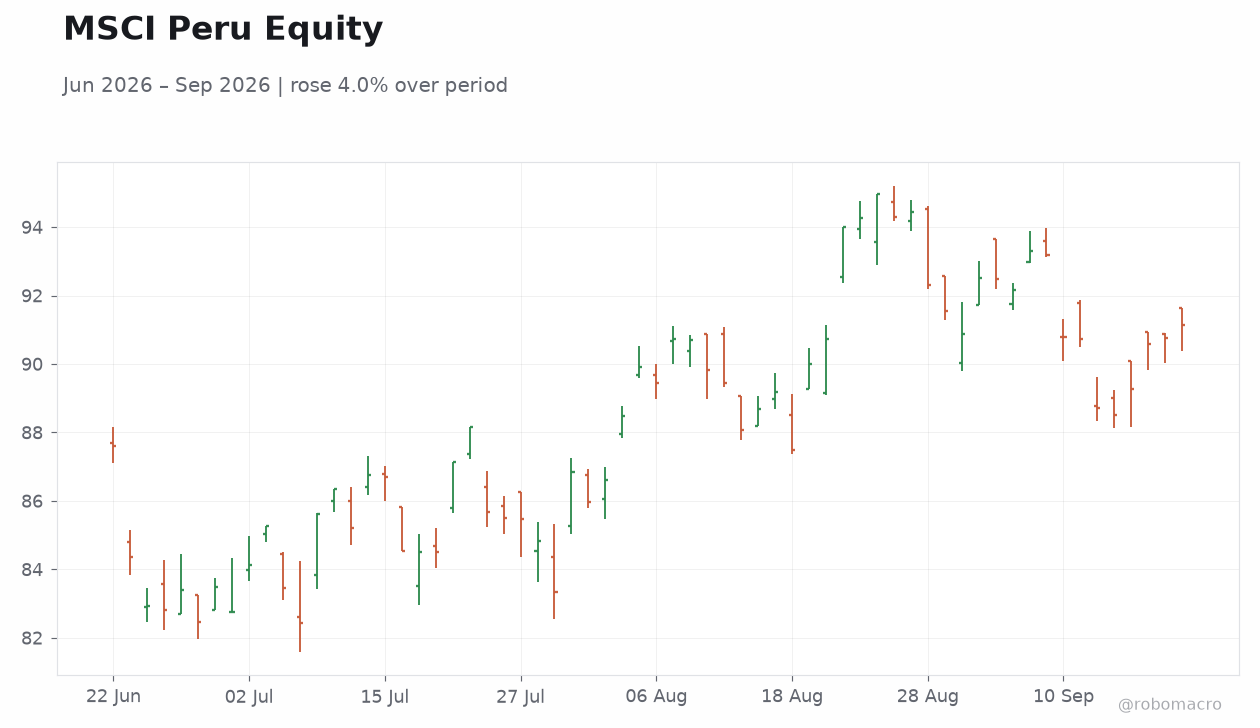
| MSCI Peru | 91.14 | +0.43% |
| USD/COP | 3,194.53 | +0.58% |
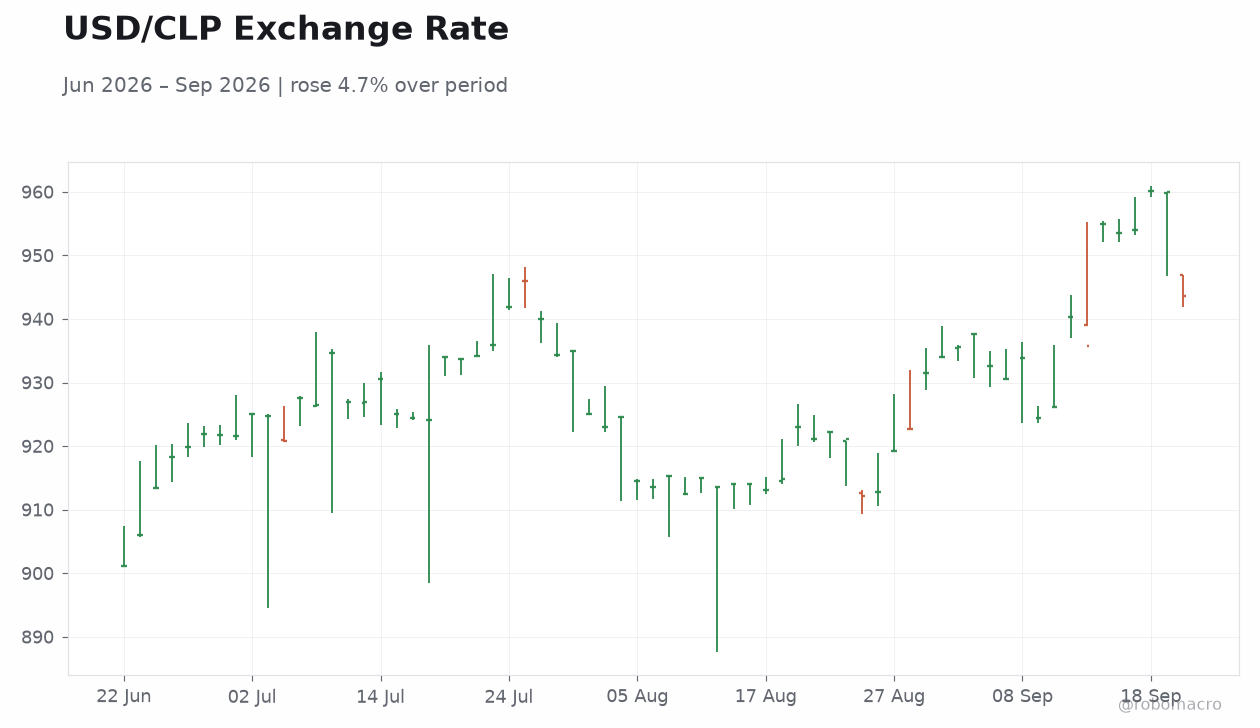
| USD/CLP | 943.60 | -1.70% |
| USD/PEN | 3.38 | +3.32% |
| Copper | 6.84 | +2.28% |
| Gold | 4,348.00 | -0.82% |
| Brent Crude | 98.63 | -1.70% |
| Bitcoin | 86,010.02 | -0.68% |
| Colombia 10Y Govt Yield | 12.91% | +16 bp |
| Peru 10Y Govt Yield | 6.59% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
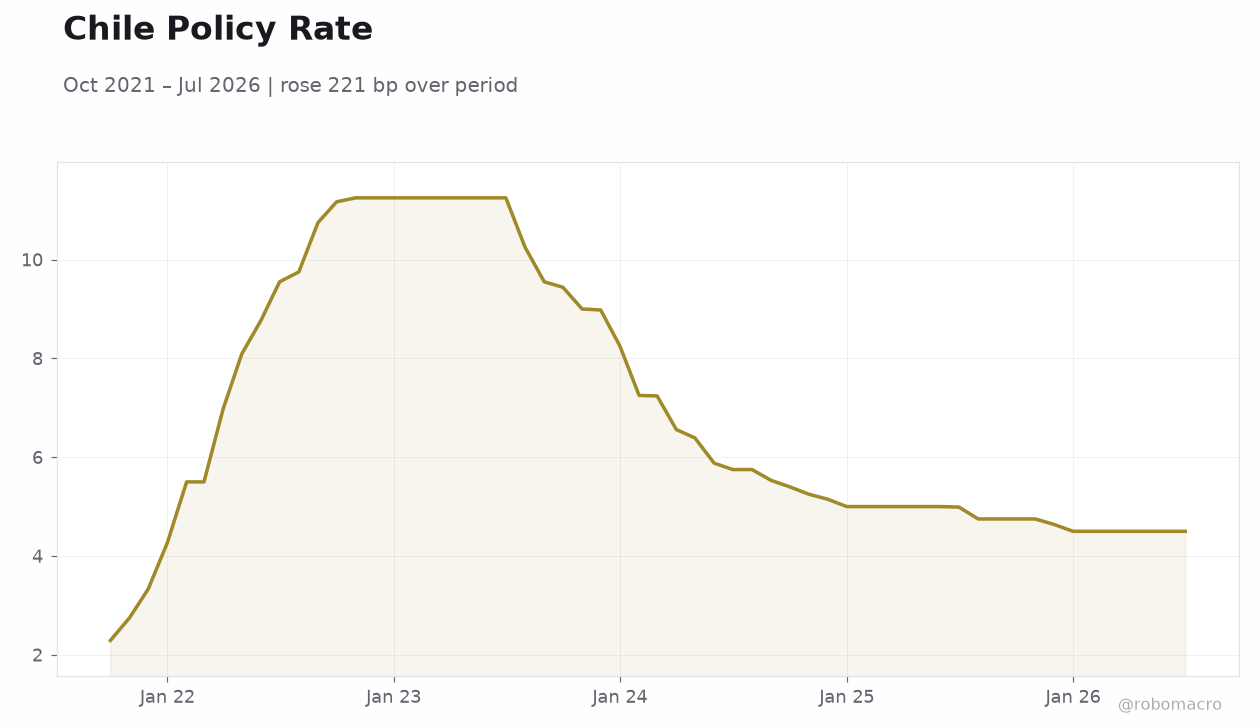 Chile Policy Rate | Type: macro_line | Rate %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MSCI Chile rose 1.29% to 39.96 as copper climbed 2.28% to 6.84
- Colombia 10Y yield jumped 16 bp to 12.91%; Peru 10Y eased 1 bp to 6.59
- Wildfire triggers public calamity declaration in Colombia near Villa de Leyva
Yesterday's Recap
Equity markets in the Andean region showed clear divergence on 21 September. MSCI Chile posted the strongest gain at 1.29% to 39.96, supported by the 2.28% advance in copper to 6.84. MSCI Peru rose 0.43% to 91.14 while MSCI Colombia remained flat at 9.02.
FX moves were mixed, with USD/CLP falling 1.70% to 943.60 on peso strength, USD/COP rising 0.58% to 3,194.53, and USD/PEN surging 3.32% to 3.38. Colombia’s 10-year government yield increased 16 bp to 12.91% as of 18 September while Peru’s 10-year yield declined 1 bp to 6.59% as of 17 September. Brent crude fell 1.70% to 98.63, narrowing Colombia’s oil-related fiscal buffers.
Colombia declared a public calamity after wildfires threatened Villa de Leyva and other areas amid dry conditions, with nearly 20 active fires reported. Gold fell 0.82% to 4,348.00 and Bitcoin slipped 0.68% to 86,010.02, while the absence of any CPI, GDP or trade data releases left commodity prices as the dominant driver for regional asset prices.
The Day Ahead
No economic data releases, central-bank meetings or sovereign debt auctions are scheduled for Colombia, Chile or Peru on 22-23 September. Markets will continue to track global commodity prices, especially copper and oil, for direction. Any updates on firefighting costs or reconstruction in Colombia could surface through official channels.
Investors will also monitor external drivers such as US data prints and Fed signals that influence regional risk sentiment. The quiet domestic calendar leaves room for commodity and FX volatility to dominate price action, with Chile and Peru positioned to benefit from sustained copper strength through higher mining royalties and export revenues while Colombia faces narrower oil-related fiscal space if Brent remains lower.
Other Economic Notes
The Inter-American Development Bank estimates that AI adoption could expand the Latin American and Caribbean economy by 5.1%, though wage pressures may emerge in lower-skill sectors. Copper’s advance provides direct fiscal and external-account support to Chile and Peru through higher mining revenues and royalties. Lower Brent prices reduce expected oil income for Colombia and could widen fiscal gaps if sustained.
↓ p.2