Andeans Macro Daily(Beta Mode)
Chile Equities Advance on Copper; PEN Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
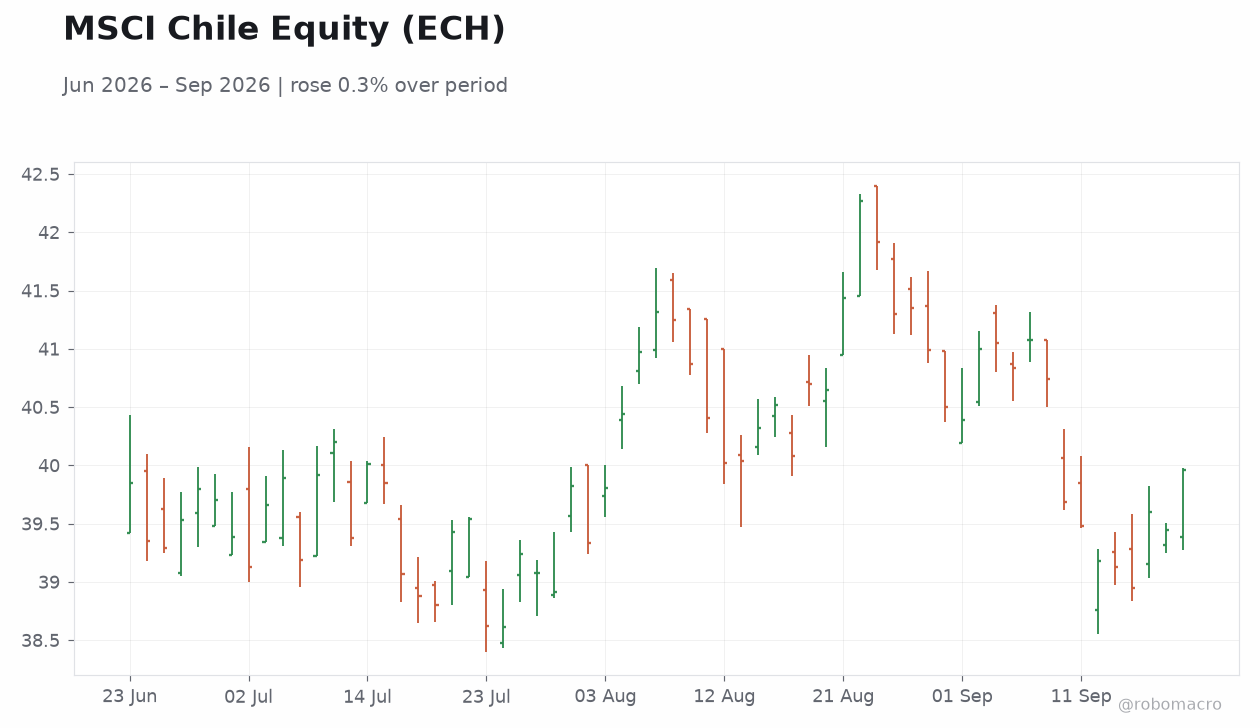
| MSCI Chile | 40.42 | +1.15% |
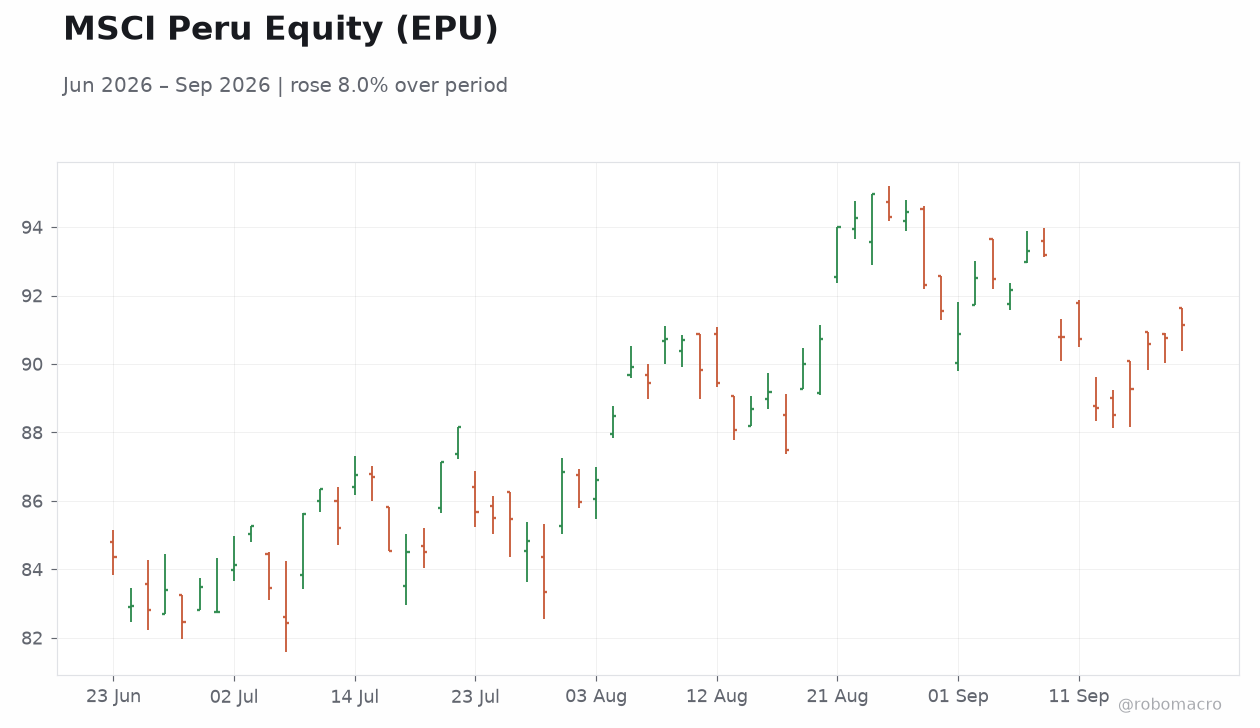
| MSCI Peru | 91.76 | +0.68% |
| USD/COP | 3,203.39 | -0.00% |
| USD/CLP | 951.22 | +0.40% |
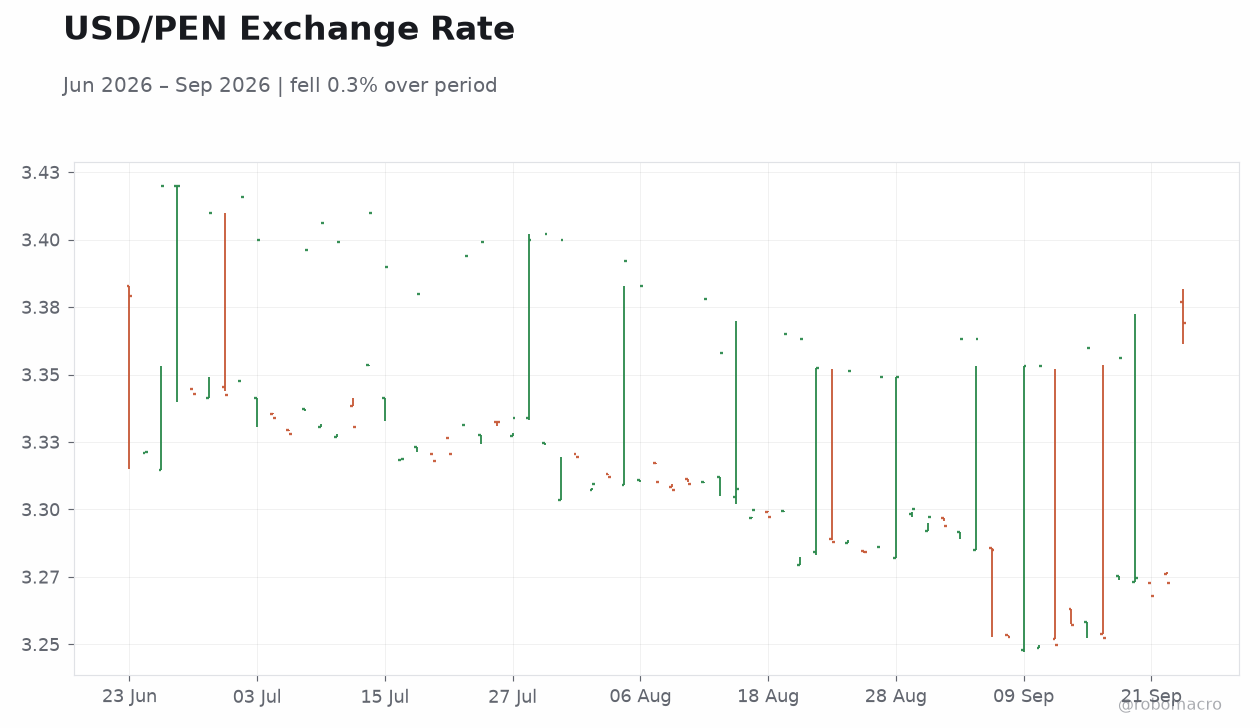
| USD/PEN | 3.37 | +2.95% |
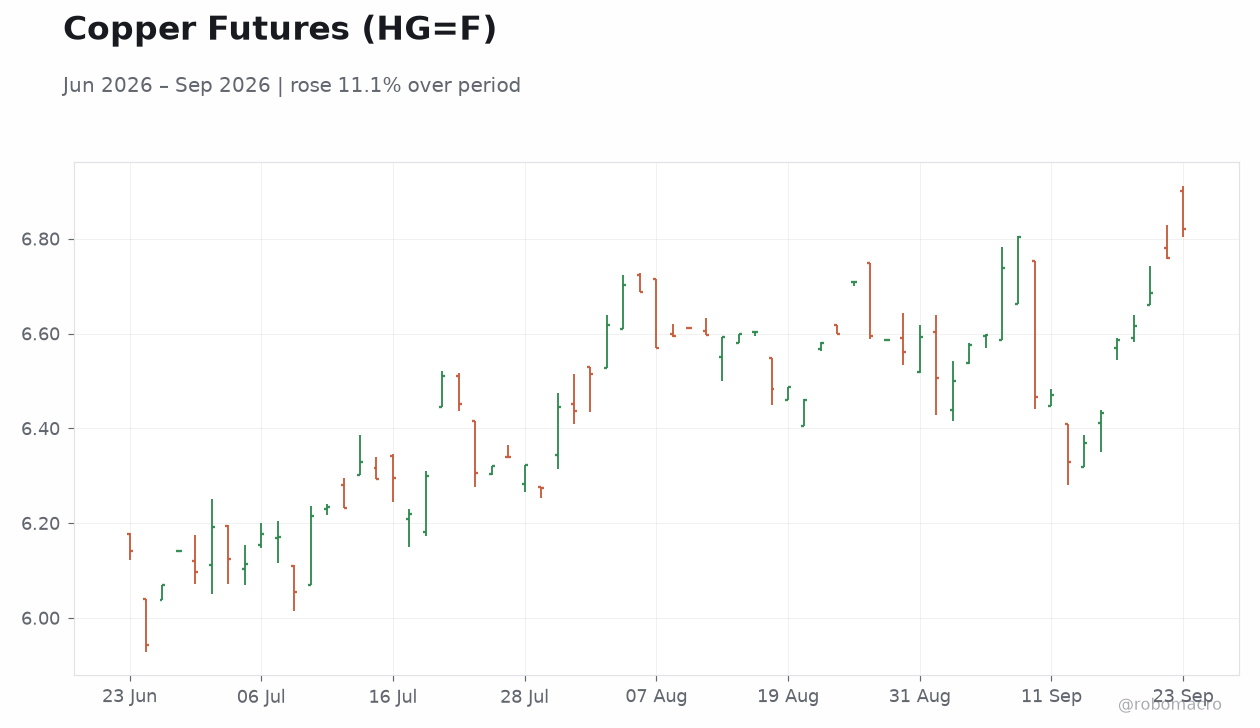
| Copper | 6.82 | +0.90% |
| Gold | 4,351.40 | -0.57% |
| Brent Crude | 95.85 | -3.43% |
| Bitcoin | 85,535.96 | -0.74% |
| Colombia 10Y Govt Yield | 12.91% | +16 bp |
| Peru 10Y Govt Yield | 6.59% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
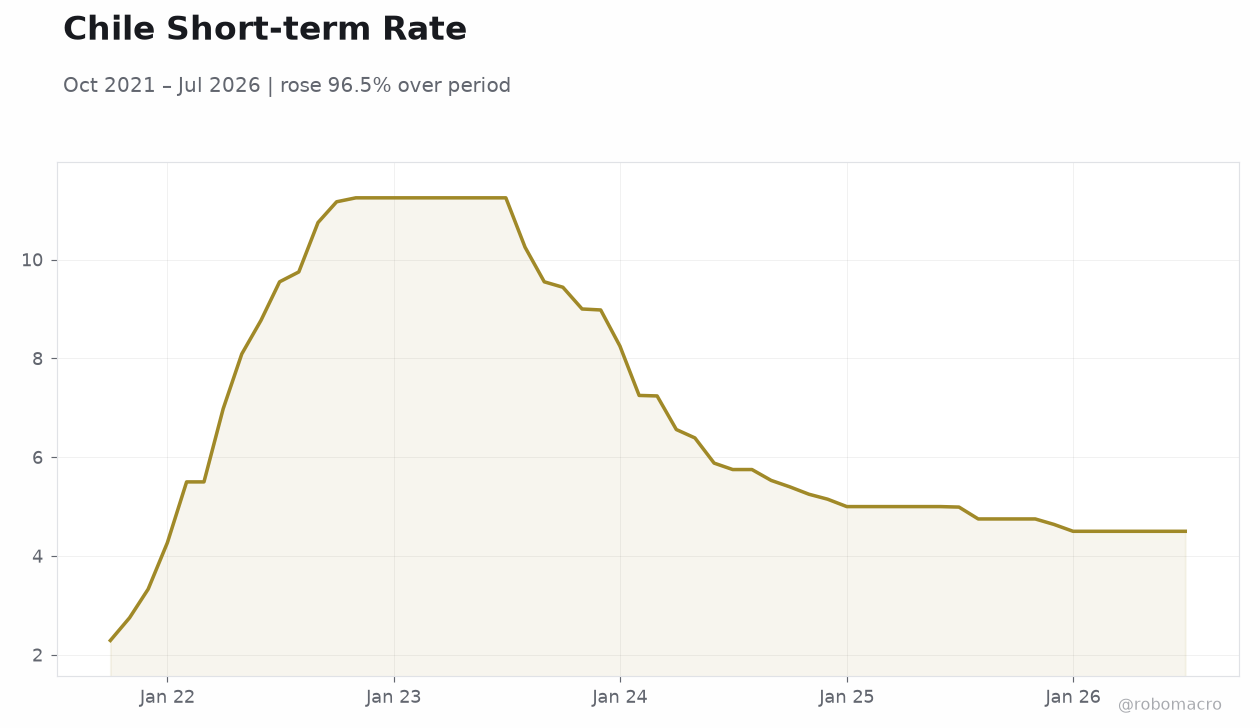 Chile Short-term Rate | Type: macro_line | %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MSCI Chile rose 1.15% while Peru equities gained 0.68% on copper strength; Colombia markets stayed flat.
- USD/PEN surged 2.95% amid broad USD moves, with CLP up 0.40% and COP unchanged.
- No economic data releases occurred across Colombia, Chile or Peru, leaving external factors dominant.
Yesterday's Recap
Equity markets in the Andean region posted mixed but generally positive results on September 22. MSCI Chile climbed 1.15% to 40.42, supported by a 0.90% advance in copper prices to 6.82. MSCI Peru rose 0.68% to 91.76, while MSCI Colombia remained unchanged at 9.02.
Currency markets diverged sharply, with USD/PEN jumping 2.95% to 3.37, USD/CLP increasing 0.40% to 951.22 and USD/COP holding steady at 3,203.39. Sovereign yields reflected limited domestic drivers, as Colombia’s 10-year yield rose 16 bp to 12.91% while Peru’s 10-year yield eased 1 bp to 6.59%. Brent crude’s 3.43% decline to 95.85 offered little support for Colombian fiscal revenues, and gold’s 0.57% drop to 4,351.40 provided minimal offset for mining sectors in Peru and Colombia.
With zero data releases reported, market moves stemmed primarily from commodity price shifts and external USD pressure.
The Day Ahead
The economic calendar remains empty for September 23-24 across Colombia, Chile and Peru, with no CPI prints, GDP figures, trade balances or central-bank meetings scheduled. Market participants will therefore focus on external commodity prices and any Fed-related signals that could influence regional FX. Copper’s recent gain should continue to underpin sentiment toward Chilean and Peruvian assets.
Oil price weakness may keep Colombian yields under modest pressure. Absent domestic catalysts, trading volumes in Andean currencies and equities could stay subdued.
Other Economic Notes
Copper’s advance supports improved export receipts and royalty income for Chile and Peru, though no new production data emerged to quantify the impact. Colombia faces headwinds from softer Brent prices that reduce near-term oil-related fiscal inflows. Peru’s sharp PEN depreciation raises imported inflation risks without offsetting domestic releases to clarify the trend.
Regional equity performance remains tightly linked to commodity cycles rather than local policy surprises. Broader USD strength continues to transmit external volatility into Andean FX markets.