Andeans Macro Daily(Beta Mode)
Andean FX Weakens as USD Strengthens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
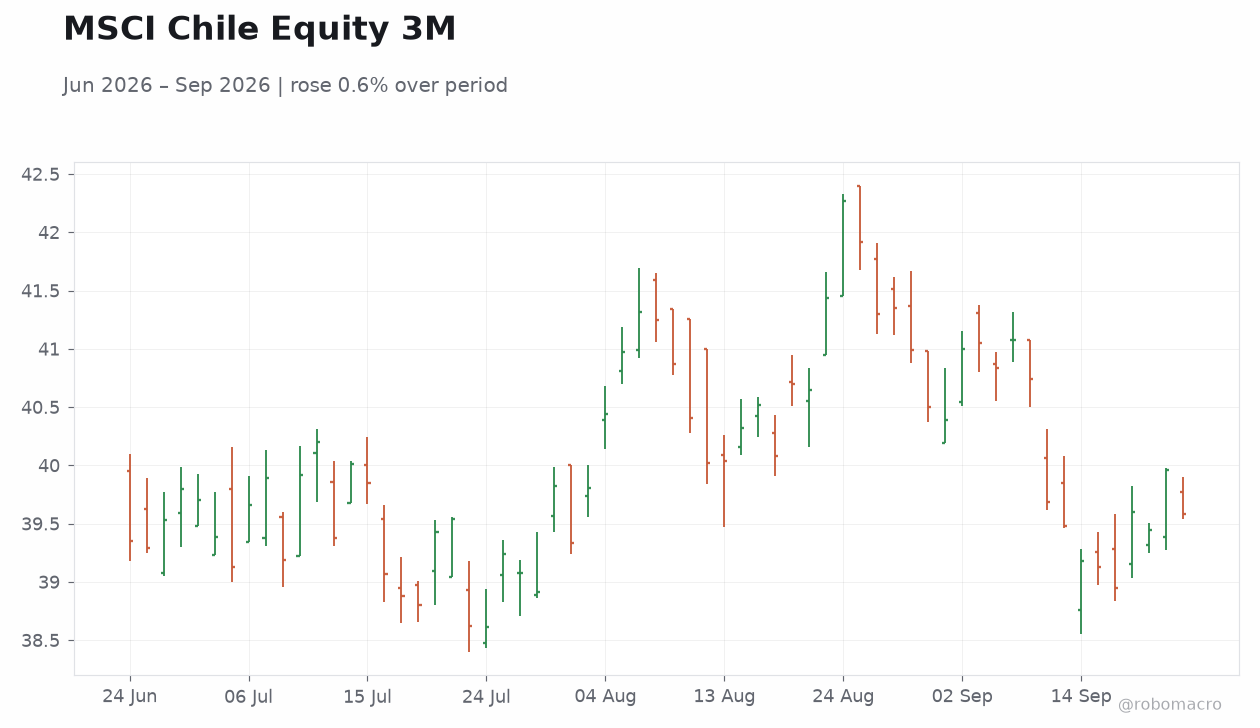
| MSCI Chile | 39.58 | -2.08% |
| MSCI Peru | 91.57 | -0.21% |
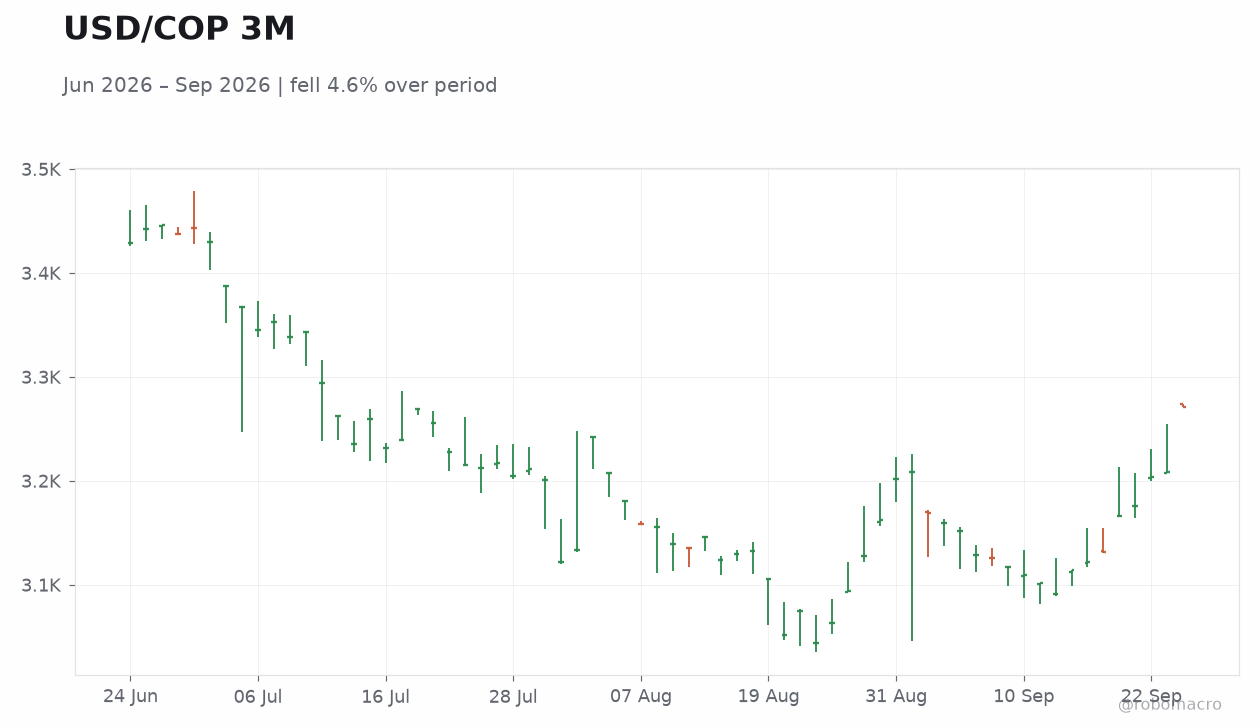
| USD/COP | 3,271.13 | +1.94% |
| USD/CLP | 962.70 | +1.68% |
| USD/PEN | 3.39 | +3.33% |
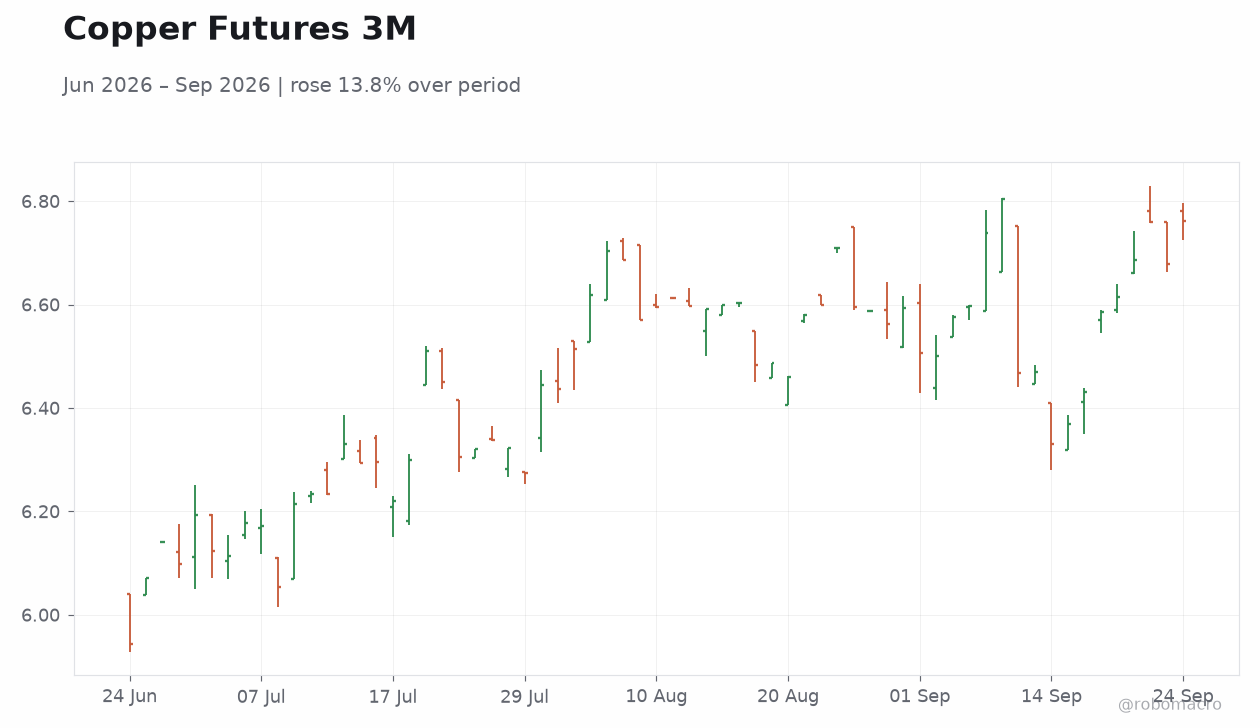
| Copper | 6.76 | +1.24% |
| Gold | 4,290.50 | -0.65% |
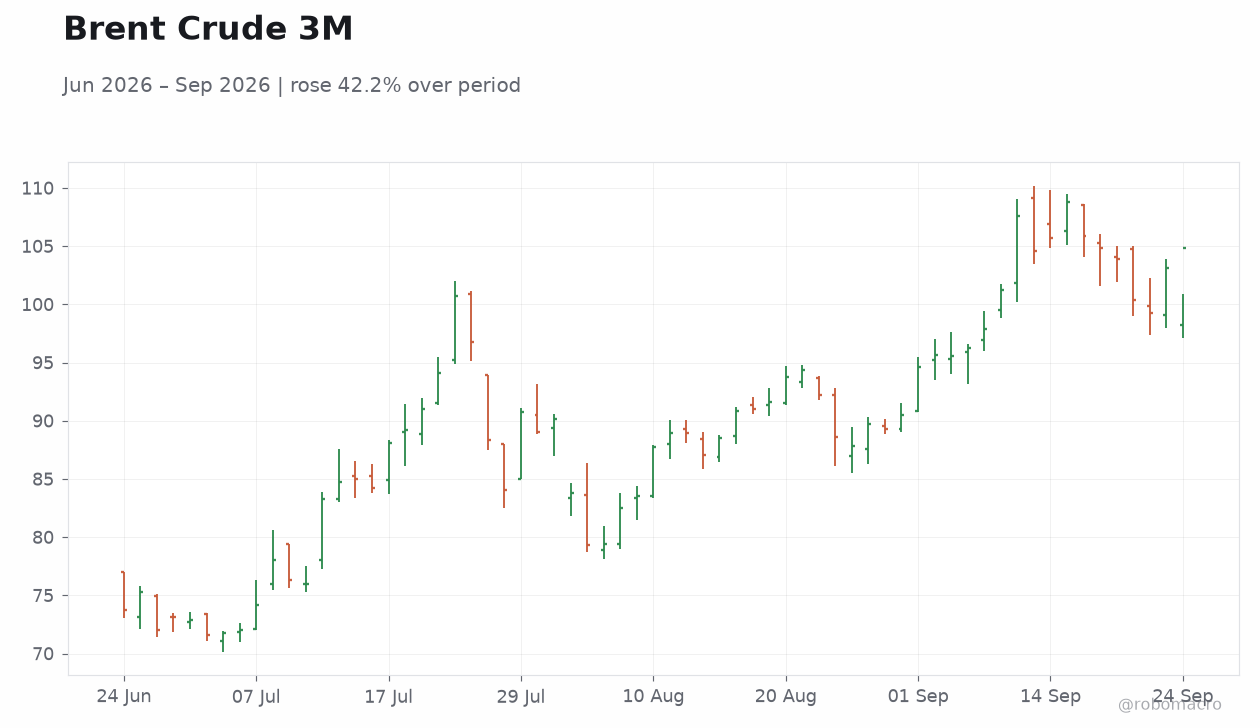
| Brent Crude | 104.83 | +1.70% |
| Bitcoin | 83,526.04 | -1.02% |
| Colombia 10Y Govt Yield | 12.91% | +16 bp |
| Peru 10Y Govt Yield | 6.54% | -5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
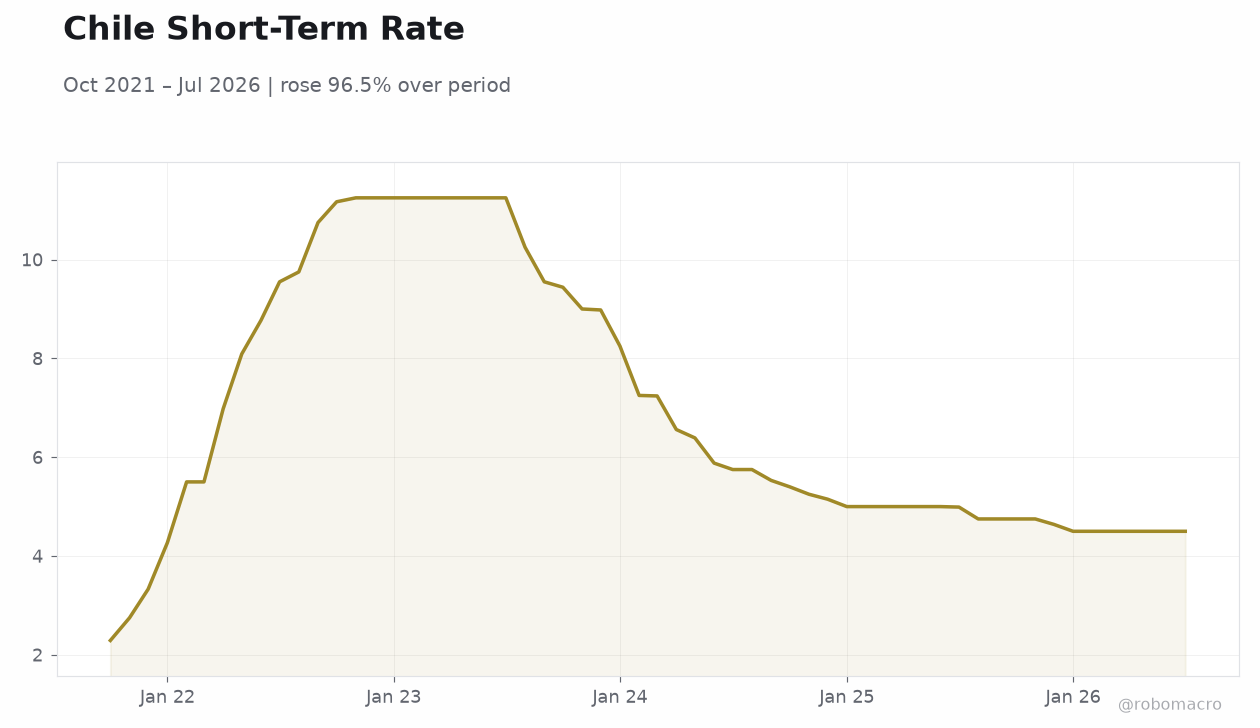 Chile Short-Term Rate | Type: macro_line | Rate %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Regional currencies sold off sharply, with USD/PEN surging 3.33% to 3.39 and USD/COP rising 1.94% to 3,271.13.
- MSCI Chile fell 2.08% to 39.58 while Colombia 10Y yields climbed 16 bp to 12.91%.
- Copper rose 1.24% to 6.76 and Brent gained 1.70% to 104.83, offering support to Chile and Peru fiscal balances.
Yesterday's Recap
Equity markets across the Andean bloc closed mixed to lower on September 23. MSCI Chile posted the steepest decline, falling 2.08% to 39.58, while MSCI Peru eased 0.21% to 91.57 and MSCI Colombia held steady at 9.02. Currencies came under broad pressure against the dollar, with USD/PEN jumping 3.33% to 3.39, USD/COP advancing 1.94% to 3,271.13, and USD/CLP rising 1.68% to 962.70.
Commodity prices provided partial offset for exporters, as copper climbed 1.24% to 6.76 and Brent crude gained 1.70% to 104.83, though gold slipped 0.65% to 4,290.50. Sovereign yields diverged, with Colombia’s 10-year yield rising 16 bp to 12.91% while Peru’s 10-year yield eased 5 bp to 6.54%. No macroeconomic data releases occurred in Colombia, Chile, or Peru.
Market moves reflected external USD strength rather than domestic catalysts.
The Day Ahead
No economic releases, central-bank meetings, or sovereign auctions are scheduled for Colombia, Chile, or Peru on September 24-25. Traders will monitor external drivers including copper and oil price momentum for signals on export revenues and fiscal accounts. Chile and Peru remain sensitive to further copper gains that could bolster royalty collections and current-account balances.
Colombia’s oil-linked fiscal position may benefit from sustained Brent levels above 100. Market participants will also track any spillover from global USD moves into COP, CLP, and PEN. Absent domestic data, pricing is expected to remain driven by commodity and external risk sentiment.
Other Economic Notes
Copper’s advance supports fiscal and external accounts in Chile and Peru, where mining royalties and export receipts form a large share of revenues. Brent’s gain offers modest relief to Colombia’s oil-dependent budget, though persistent high 10-year yields at 12.91% signal ongoing investor caution on fiscal sustainability. Peru’s lower 10-year yield at 6.54% reflects comparatively stable macro fundamentals and lower inflation pressures.
Regional equity underperformance, led by Chile, highlights sensitivity to global risk sentiment and commodity volatility. No new lithium or mining production data emerged to alter the medium-term outlook for Chile’s export basket.