Andeans Macro Daily(Beta Mode)
Colombia Cuts Ties With Iran as FX Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
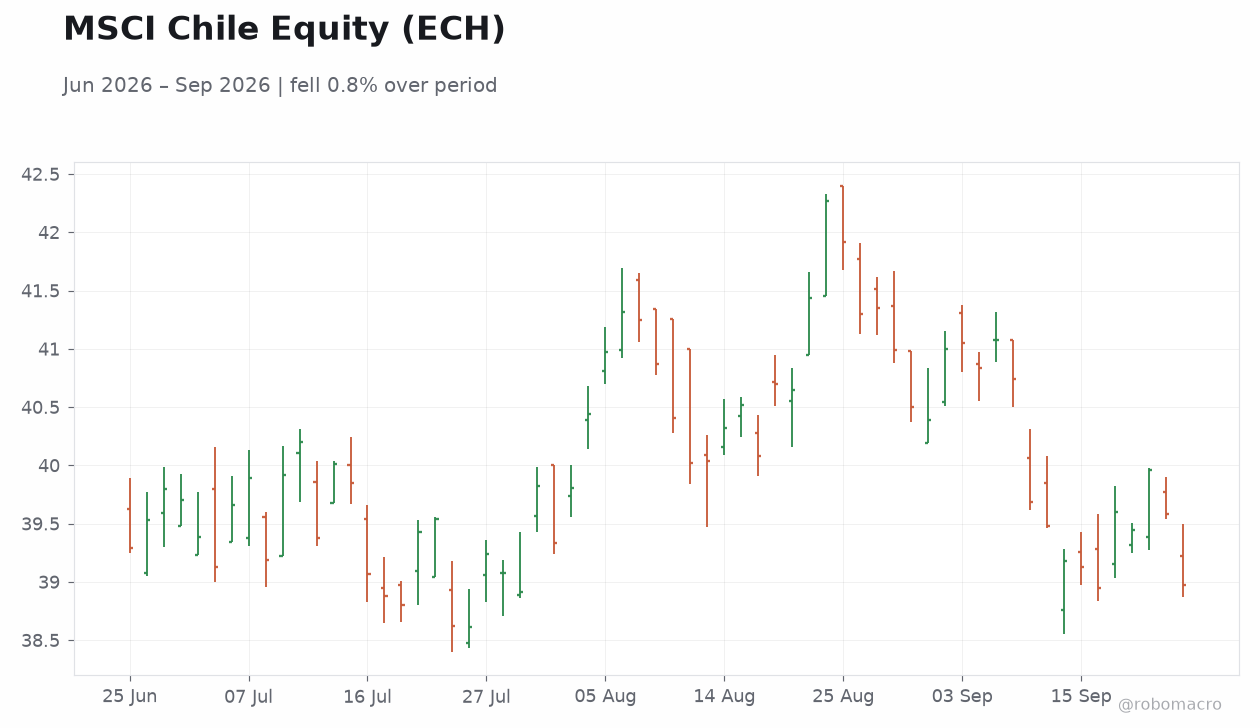
| MSCI Chile | 38.97 | -1.54% |
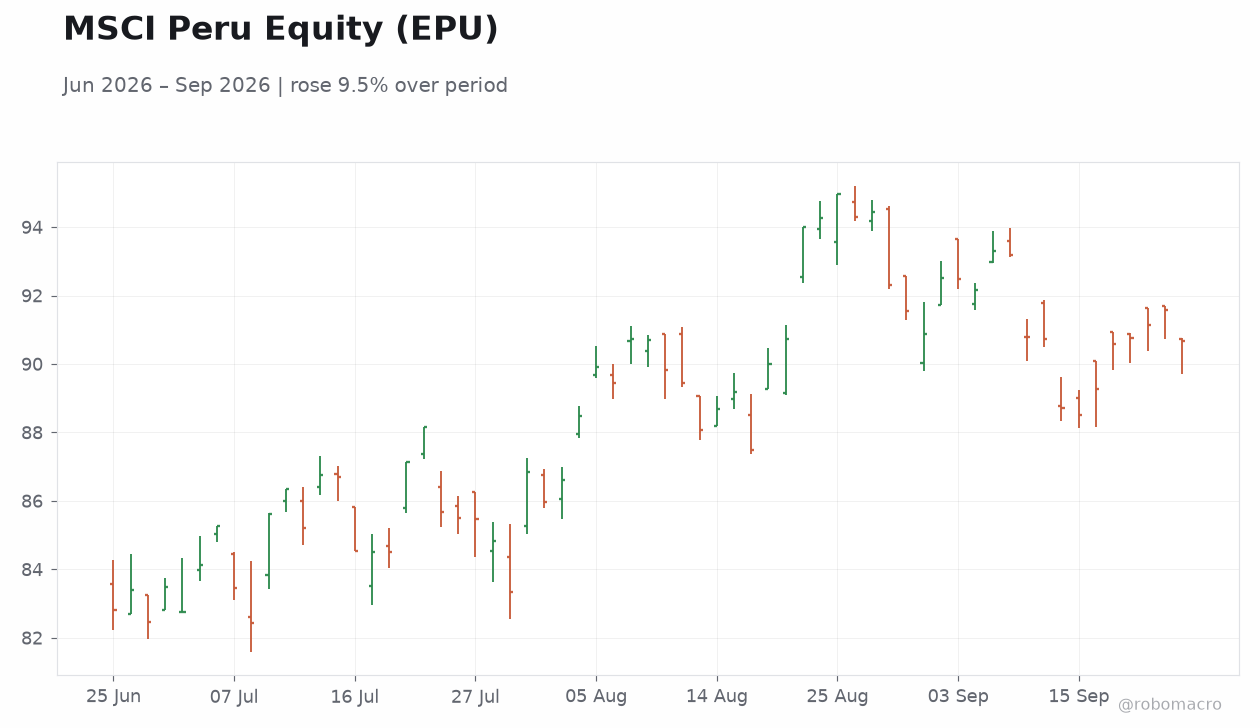
| MSCI Peru | 90.68 | -0.97% |
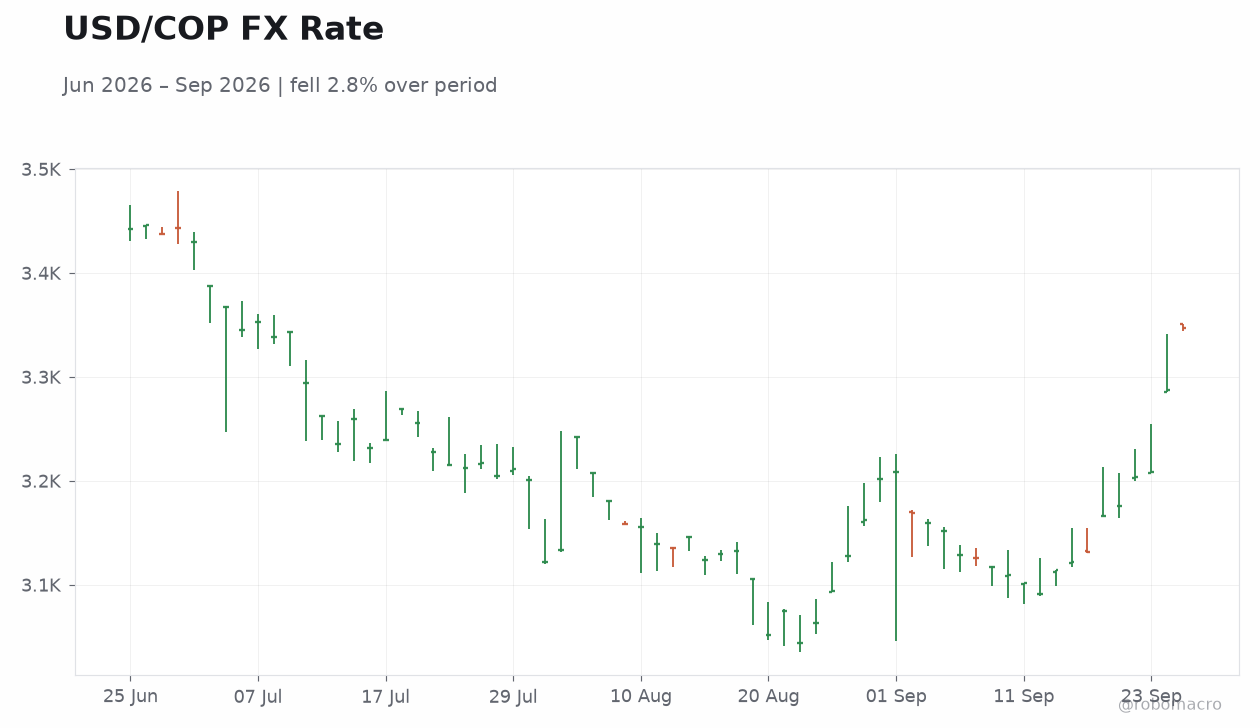
| USD/COP | 3,347.34 | +1.83% |
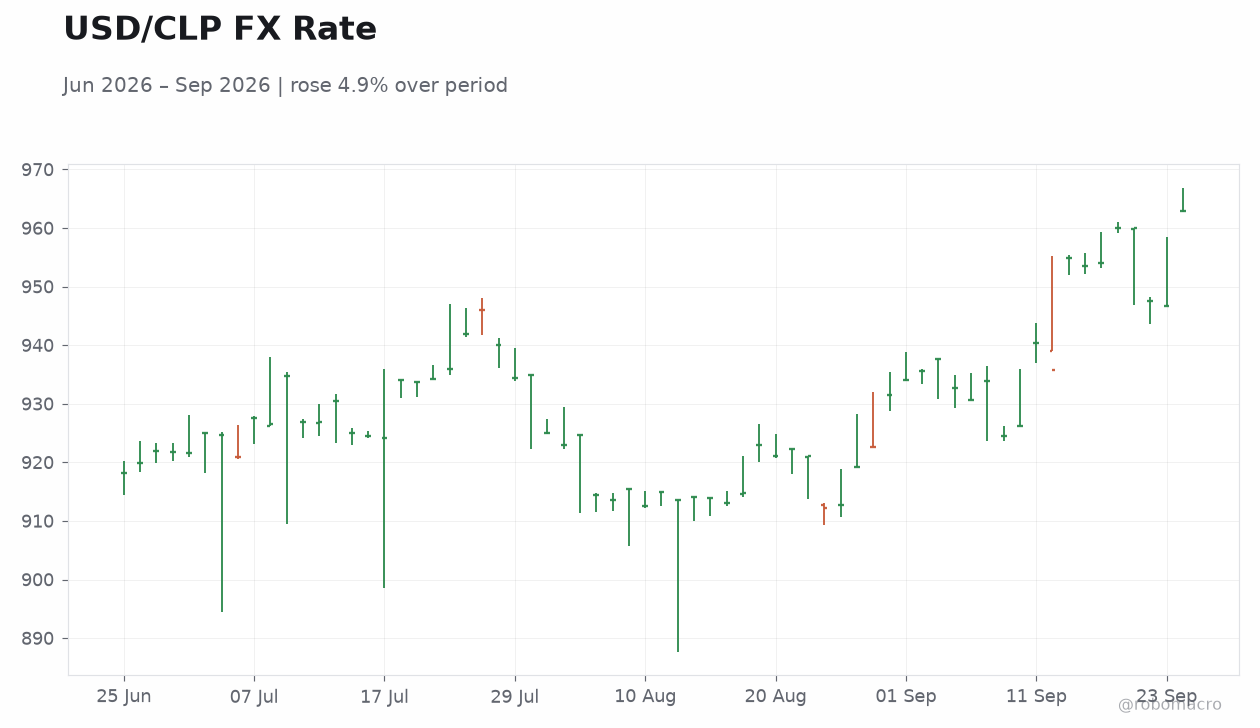
| USD/CLP | 962.83 | +1.70% |
| USD/PEN | 3.39 | +0.52% |
| Copper | 6.79 | +1.09% |
| Gold | 4,350.90 | +1.23% |
| Brent Crude | 98.59 | -7.51% |
| Bitcoin | 85,095.10 | +0.85% |
| Colombia 10Y Govt Yield | 12.91% | +16 bp |
| Peru 10Y Govt Yield | 6.52% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
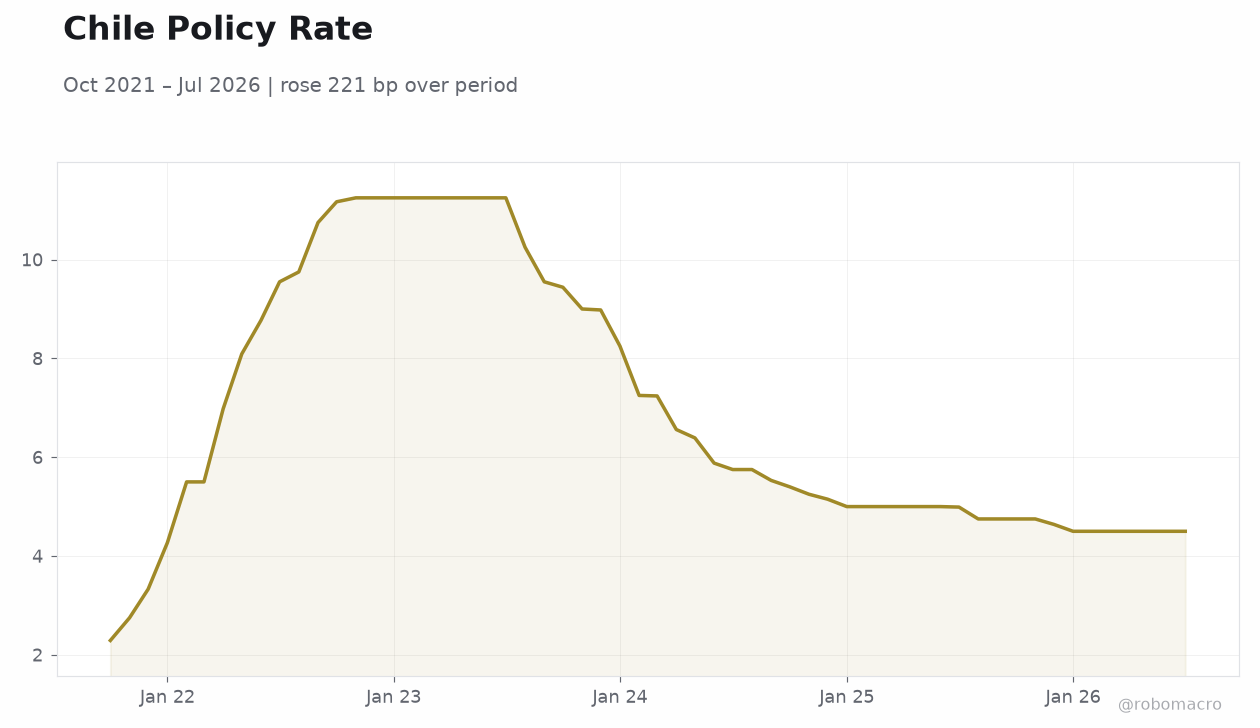 Chile Policy Rate | Type: macro_line | Percent: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Colombia severs diplomatic ties with Iran on national-security grounds, driving USD/COP up 1.83% to 3,347.34.
- MSCI Chile falls 1.54% and MSCI Peru declines 0.97% amid broad USD strength, while copper rises 1.09% to 6.79.
- Colombia 10-year yield widens 16 bp to 12.91% and Peru 10-year yield tightens 7 bp to 6.52% as Brent crude drops 7.51%.
Yesterday's Recap
Equity markets in Chile and Peru posted losses as MSCI Chile fell 1.54% to 38.97 and MSCI Peru declined 0.97% to 90.68, while MSCI Colombia held steady at 9.02. Currencies across the Andean bloc weakened against the dollar, with USD/COP rising 1.83% to 3,347.34, USD/CLP advancing 1.70% to 962.83, and USD/PEN increasing 0.52% to 3.39. Colombia announced the formal severance of diplomatic relations with Iran, effective Saturday, citing national-security concerns.
Copper gained 1.09% to 6.79 and gold advanced 1.23% to 4,350.90, providing support to mining-linked revenues in Chile and Peru. Brent crude plunged 7.51% to 98.59, weighing on Colombia’s oil-linked fiscal and external accounts. Colombia’s 10-year government yield rose 16 bp to 12.91%, while Peru’s 10-year yield eased 7 bp to 6.52%.
Chile announced plans to issue its first Swiss-franc bond, marking a return to international debt markets for the third time this year.
The Day Ahead
No macroeconomic releases, central-bank meetings, or sovereign auctions are scheduled for 25–26 September across Colombia, Chile, or Peru. Market participants will monitor ongoing reactions to Colombia’s diplomatic break with Iran and any follow-through on Chile’s Swiss-franc issuance. Copper and gold price movements remain key for Chile and Peru fiscal and current-account outlooks.
Brent crude volatility will continue to influence Colombia’s external balances. Regional FX will stay sensitive to broader dollar strength and any shifts in Fed expectations.
Other Economic Notes
Elevated oil prices and hawkish Fed bets continue to pressure regional currencies, with carry-trade differentials narrowing in favor of the dollar. Chile’s planned Swiss-franc bond sale diversifies funding sources and may ease domestic yield pressures amid stable copper revenues. Peru’s mining sector sees renewed drilling activity at the Condestable copper project, supporting long-term export prospects.
Colombia’s diplomatic move introduces a new political-risk factor that could affect investor sentiment toward local assets. Commodity price divergence—copper and gold higher, Brent sharply lower—creates uneven fiscal impacts across the three economies.