Andeans Macro Daily(Beta Mode)
BanRep Holds at 12% as Fiscal Deficit Widens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
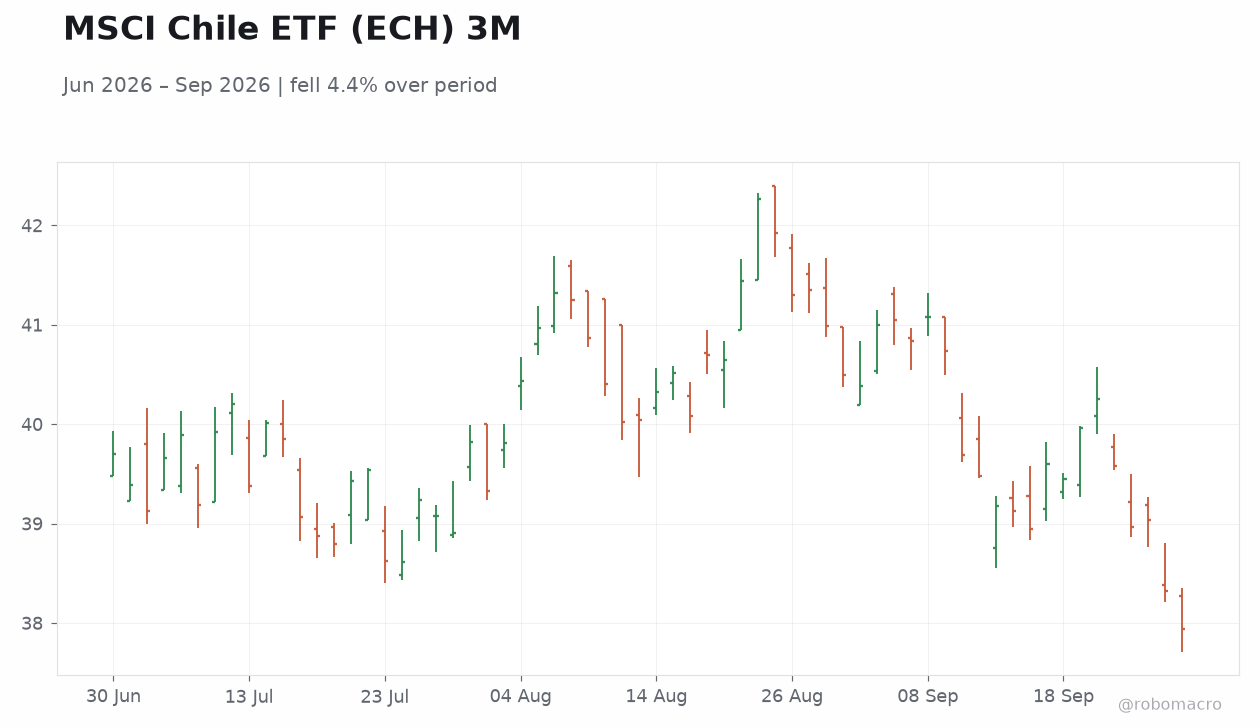
| MSCI Chile | 37.94 | -0.99% |
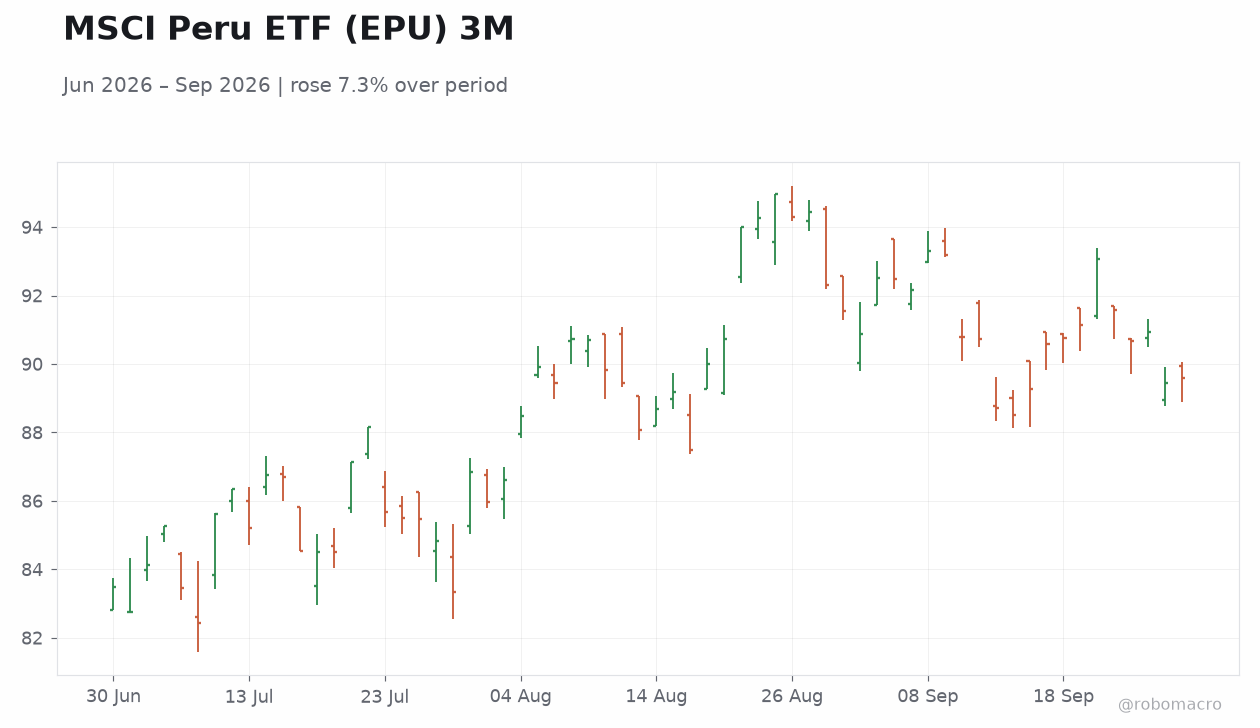
| MSCI Peru | 89.59 | +0.17% |
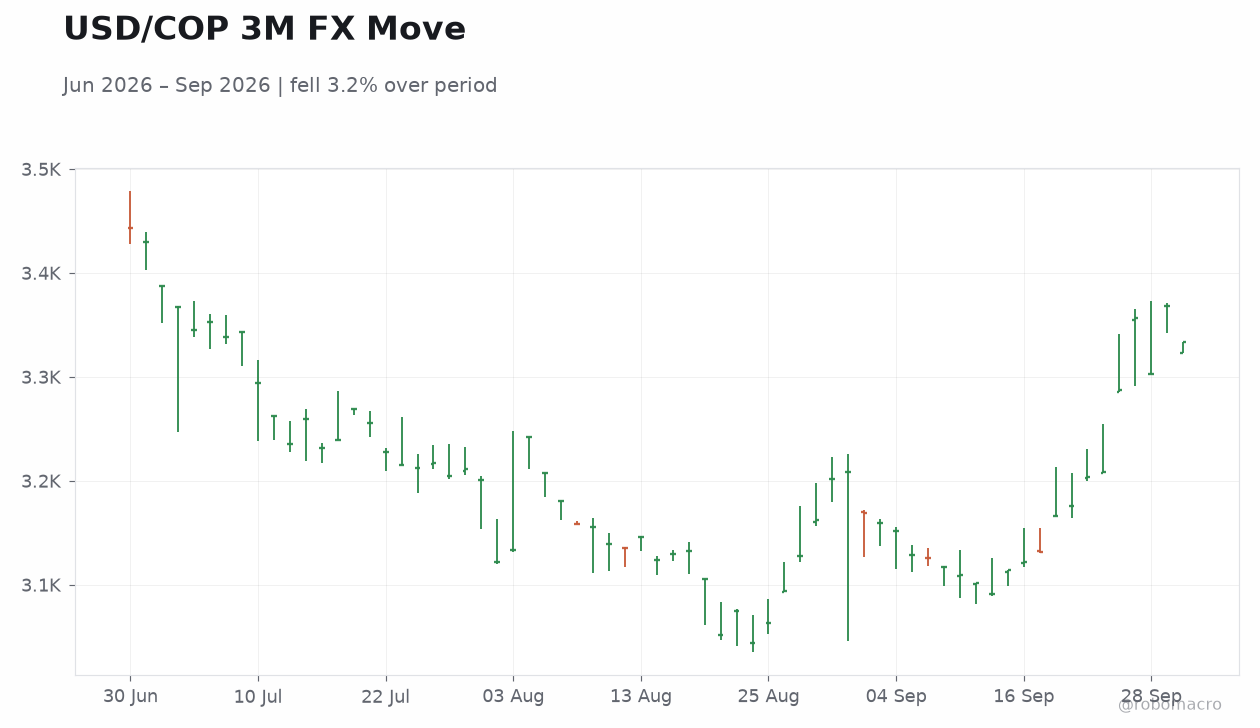
| USD/COP | 3,333.33 | -1.05% |
| USD/CLP | 973.25 | +0.62% |
| USD/PEN | 3.44 | +0.10% |
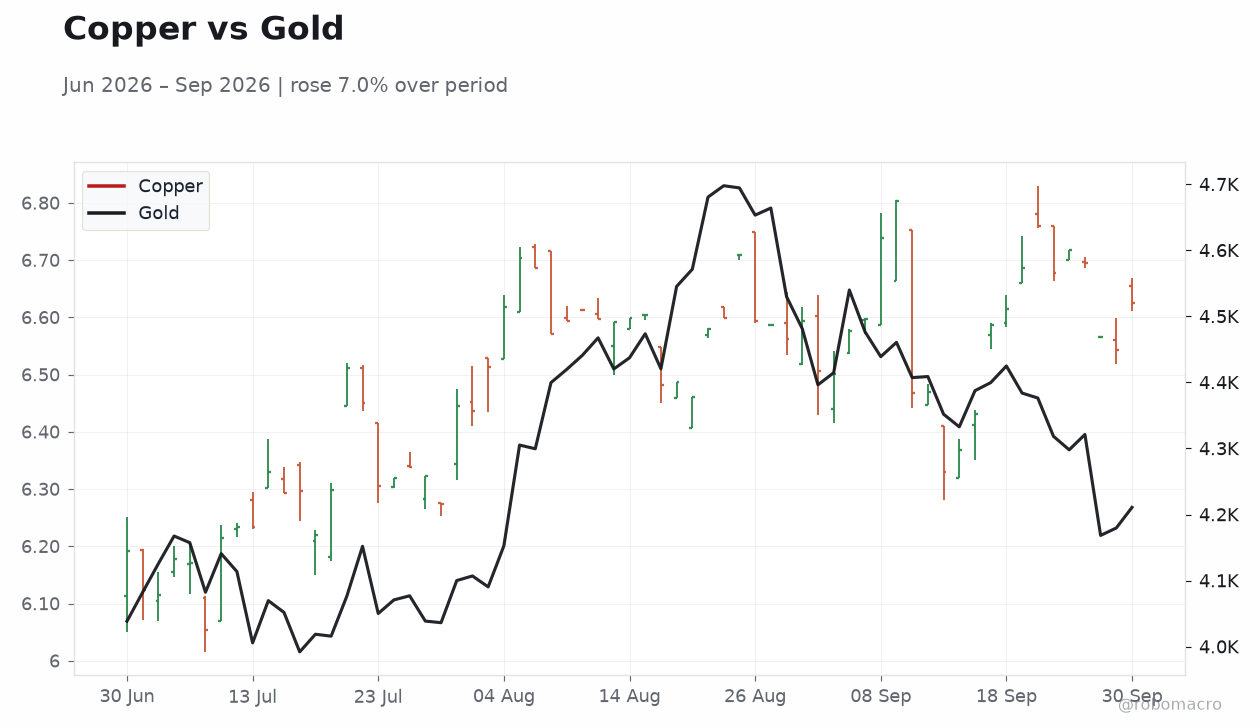
| Copper | 6.63 | +1.28% |
| Gold | 4,210.50 | +0.74% |
| Brent Crude | 97.65 | -4.82% |
| Bitcoin | 83,712.62 | +0.11% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | 6.67% | +15 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
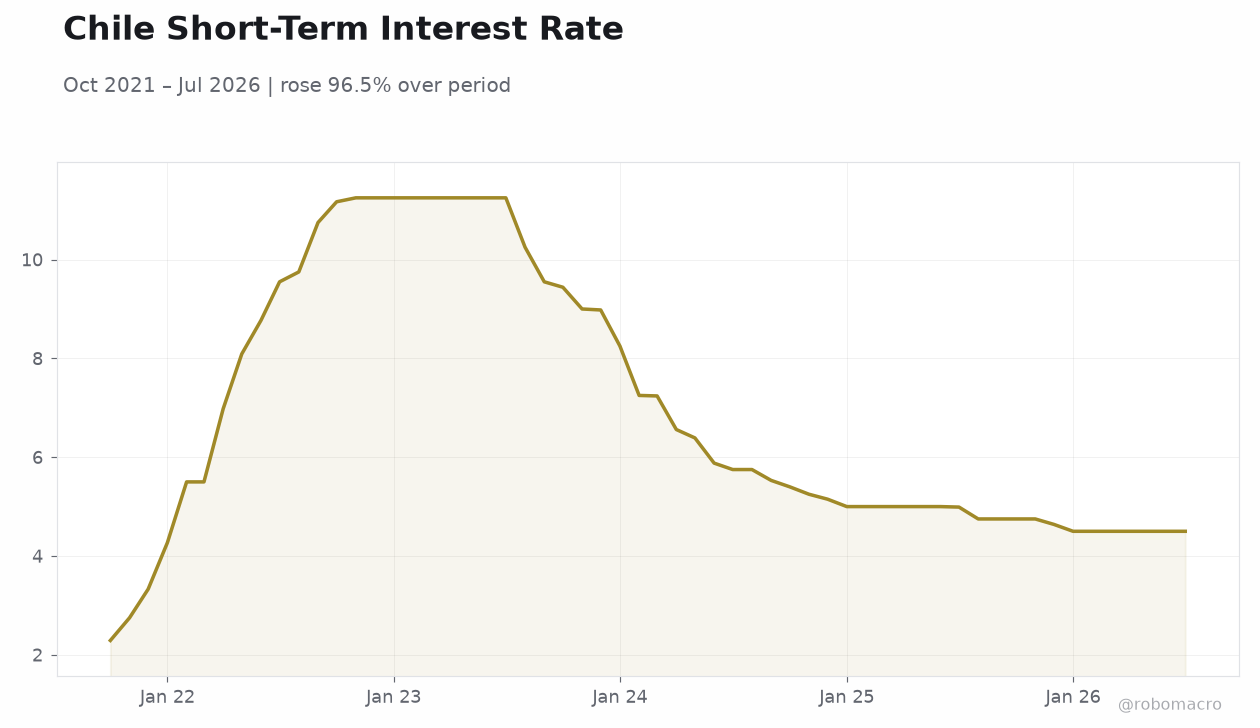 Chile Short-Term Interest Rate | Type: macro_line | Rate %: 4.5 (2026-07-01) | Range: 2.29–11.25 | Trend(5pt): 2.29,11.25,7.25,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 12 | 12 | 10:00 |
- BanRep set to hold rates at 12% amid persistent inflation pressures
- Colombia fiscal talks with IMF intensify after deficit expansion
- Copper rally bolsters Chile and Peru export revenues while Brent slump hits Colombia
Yesterday's Recap
Equity markets showed mixed performance across the Andean bloc on September 29. MSCI Chile declined 0.99% to 37.94 while MSCI Peru advanced 0.17% to 89.59 and MSCI Colombia closed flat at 9.02. FX moves diverged with USD/COP falling 1.05% to 3,333.33, USD/CLP rising 0.62% to 973.25, and USD/PEN gaining 0.10% to 3.44.
Peru’s 10-year government yield increased 15 bp to 6.67%. No macroeconomic data releases occurred in Colombia, Chile, or Peru. News flow centered on Colombia’s widening fiscal deficit prompting IMF discussions and expectations that September inflation could reach a 3.5-year high of 7.4% driven by food, peso, and oil pressures.
Copper rose 1.28% to 6.63, supporting mining revenues in Chile and Peru, while Brent crude dropped 4.82% to 97.65, pressuring Colombia’s fiscal and current-account balances. Gold advanced 0.74% to 4,210.50, offering modest export support to Peru and Colombia.
The Day Ahead
Colombia’s central bank will announce its interest-rate decision at 10:00 ET with consensus pointing to a hold at the current 12% level. No data releases, auctions, or mining announcements are scheduled for Chile or Peru. Market participants will monitor the BanRep statement for signals on whether the committee views the current stance as sufficiently restrictive given rising inflation expectations.
Copper and gold price movements will remain key for Chile and Peru fiscal outlooks while Brent weakness continues to weigh on Colombia’s oil-dependent revenues. Tomorrow’s calendar remains empty of Andean events. The committee voted to hold.
Other Economic Notes
Colombia’s fiscal position has deteriorated, triggering formal talks with the IMF that could shape near-term policy credibility. Persistent inflation pressures, potentially reaching 7.4% in September, complicate the outlook for monetary easing and may force BanRep to consider additional hikes later in the year. Commodity price volatility directly affects fiscal balances, with higher copper supporting Chile and Peru while lower Brent crude reduces Colombia’s export and royalty income.
Lithium developments in Chile continue to offer long-term revenue potential but have not yet altered near-term macro dynamics. Political and reform risks remain elevated across the region and could influence FX and sovereign spreads. Eurozone CPI at 3.20% and unemployment at 6.40% provide limited direct read-through for Andean policy.