Andeans Macro Daily(Beta Mode)
BanRep Hikes to 12.25%, CLP and PEN Weaken
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
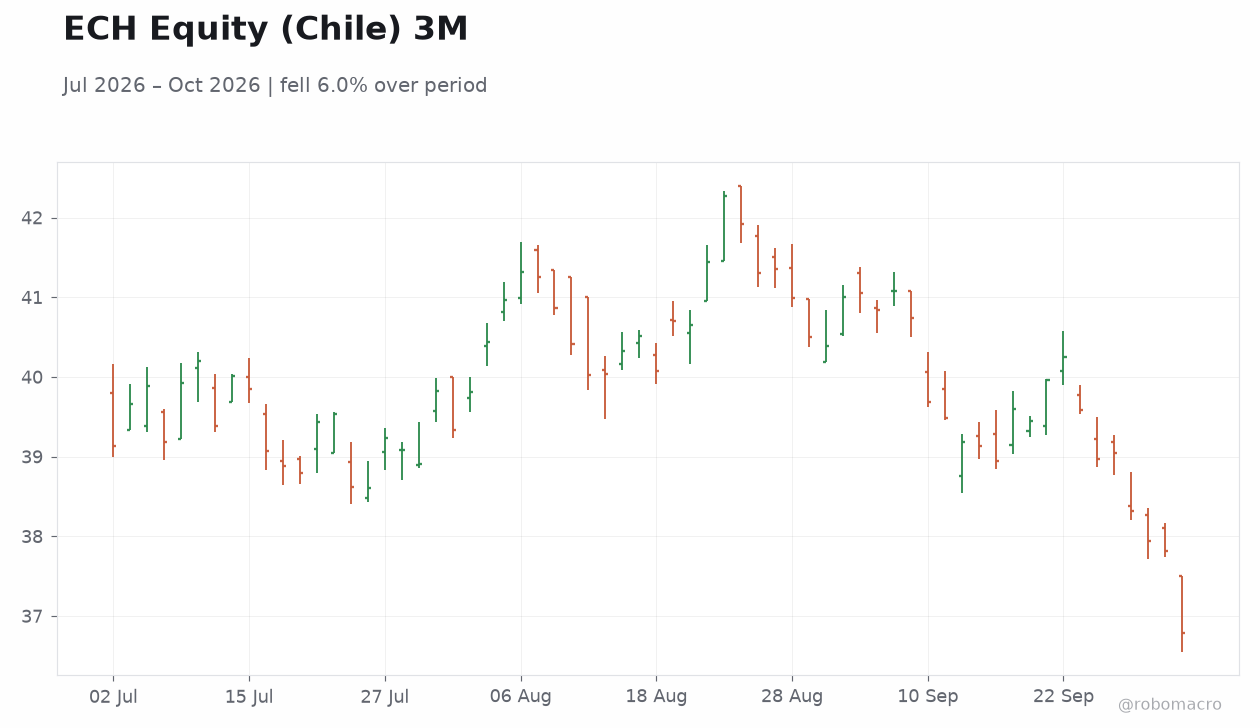
| MSCI Chile | 36.79 | -2.70% |
| MSCI Peru | 88.75 | +0.02% |
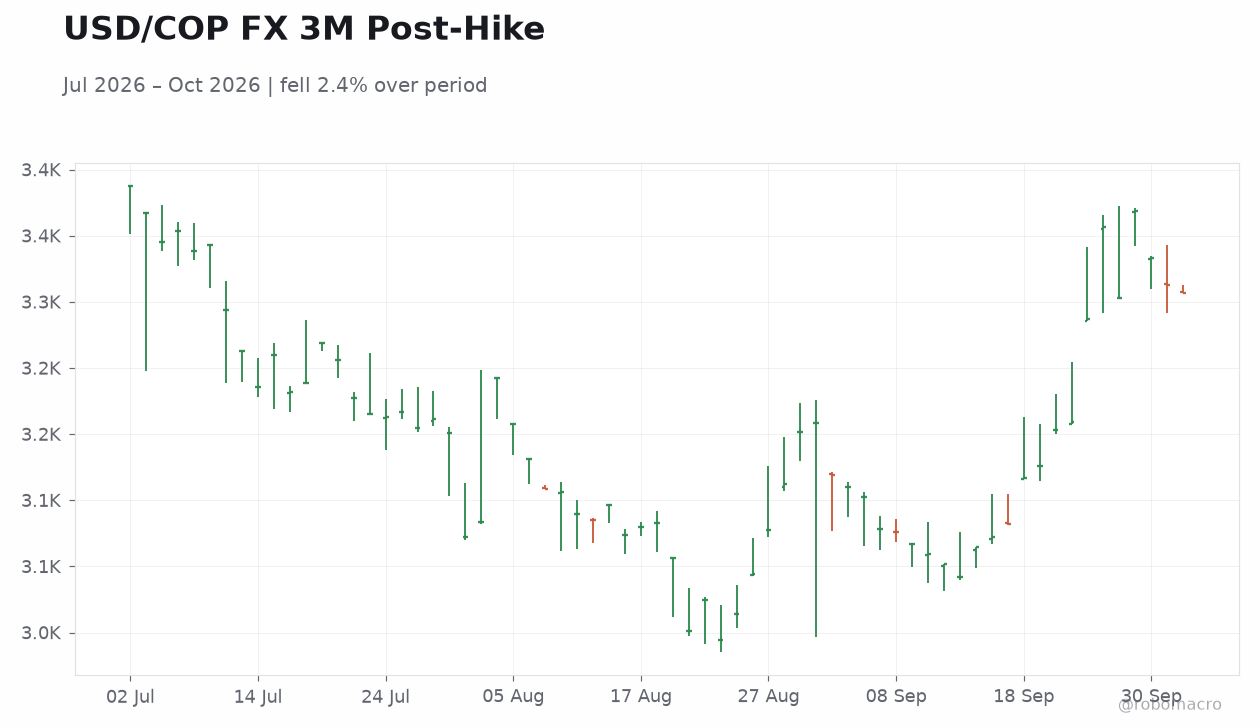
| USD/COP | 3,306.99 | -0.18% |
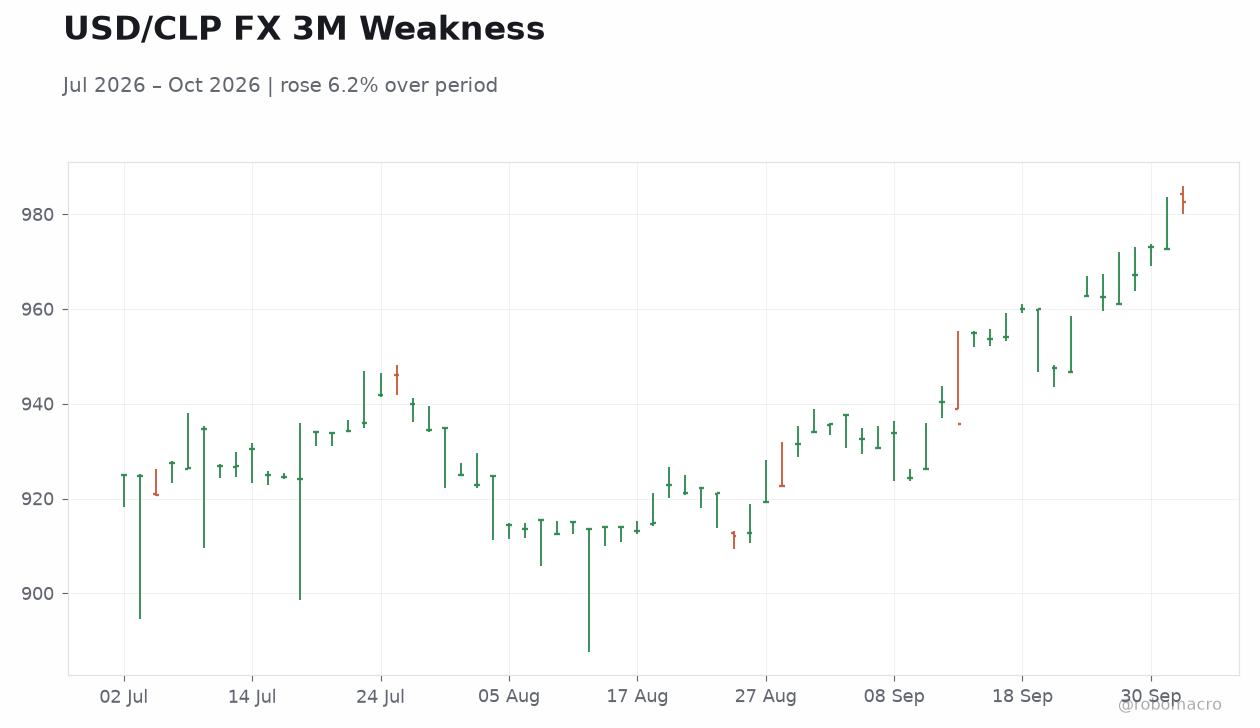
| USD/CLP | 982.30 | +0.99% |
| USD/PEN | 3.46 | +3.67% |
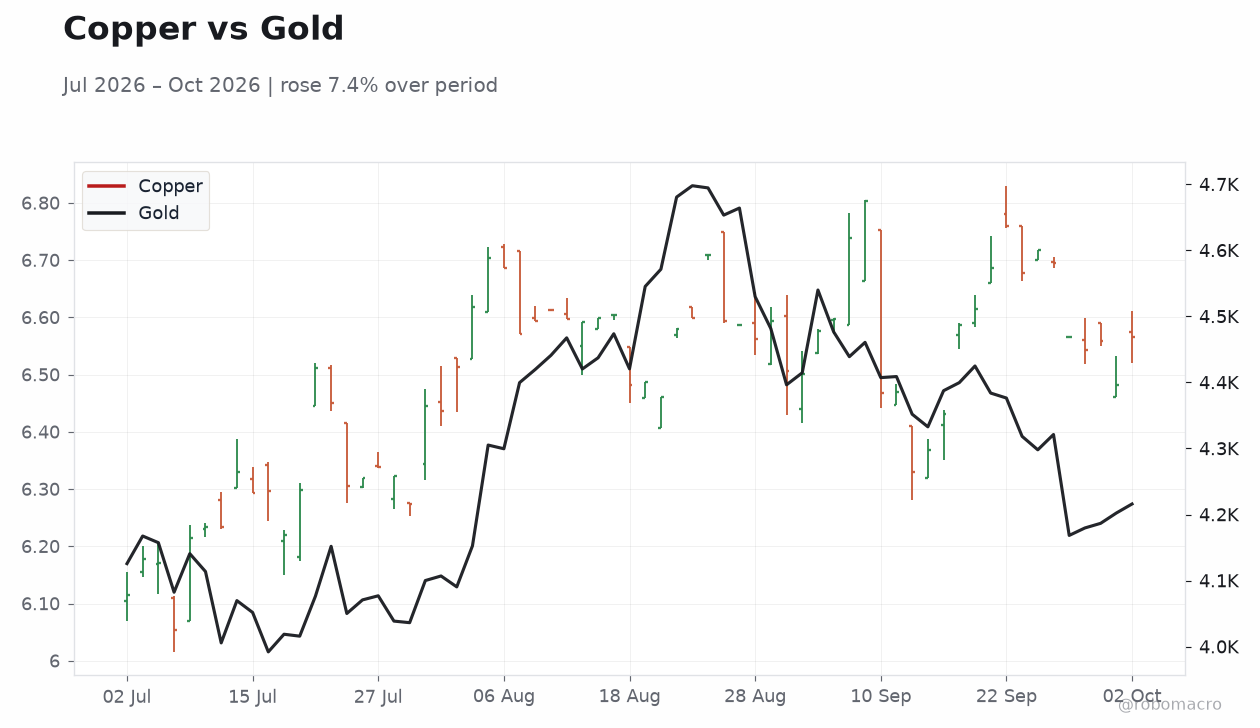
| Copper | 6.57 | +1.30% |
| Gold | 4,217.20 | +0.35% |
| Brent Crude | 99.90 | -2.36% |
| Bitcoin | 86,486.55 | +1.93% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Central Bank Interest Rate Decision | 12 | 12 | 12.25 |
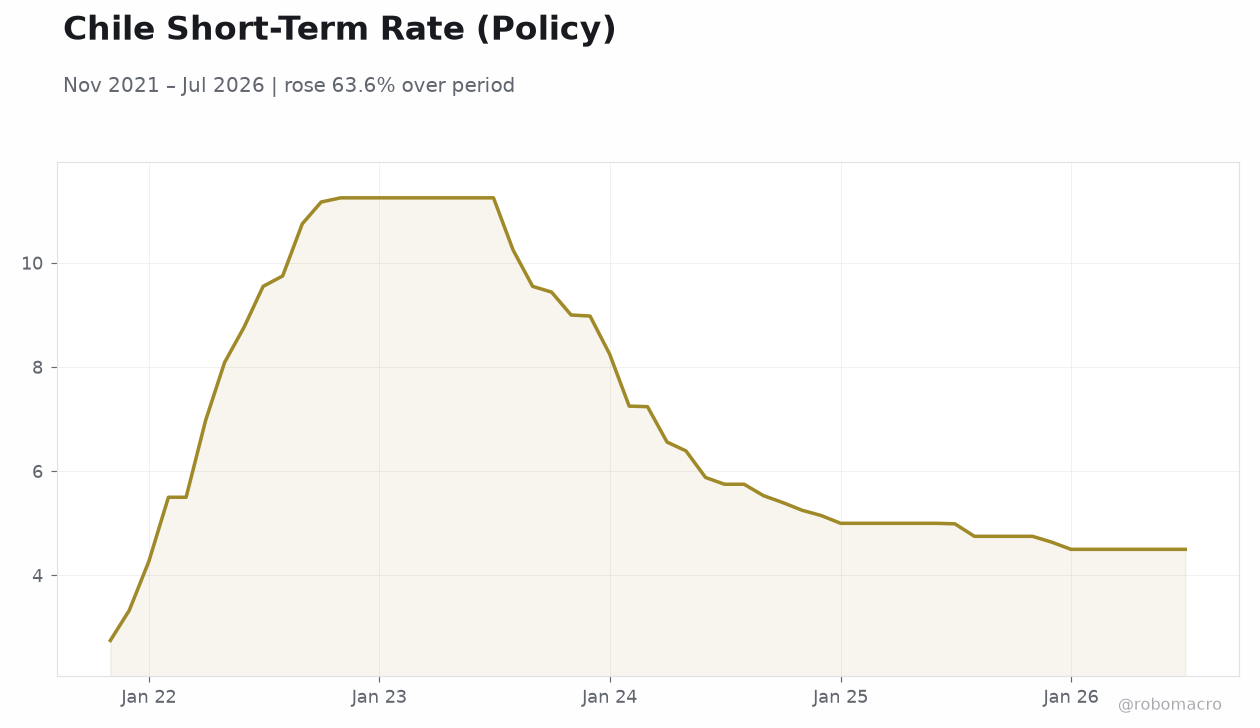 Chile Short-Term Rate (Policy) | Type: macro_line | Policy Rate %: 4.5 (2026-07-01) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,7.24,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BanRep raises policy rate 25 bp to 12.25%, surprising markets
- MSCI Chile falls 2.70% as USD/CLP climbs 0.99%
- Copper rises 1.30% while USD/PEN jumps 3.67%
Yesterday's Recap
Colombia’s central bank delivered the region’s sole high-impact release by lifting its policy rate to 12.25% from 12.00%, exceeding the 12.00% consensus. The move triggered limited immediate reaction in USD/COP, which eased 0.18% to 3,306.99, while MSCI Colombia held steady at 9.02. In Chile, equities bore the brunt of the session as MSCI Chile declined 2.70% to 36.79 and USD/CLP advanced 0.99% to 982.30.
Peru recorded the sharpest currency move, with USD/PEN surging 3.67% to 3.46 even as MSCI Peru edged 0.02% higher to 88.75. Copper’s 1.30% gain to 6.57 offered some offset for Chilean and Peruvian fiscal balances, while Brent crude’s 2.36% drop to 99.90 weighed on Colombia’s oil-linked revenues. Gold advanced modestly 0.35% to 4,217.20, providing marginal support to Peru and Colombia.
No CPI, GDP or trade data emerged from Chile or Peru. Protests against a copper mine in Jerico continue to highlight local opposition to new projects.
The Day Ahead
No macroeconomic releases, central-bank meetings or bond auctions are scheduled for Colombia, Chile or Peru on October 2 or 3. Market participants will therefore focus on external drivers, including copper and oil price swings that directly affect fiscal and current-account balances in Chile, Peru and Colombia. USD strength visible in CLP and PEN moves may keep local volatility elevated absent fresh domestic data.
Mining-sector developments in Colombia remain in focus following ongoing protests against copper projects. Lithium policy updates from Chile could also surface and influence longer-term investment flows. Traders will monitor any follow-up comments from BanRep officials for signals on the durability of the recent tightening.
Other Economic Notes
Copper’s advance supports export receipts and royalty income in Chile and Peru, though production volumes were not updated. Brent’s decline widens Colombia’s fiscal gap and may pressure sovereign spreads if oil prices remain soft. Political opposition to mining in Colombia, highlighted by protests in Jerico, adds downside risk to foreign direct investment in the copper sector.
Lithium remains an emerging theme for Chile’s medium-term growth outlook, yet no new policy announcements appeared. Broader commodity strength continues to underpin Andean external accounts despite the absence of fresh volume data.