Andeans Macro Daily(Beta Mode)
Chile Stocks Slip as CLP Weakens on Oil Surge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
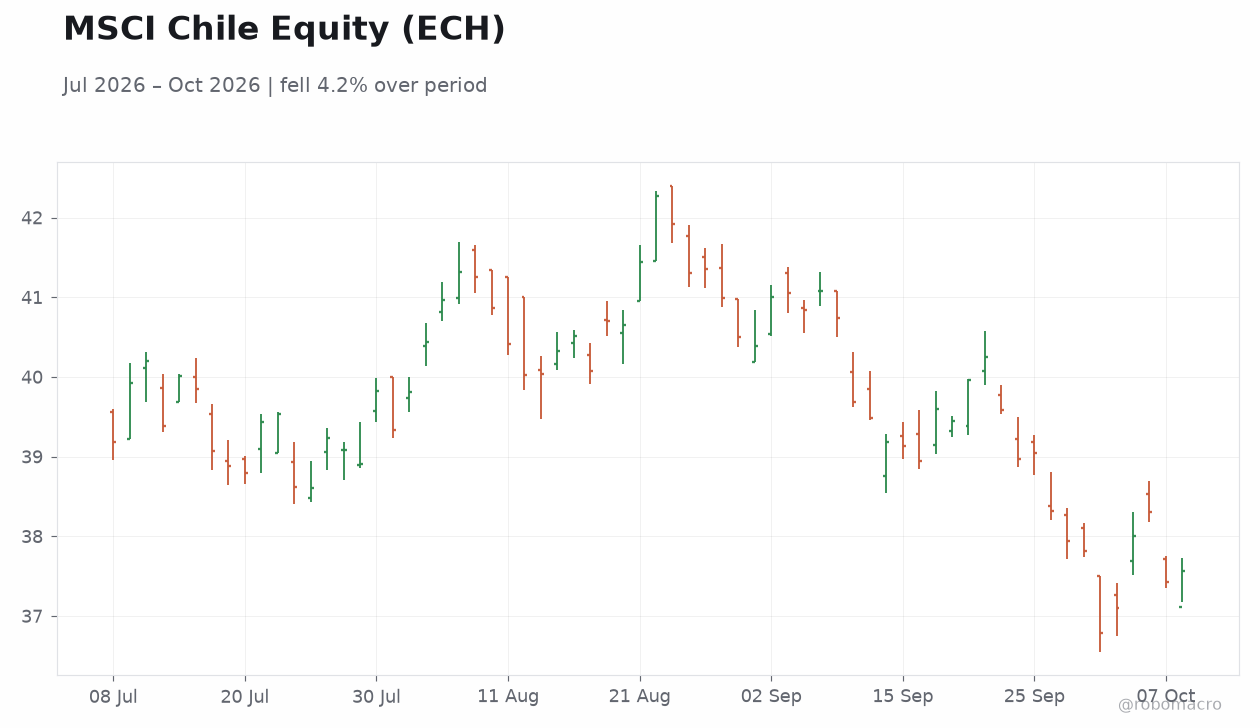
| MSCI Chile | 37.11 | -0.85% |
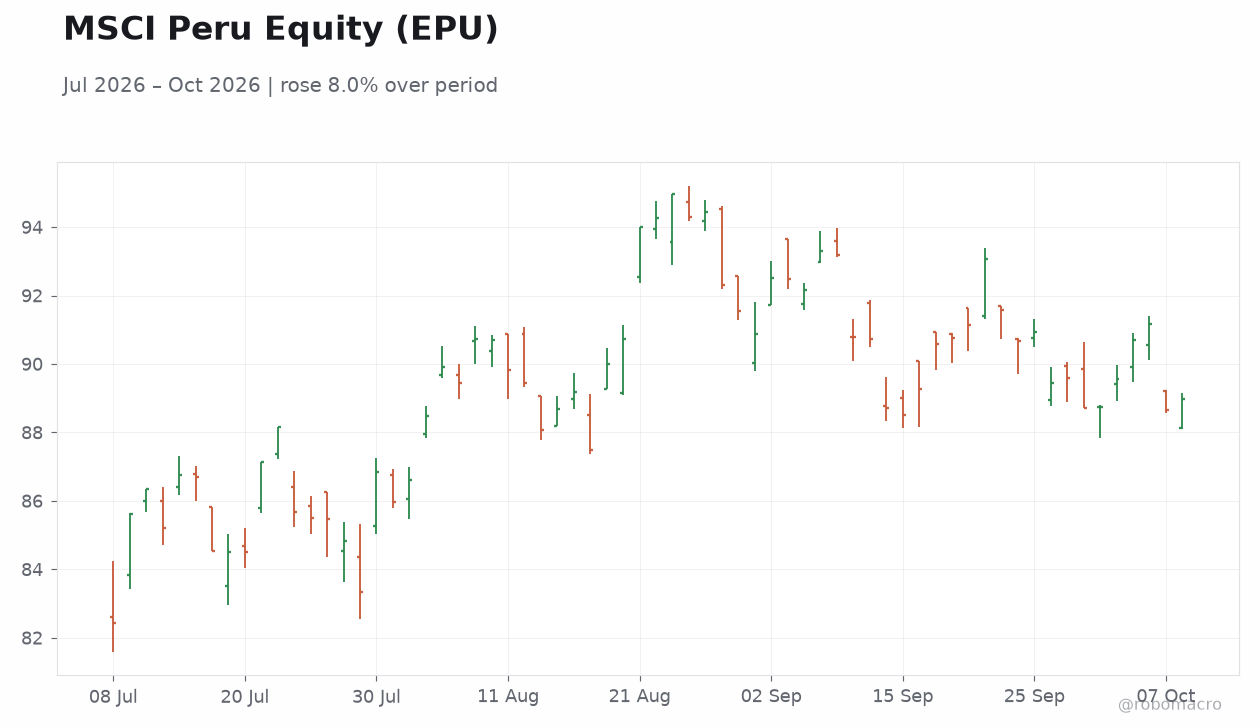
| MSCI Peru | 88.39 | -0.30% |
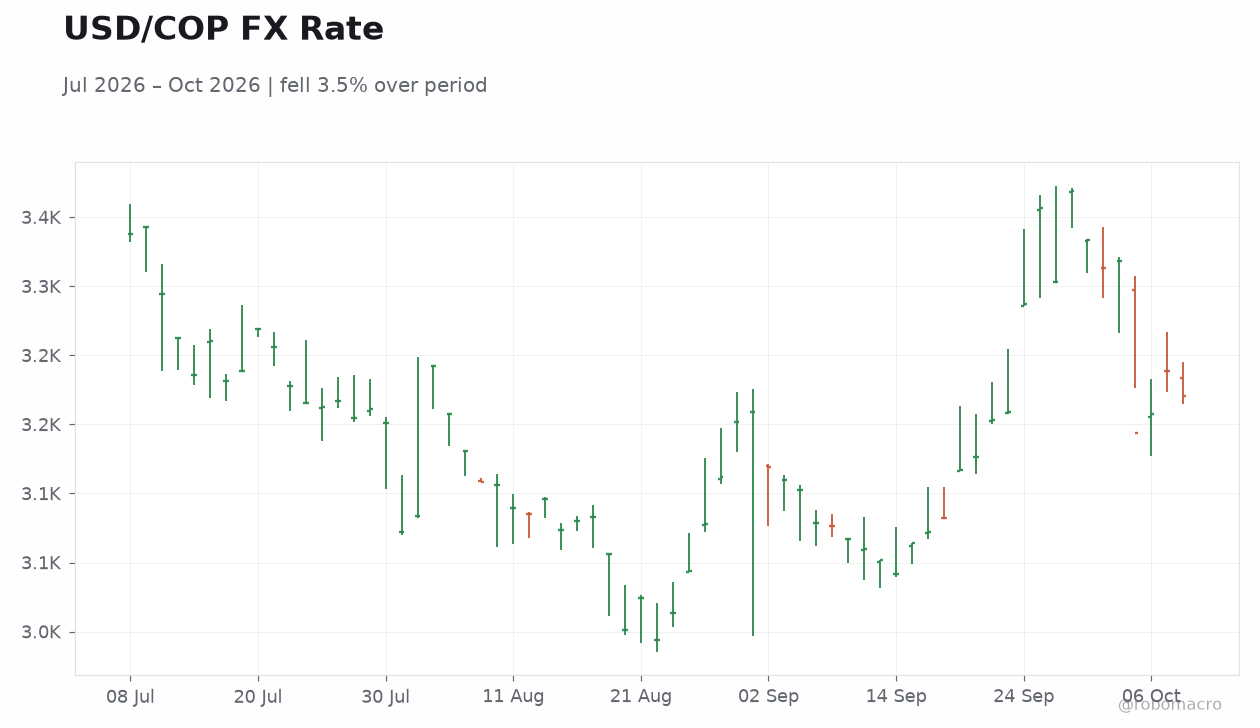
| USD/COP | 3,223.14 | -0.49% |
| USD/CLP | 980.04 | +0.73% |
| USD/PEN | 3.44 | -0.14% |
| Copper | 6.62 | +0.31% |
| Gold | 4,150.60 | +0.24% |
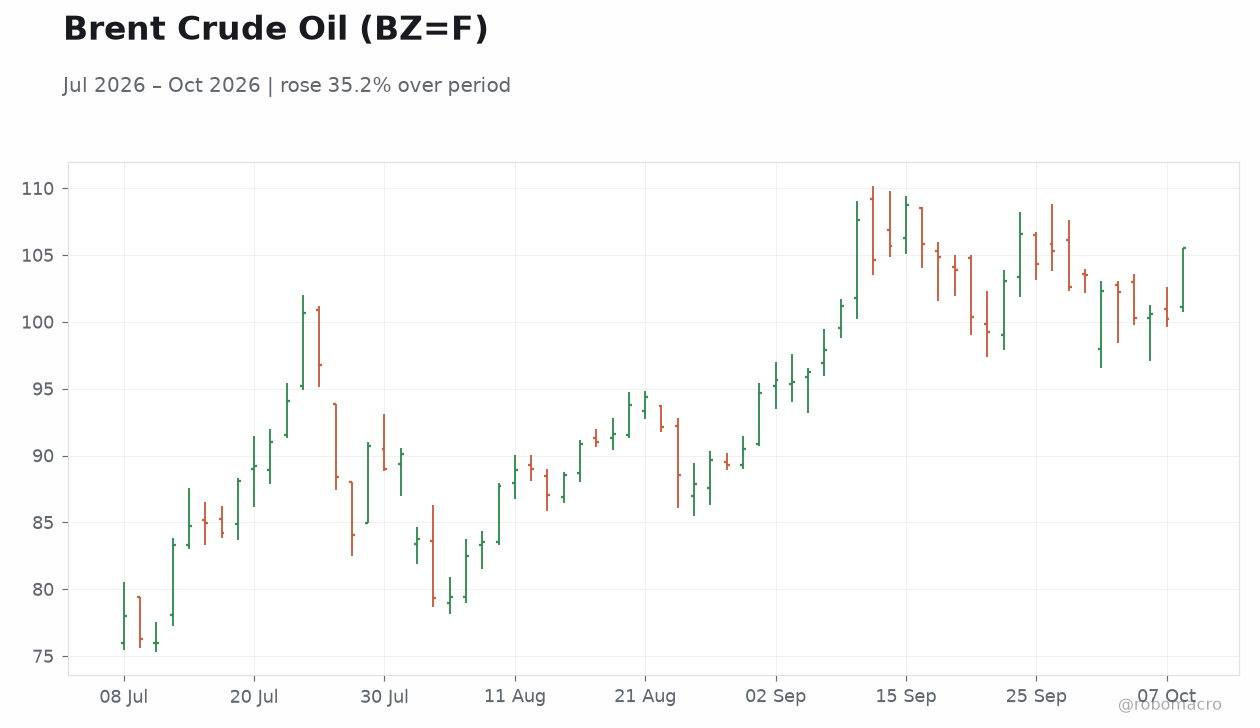
| Brent Crude | 105.39 | +5.18% |
| Bitcoin | 82,523.05 | -0.90% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
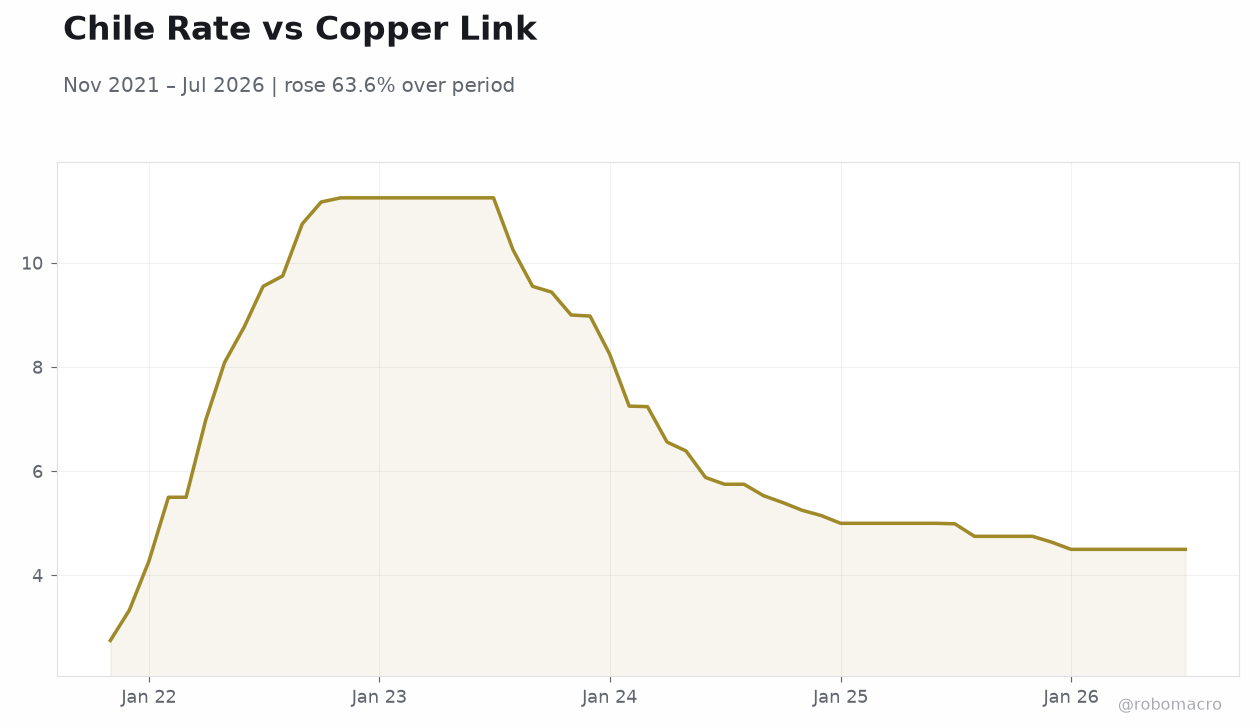 Chile Rate vs Copper Link | Type: macro_line | Chile Rate %: 4.5 (2026-07-01) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,7.24,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- MSCI Chile drops 0.85% while CLP weakens 0.73% against USD
- Brent crude surges 5.18% supporting Colombia’s COP strength
- Peru MSCI slips 0.30% as copper edges up only 0.31%
Yesterday's Recap
Chilean equities declined as the MSCI Chile index fell 0.85% to 37.11 amid broader commodity volatility. The CLP depreciated 0.73% to 980.04 per USD, reflecting pressure from higher Brent crude prices that jumped 5.18% to 105.39. In Colombia, the MSCI Colombia index held steady at 9.02 while the COP strengthened 0.49% to 3,223.14 per USD on firmer oil prices.
Peru’s MSCI index eased 0.30% to 88.39 with the PEN appreciating 0.14% to 3.44 per USD. Gold advanced 0.24% to 4,150.60, providing limited support to regional miners. Flooding along Chile’s Mapocho river prompted airlifts but did not disrupt broader market pricing.
Bitcoin fell 0.90% to 82,523.05, offering little offset to Andean equity weakness. Copper rose 0.31% to 6.62, giving modest backing to Peru’s export outlook without lifting equities materially.
The Day Ahead
Markets enter a data-light session with no scheduled Andean releases, leaving focus on commodity price action and external drivers. Copper at 6.62 and Brent near 105.39 will dictate sentiment for Chile and Peru exporters while oil remains key for Colombia. Regional FX pairs are expected to track global risk appetite and USD direction.
Equity flows into MSCI Chile and Peru proxies could stay subdued absent fresh catalysts. Any comments from central bank officials would likely center on inflation trajectories rather than immediate policy shifts. Investors will watch for follow-through moves in gold at 4,150.60 and any shifts in Bitcoin that could influence risk sentiment across emerging markets.
Other Economic Notes
The World Bank projects Colombia will outpace both Brazil and Mexico in 2026 growth, underscoring relative resilience in the Andean bloc. Chile’s lithium sector continues to draw attention as a structural growth driver alongside traditional copper output. Peru’s mining pipeline remains central to medium-term fiscal balances and export receipts.
Regional sovereign spreads have shown limited reaction to the latest commodity moves, suggesting investors view current price levels as supportive rather than disruptive. Fiscal discipline across the three economies continues to anchor credibility with external investors despite varying political backdrops. Steady external accounts in Colombia benefit directly from Brent strength while Chile and Peru rely more on copper stability.