Andeans Macro Daily(Beta Mode)
BCCh Holds at 4.50%, BanRep Decision Looms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
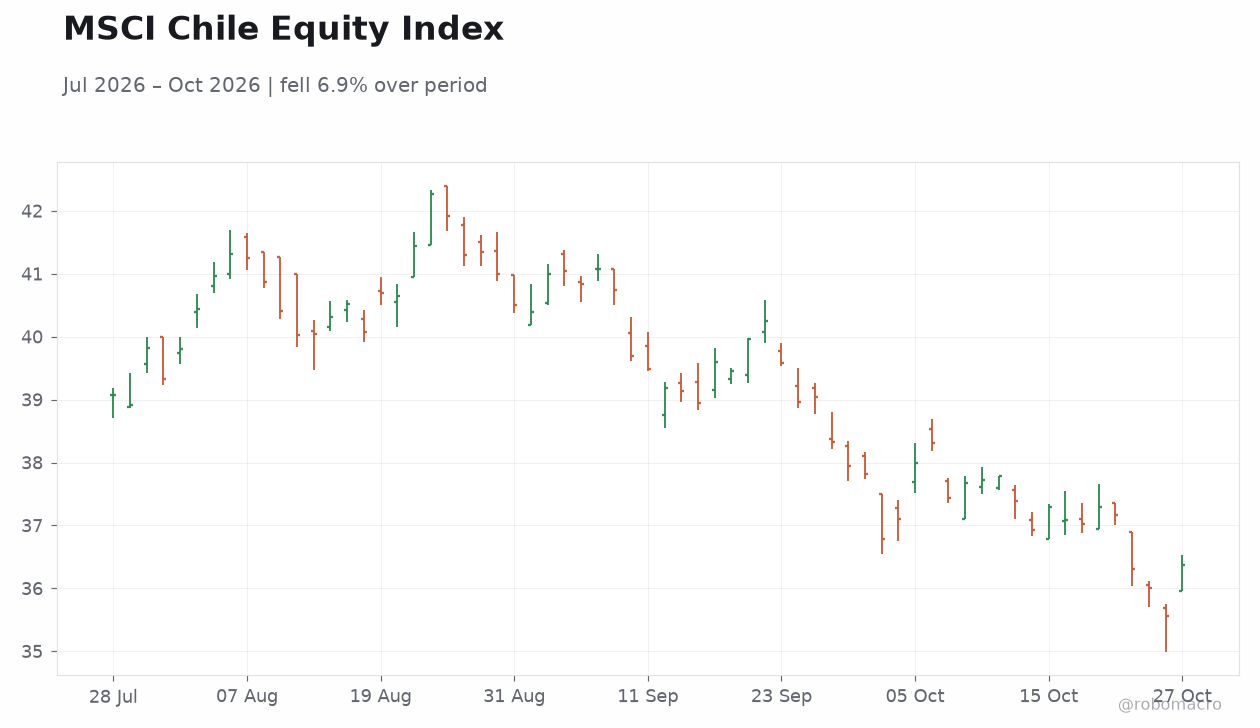
| MSCI Chile | 36.37 | +2.28% |
| MSCI Peru | 85.49 | +1.29% |
| USD/COP | 3,145.89 | -0.10% |
| USD/CLP | 977.90 | -1.17% |
| USD/PEN | 3.45 | +0.15% |
| Copper | 6.65 | +0.48% |
| Gold | 4,072.70 | -0.05% |
| Brent Crude | 111.28 | -2.28% |
| Bitcoin | 80,644.19 | -0.20% |
| Colombia 10Y Govt Yield | - | - |
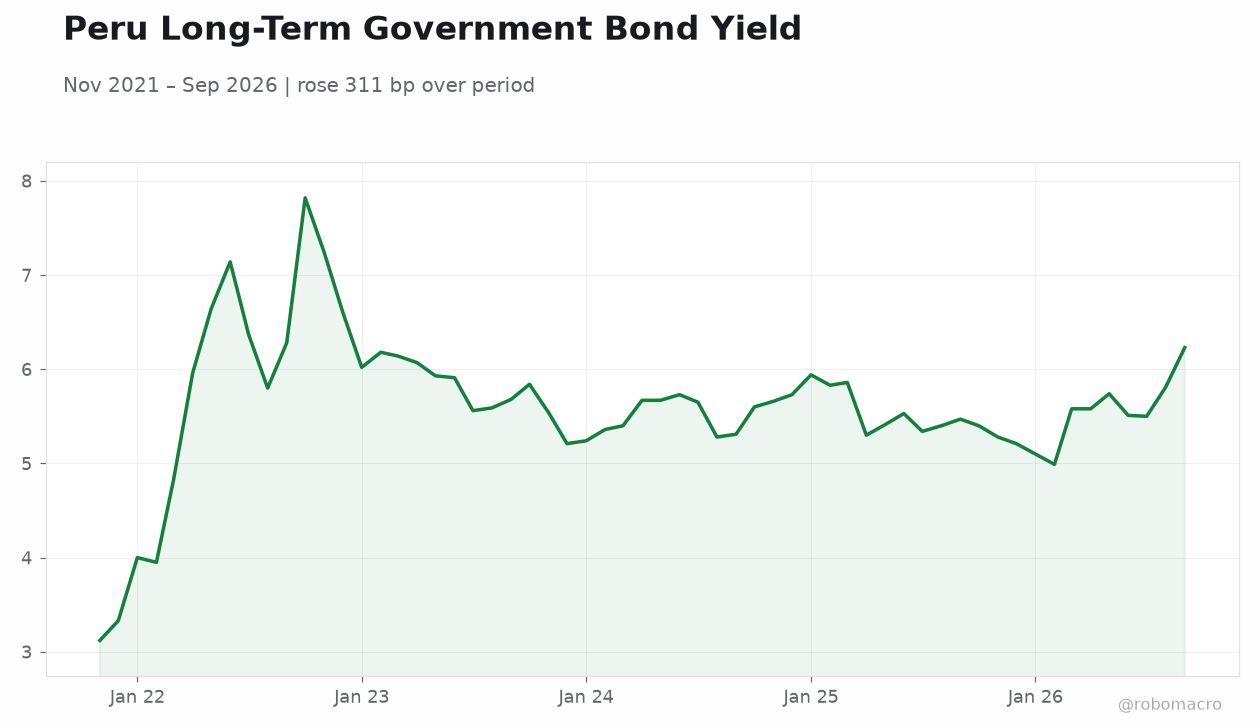
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
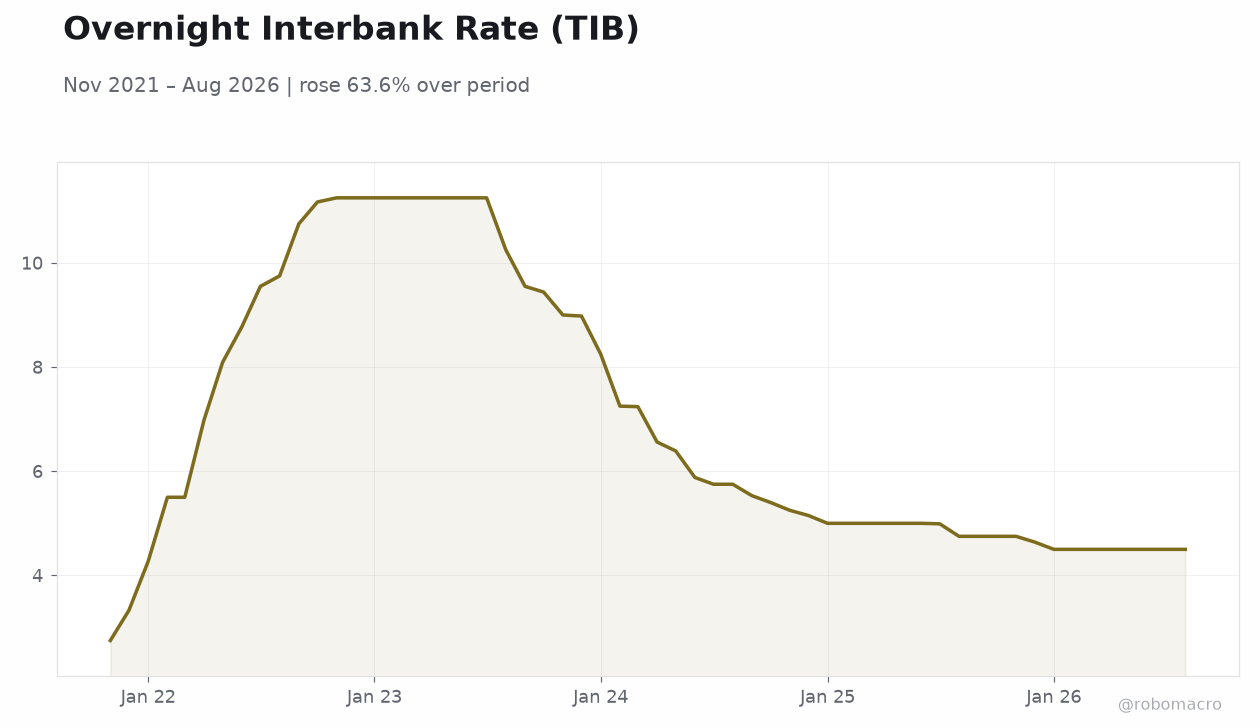
| Central Bank Interest Rate Decision | 4.50 | 4.50 | 4.50 |
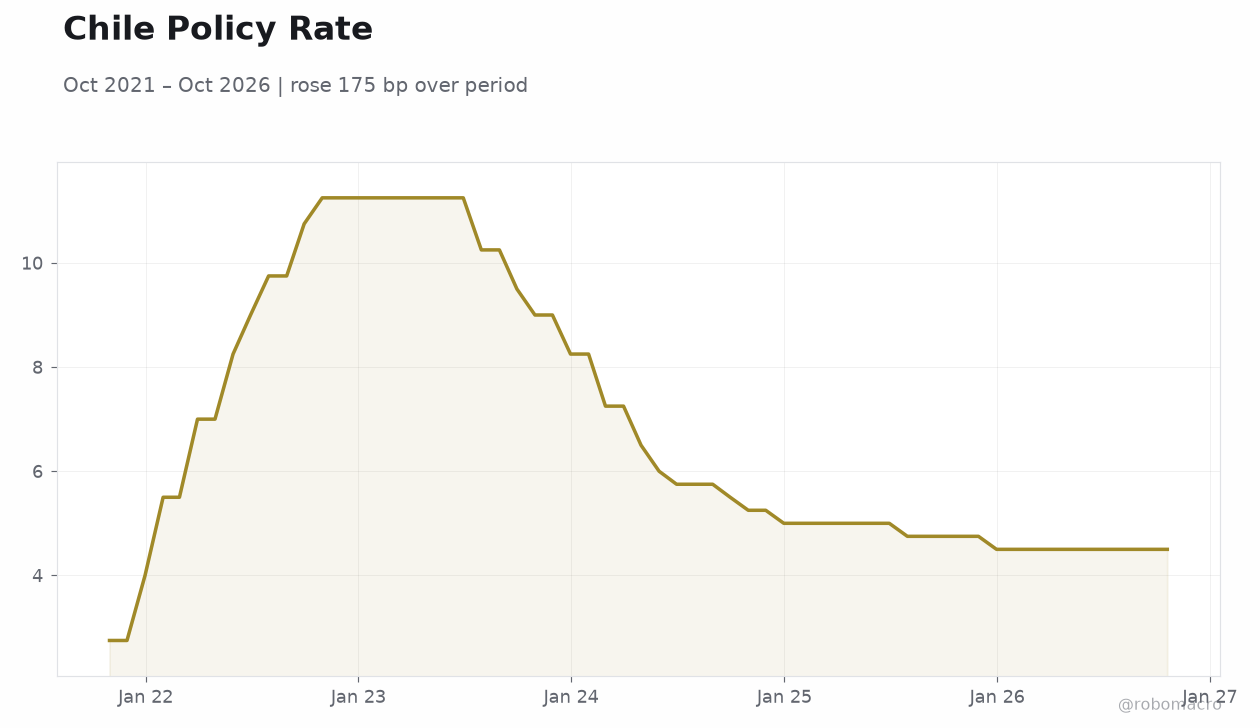 Chile Policy Rate | Type: macro_line | BCCh Policy Rate (%): 4.5 (2026-10-20) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,6.5,4.75,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
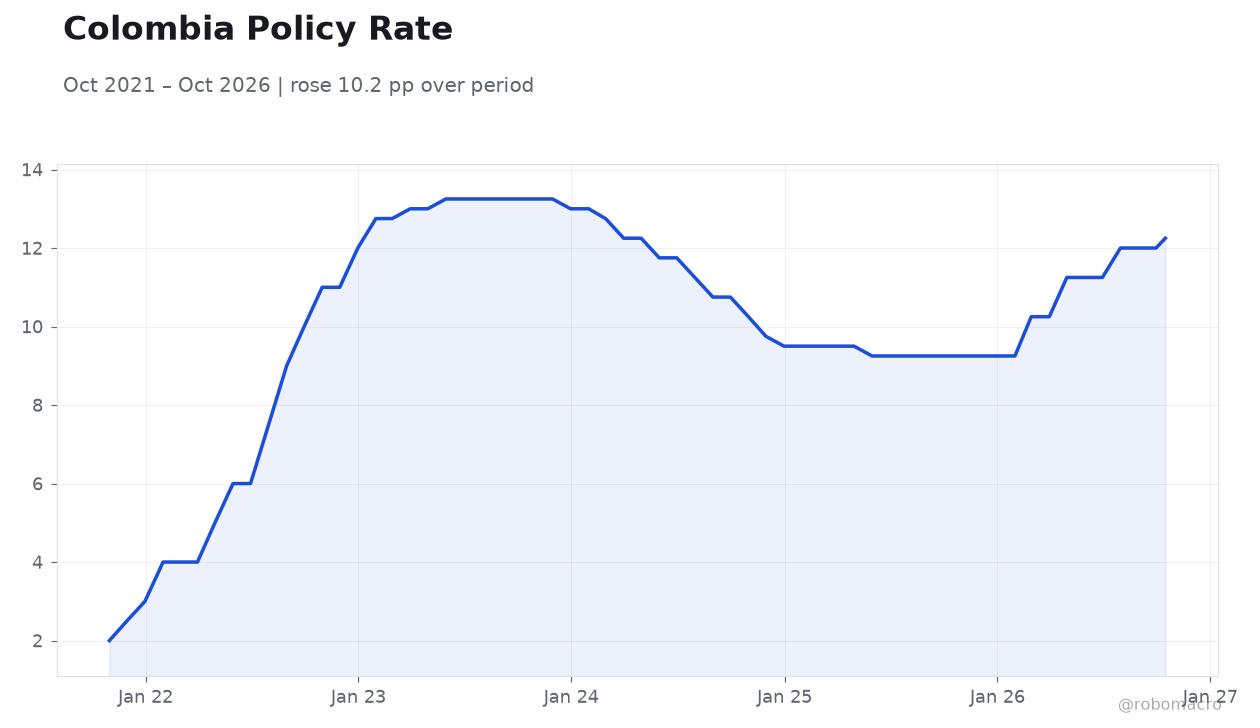
| Central Bank Interest Rate Decision | 12.25 | - | 14:00 |
- BCCh held its policy rate at 4.50% on October 27, matching consensus and the previous level, with Chile CPI at 4.08% YoY keeping the easing cycle paused.
- BanRep meets October 30 with the policy rate at 12.25% and Colombia CPI at 6.29% YoY; consensus is unavailable, leaving two-way risk around the hold.
- Chile equities outperformed, with MSCI Chile up 2.28% and the peso firming 1.17% against the dollar as copper edged higher.
Yesterday's Recap
The Bank of Chile (BCCh) held its policy rate at 4.50% on October 27, in line with consensus and the previous level, confirming the pause in the easing cycle as Chilean inflation runs at 4.08% YoY. The decision removes near-term easing risk and anchors the front end of the Chilean curve. Market reaction was constructive: MSCI Chile rose 2.28% and the Chilean peso appreciated 1.17% against the dollar to 977.90, supported by copper's 0.48% gain to 6.65.
Peru's MSCI index added 1.29% while the sol slipped 0.15% to 3.45, a modest underperformance versus Chile. Colombia was the laggard, with MSCI Colombia flat at 9.02 and the peso essentially unchanged at 3,145.89, as investors positioned defensively ahead of the October 30 BanRep decision. Regional sentiment was mixed, with Brazil's growth debate dominating LatAm headlines and offering little directional spillover to Andean assets.
The Day Ahead
The dominant event is BanRep's October 30 policy decision, with the rate at 12.25% and consensus unpublished in the calendar, leaving the hold-versus-hike debate genuinely open given Colombian inflation at 6.29% YoY. Positioning into that meeting will likely keep COP volatility elevated and could cap rallies in Colombian local assets. No Chilean or Peruvian data releases are scheduled, so flows will track copper and broader risk appetite.
Chile's post-hold trading will be watched for follow-through in the peso and local rates after the currency's 1.17% appreciation. Peru's sol will take its cue from mining-sector headlines and copper direction. With no tomorrow-dated events, attention front-loads onto the BanRep meeting and its communication on the pace of any further tightening.
Other Economic Notes
Andean inflation dispersion remains the defining macro theme: Colombia at 6.29% YoY, Chile at 4.08%, and Peru at 4.55% (Lima Metropolitana), all for the 12 months to September, with Bolivia at 5.70%. Colombia's elevated print is the key constraint on BanRep's room to maneuver, keeping real rates high and local credit conditions tight. Chile's inflation near 4% justifies the BCCh's cautious pause rather than renewed cuts.
Peru's unchanged 4.25% policy rate preserves its traditional role as the bloc's anchor. ↓ p.2