Andeans Macro Daily(Beta Mode)
Chile Recession Confirmed, Peso Slides; BCRP Hold Eyed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 35.86 | -1.70% |
| MSCI Peru | 81.76 | -1.46% |
| USD/COP | 3,299.00 | +0.75% |
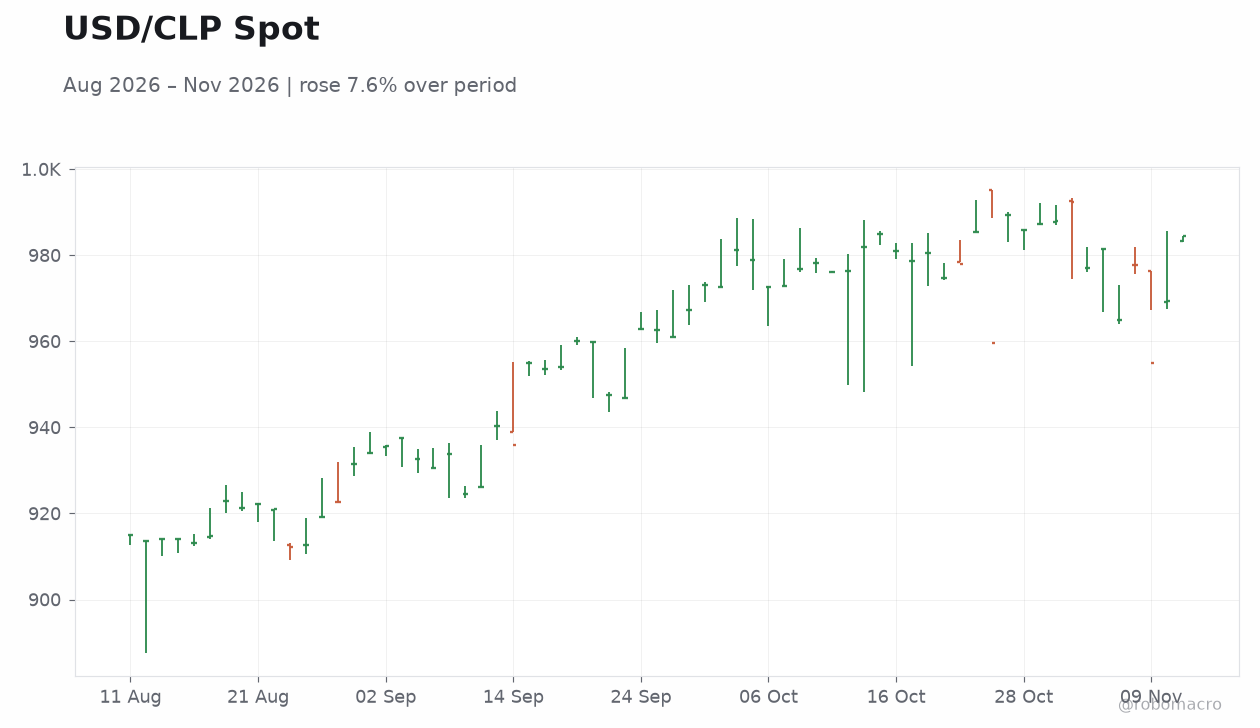
| USD/CLP | 983.83 | +1.50% |
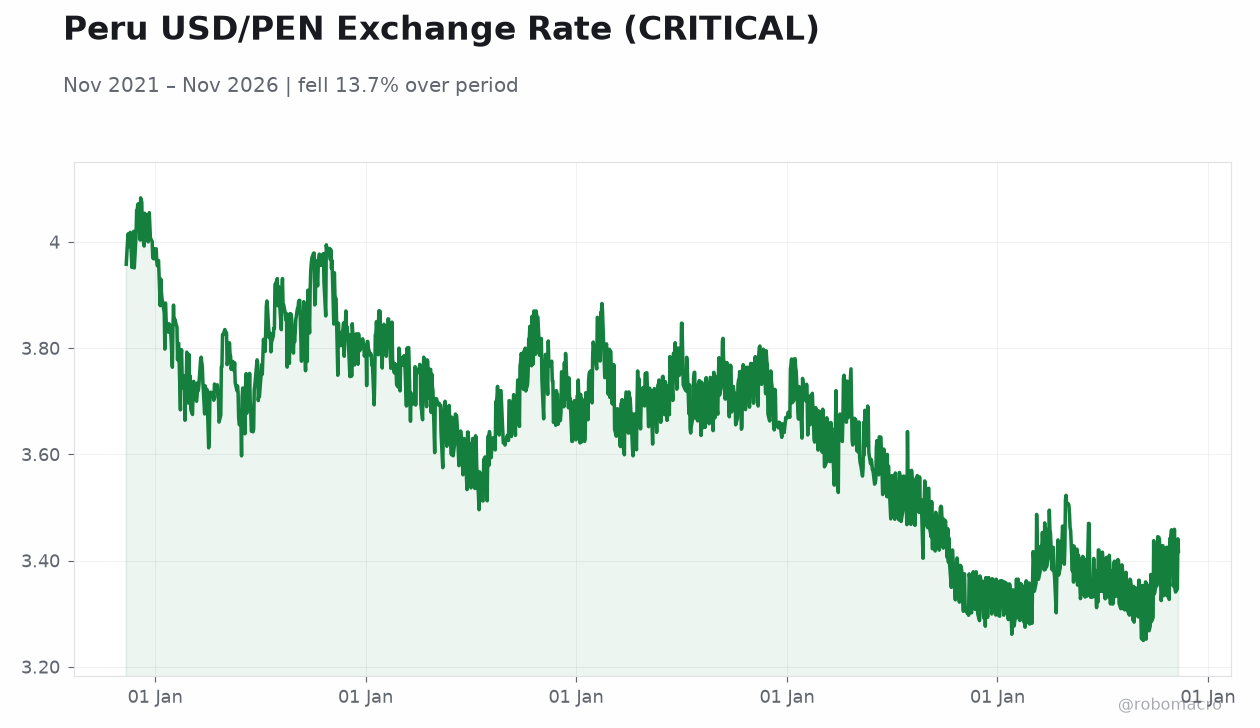
| USD/PEN | 3.42 | -0.69% |
| Copper | 6.31 | +1.46% |
| Gold | 4,063.50 | +0.83% |
| Brent Crude | 92.93 | +1.57% |
| Bitcoin | 73,956.13 | +0.32% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
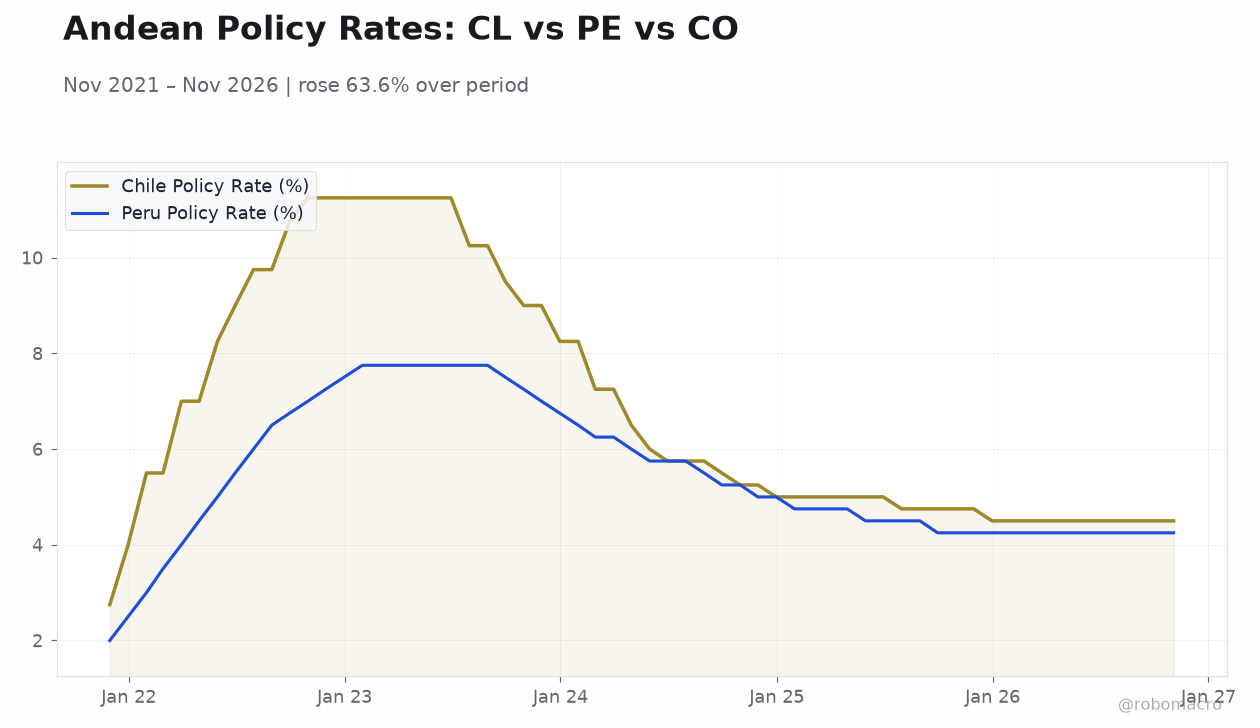 Andean Policy Rates: CL vs PE vs CO | Type: macro_line | Chile Policy Rate (%): 4.5 (2026-11-03) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,6,4.75,4.5 | Peru Policy Rate (%): 4.25 (2026-11-03) | Range: 2–7.75 | Trend(5pt): 2,7.75,5.75,4.5,4.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-12) | |||
| Central Bank Interest Rate Decision | 4.25 | - | 18:00 |
- Chile's Finance Minister Quiroz concedes the economy is in recession, sending USD/CLP up 1.50% to 983.83 and MSCI Chile down 1.70%.
- Peru's BCRP is expected to hold its policy rate at 4.25% at tomorrow's decision, with the sol the sole Andean outperformer, USD/PEN down 0.69% to 3.42.
- Colombia's BanRep remains the regional hawk at 12.25% after September's 25bp hike, with USD/COP up 0.75% to 3,299.
Yesterday's Recap
The Andean bloc traded risk-off on Tuesday, with Chile the clear underperformer. Finance Minister Jorge Quiroz conceded for the first time that the Chilean economy is in recession, a notable admission that drove USD/CLP up 1.50% to 983.83 and MSCI Chile down 1.70% to 35.86. Peru's equity proxy also slipped, with MSCI Peru down 1.46% to 81.76, though the sol bucked the trend, with USD/PEN down 0.69% to 3.42 — the only Andean currency to appreciate.
Colombia was flat on the equity side (MSCI Colombia unchanged at 9.02) but the peso weakened 0.75% to 3,299. Commodities offered no support to the region's terms-of-trade narrative: copper rose 1.46% to 6.31, Brent crude jumped 1.57% to 92.93, and gold added 0.83% to 4,063.50. No Andean macro prints were released on Tuesday, leaving markets to trade on the Chilean recession headline and broader risk sentiment.
Separately, a brazen Chilean bank heist — ten thieves, five hours, CLP5bn — grabbed local headlines but had no market impact.
The Day Ahead
The sole scheduled Andean event is Peru's BCRP central bank interest rate decision on Thursday, November 12 at 18:00 ET, with the previous rate at 4.25% and no consensus published. The BCRP's most recent decision on October 7 left the rate unchanged, and with Peruvian CPI at 5.25% year-on-year as of October 31 — well above target — a hold is the base case. Markets will parse the accompanying statement for any signal on the timing of a first cut, particularly given the sol's recent strength.
No Colombian or Chilean data releases are scheduled for the session. With Chile's recession now official, attention shifts to whether BCCh commentary acknowledges the growth deterioration ahead of its December 15 meeting.
Other Economic Notes
The Chilean recession admission is the most consequential Andean development this week, raising questions about the durability of the BCCh's easing cycle given CPI at 4.52% year-on-year. Peru's economy is forecast to edge past Chile as South America's fourth-largest economy in 2027 by just $154 million, a symbolic shift that underscores divergent growth trajectories within the bloc. Peruvian copper remains a bright spot, with Rio2 Ltd reporting $115M in quarterly revenue and $50M in EBITDA on the back of its Peruvian mine, even as its Chilean operations were weather-affected.
↓ p.2