Andeans Macro Daily(Beta Mode)
Peru Growth Slips, Sol Jumps; Andean CBs Diverge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 35.55 | +0.20% |
| MSCI Peru | 80.80 | -0.09% |
| USD/COP | 3,315.40 | +0.02% |
| USD/CLP | 998.45 | +0.43% |
| USD/PEN | 3.40 | +2.90% |
| Copper | 6.03 | -0.80% |
| Gold | 3,874.50 | -0.30% |
| Brent Crude | 94.91 | -0.97% |
| Bitcoin | 63,920.79 | -2.12% |
| Colombia 10Y Govt Yield | 13.12% | -3 bp |
| Peru 10Y Govt Yield | 6.61% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
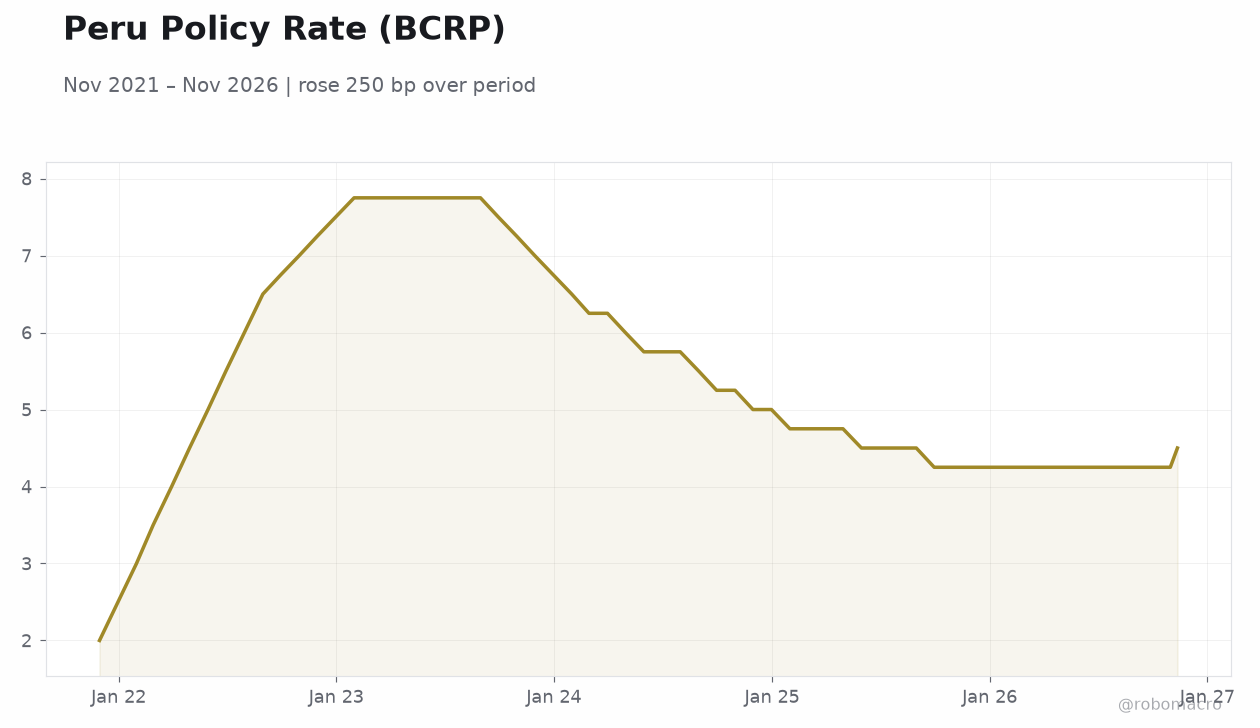 Peru Policy Rate (BCRP) | Type: macro_line | BCRP policy rate (%): 4.5 (2026-11-12) | Range: 2–7.75 | Trend(5pt): 2,7.75,5.75,4.5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Peru's economy unexpectedly slowed as mining and farming output slumped, complicating the picture after the BCRP's November 12 hike to 4.50%.
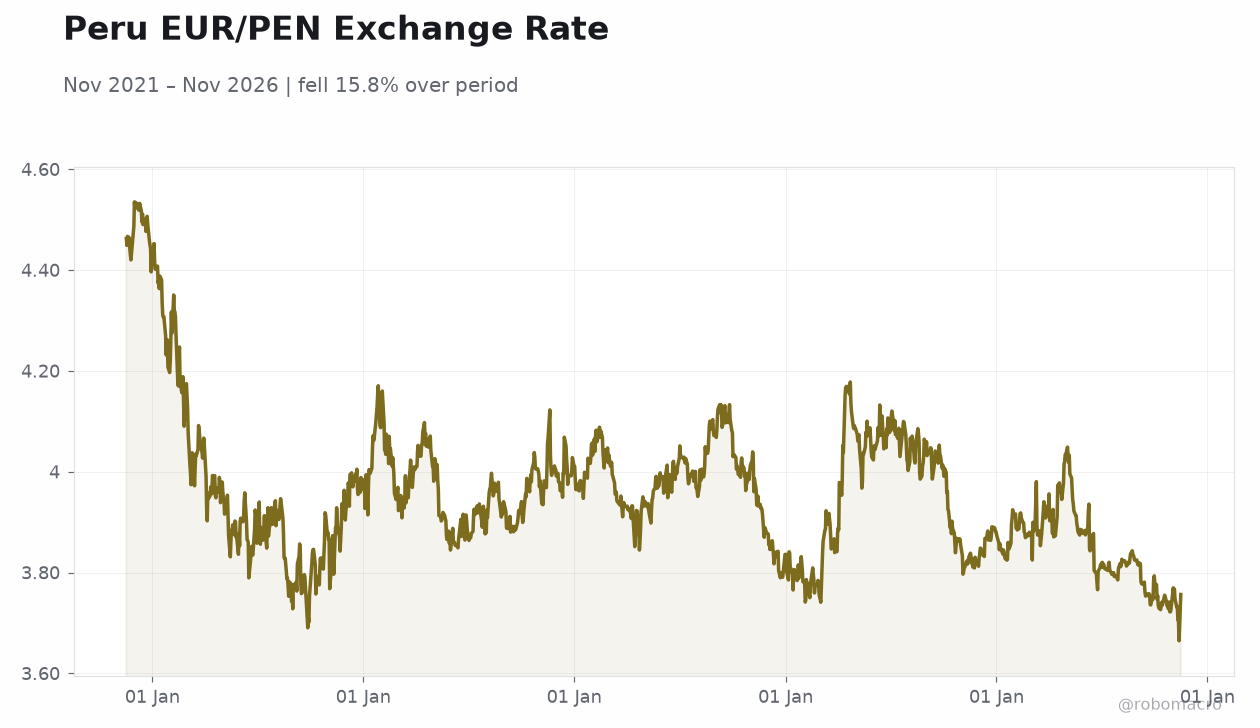
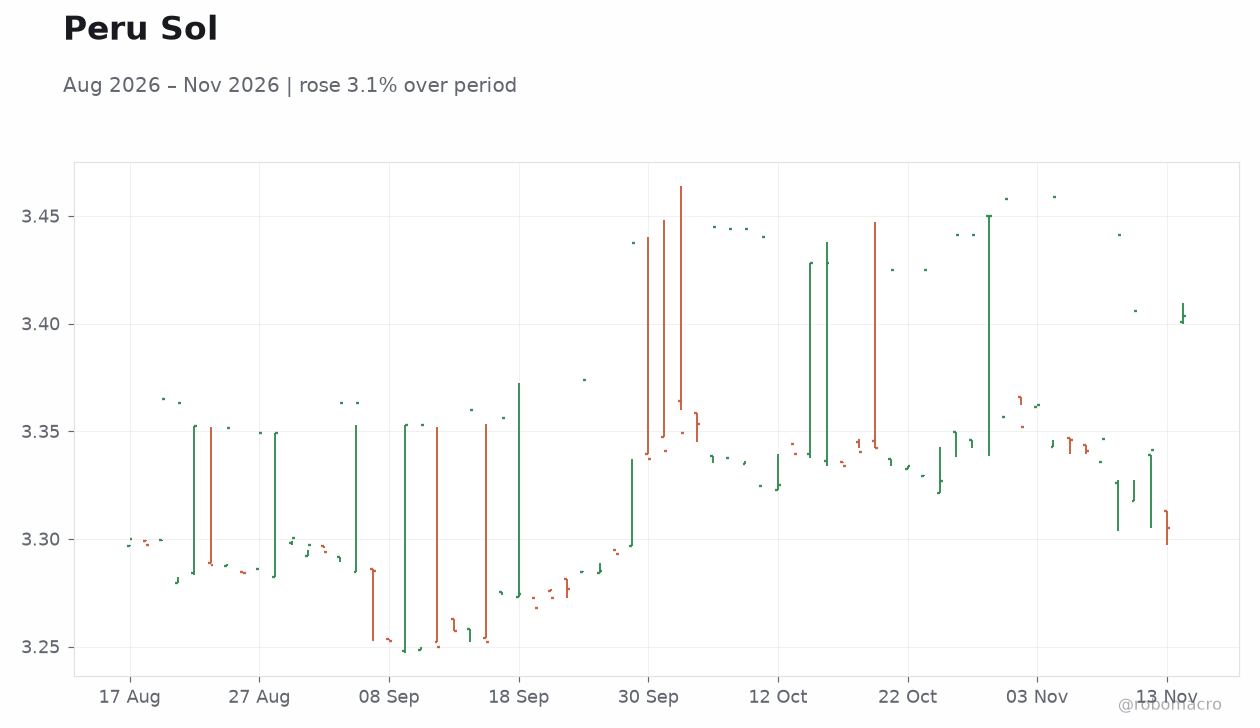
- USD/PEN jumped 2.90% to 3.40, the sharpest move in the bloc, while USD/CLP rose 0.43% to 998.45 and USD/COP held near 3,315.40.
- Chile weighs private-sector participation in Codelco's mines; copper fell 0.80% to $6.03/lb, pressuring CLP and Peruvian fiscal revenue.
Yesterday's Recap
Peru dominated the Andean tape as Bloomberg reported the economy unexpectedly slowed, with mining and farming output slumping — a sour note just days after the BCRP's November 12 decision to hike its policy rate 25 bp to 4.50%. The sol bore the brunt: USD/PEN surged 2.90% to 3.40, by far the bloc's largest FX move, while the Peru 10-year yield added 5 bp to 6.61% (as of November 12). Lima equities were soft, with MSCI Peru down 0.09% to 80.80.
Chile was comparatively quiet: MSCI Chile edged up 0.20% to 35.55, but USD/CLP rose 0.43% to 998.45 as copper slipped 0.80% to $6.03/lb. Colombia was the steady hand — MSCI Colombia flat at 9.02, USD/COP up just 0.02% at 3,315.40, and the Colombia 10-year yield easing 3 bp to 13.12% (as of November 6). Regional color was downbeat, with Brazil's IBC-Br falling 0.2% in September, reinforcing a broader LatAm slowdown narrative.
The Day Ahead
No scheduled Andean macro releases appear on the calendar for today, leaving markets to digest the Peruvian slowdown and the sol's sharp depreciation. Attention turns to whether the BCRP's November 12 hike — a hawkish turn against the regional grain — is corroborated or complicated by the soft activity print. In Chile, the Codelco private-sector partnership debate will be watched for signals on investment and copper output, a key CLP driver.
Colombia's calendar is empty, so local focus stays on the 13.12% 10-year yield and BanRep's December 18 meeting trajectory. With no data to anchor trading, Andean FX will likely take direction from global risk sentiment and the dollar.
Other Economic Notes
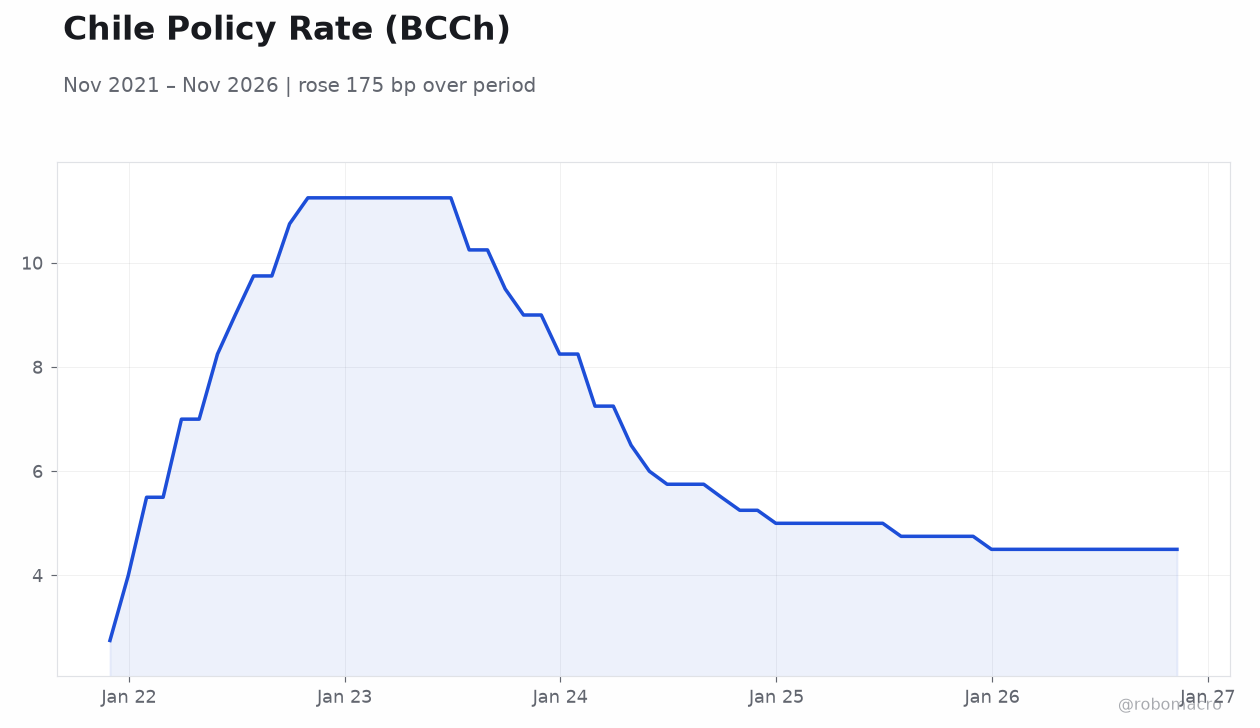
The divergence within the bloc is widening. Peru's inflation at 5.25% YoY (October, BCRP) sits above target and justified the BCRP's hike, yet the activity slump raises stagflation risk. Chile's CPI at 4.52% YoY (October, IMF) remains above the BCCh's 3% goal, limiting room for further easing after rates were cut to 4.50%.
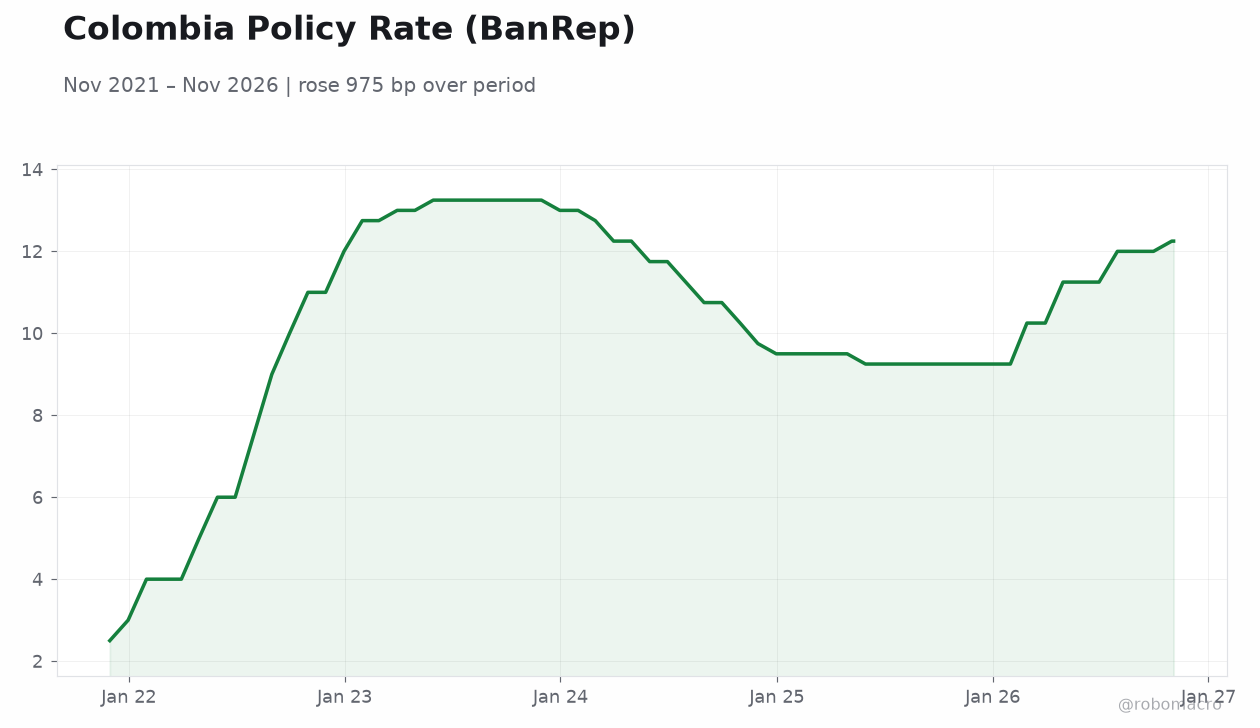
Colombia's CPI at 6.29% YoY (September, IMF) keeps BanRep's 12.25% rate firmly restrictive. Fiscal pressure is a common thread — Peru's mining-dependent revenue is exposed to copper at $6.03/lb, while Chile's Codelco partnership push reflects strained state finances. The weak regional growth outlook flagged by UPI underscores limited fiscal buffers across the bloc.