Andeans Macro Daily(Beta Mode)
Peru FX Slides as BCRP Hike, Brazil Selloff Reverberate
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 35.06 | -1.38% |
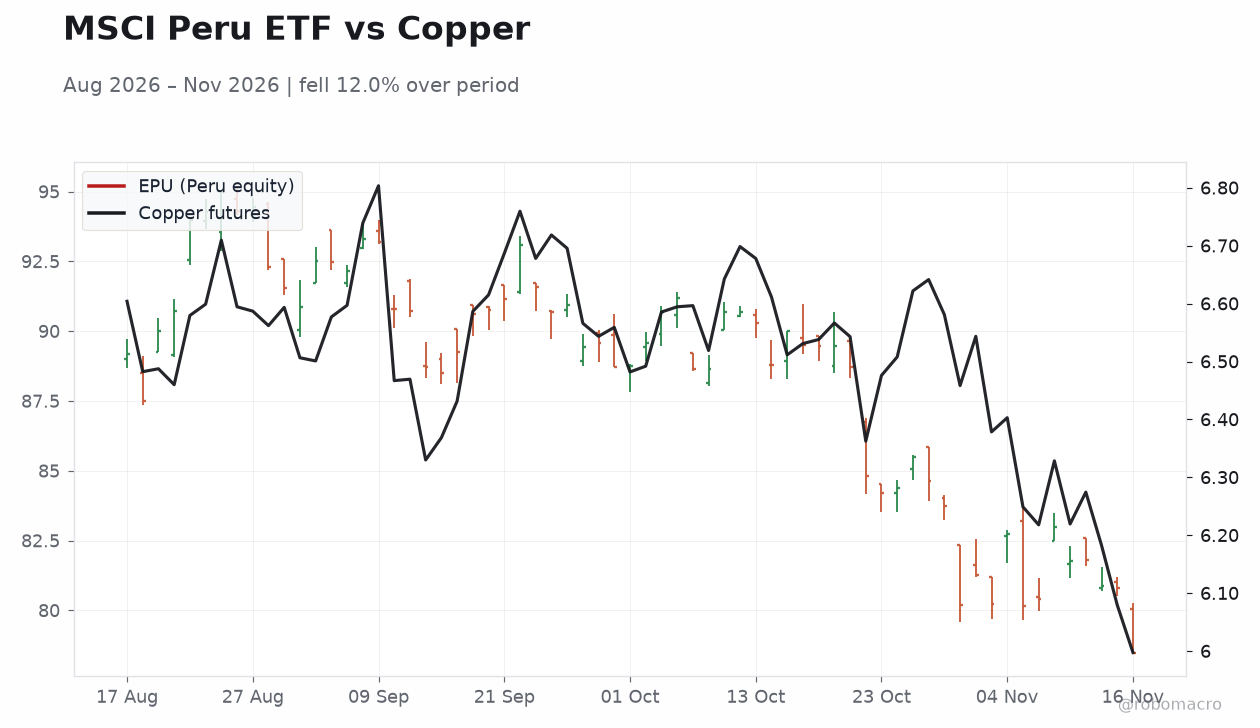
| MSCI Peru | 78.49 | -2.86% |
| USD/COP | 3,319.42 | +0.04% |
| USD/CLP | 994.68 | +2.01% |
| USD/PEN | 3.41 | +3.28% |
| Copper | 5.99 | -0.19% |
| Gold | 3,872.00 | +0.49% |
| Brent Crude | 92.72 | +0.30% |
| Bitcoin | 64,754.86 | -0.16% |
| Colombia 10Y Govt Yield | - | - |
| Peru 10Y Govt Yield | 6.59% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
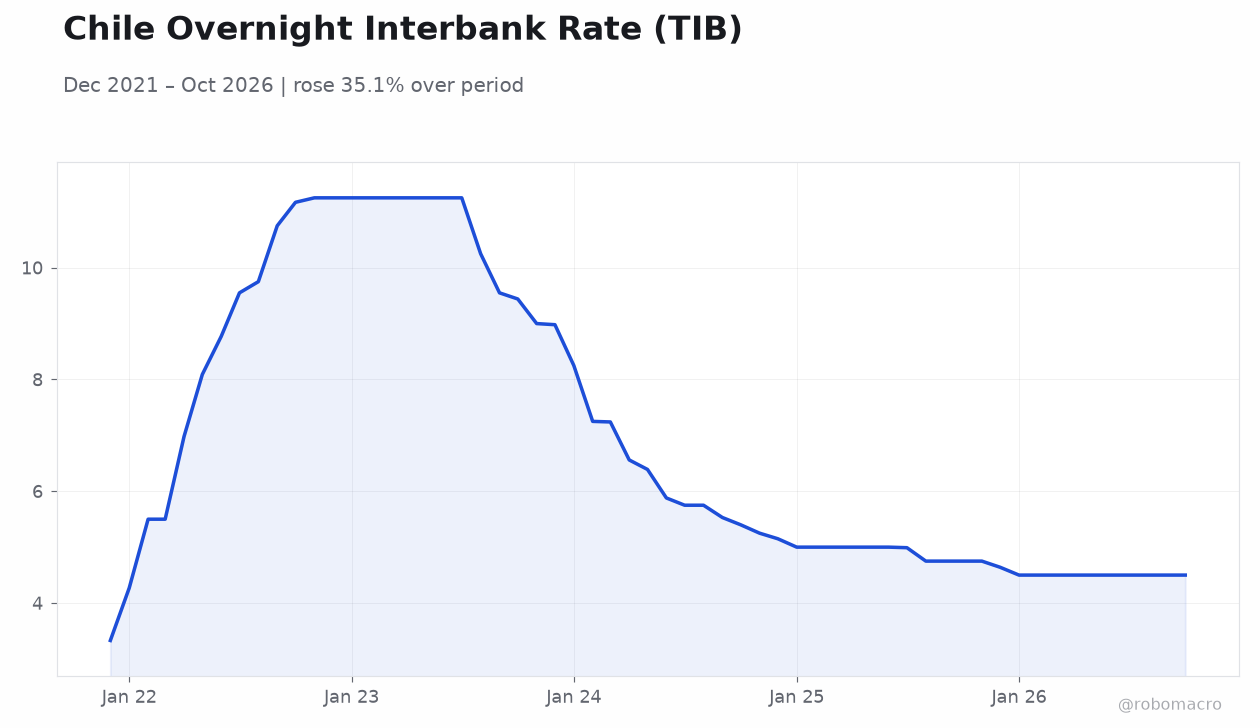
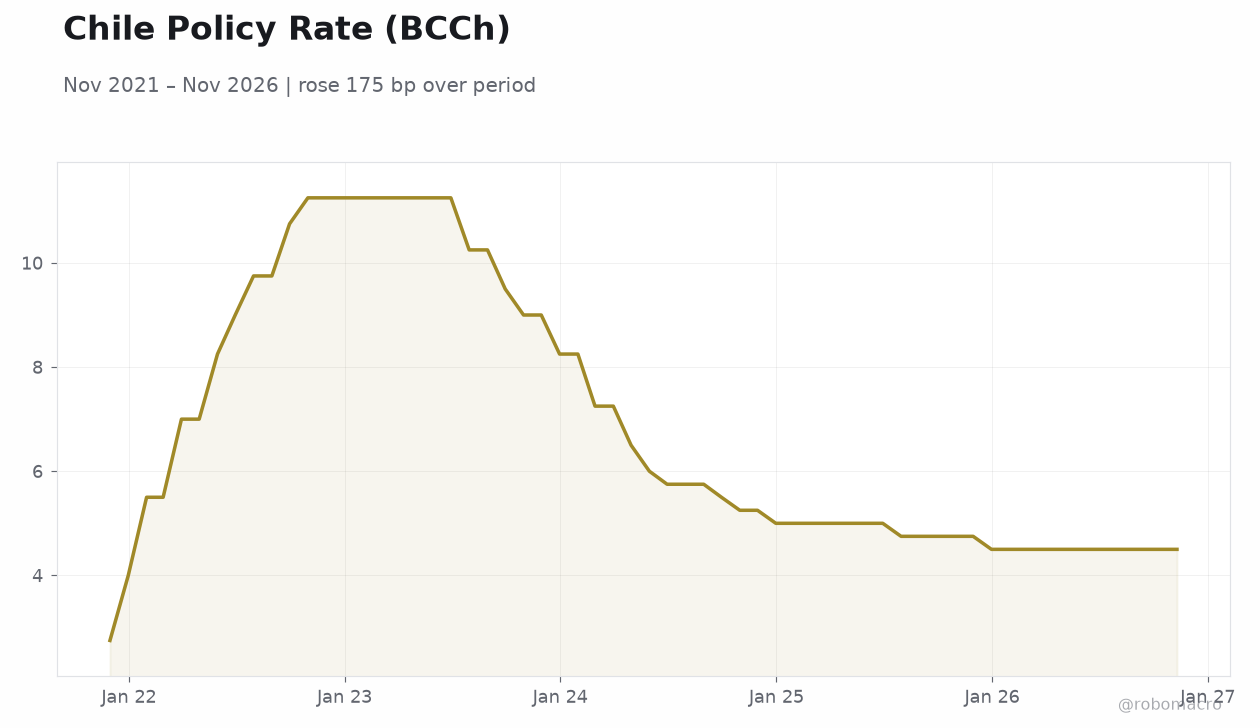 Chile Policy Rate (BCCh) | Type: macro_line | Policy rate (%): 4.5 (2026-11-10) | Range: 2.75–11.25 | Trend(5pt): 2.75,11.25,6,4.75,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
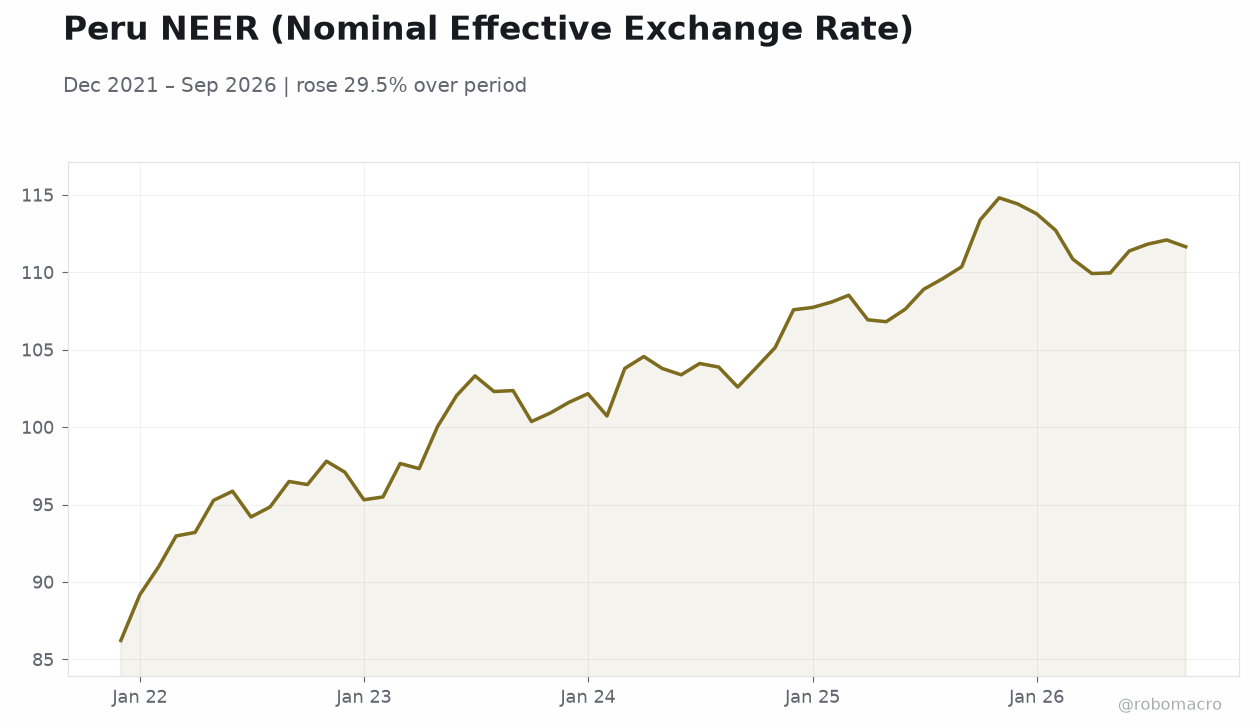
- Peru's sol led Andean FX losses, USD/PEN jumping 3.28% to 3.41, while USD/CLP rose 2.01% to 994.68 and USD/COP held near 3,319.42 (+0.04%).
- BCRP's +25bp hike to 4.50% on Nov 12 continues to reprice Peruvian assets; the 10Y yield eased 2 bp to 6.59% even as the currency weakened.
- Regional risk-off dominated: Brazil's IBC-Br contraction and 19-month-low real dragged LatAm equities, with MSCI Peru -2.86% and MSCI Chile -1.38% versus flat MSCI Colombia.
Yesterday's Recap
Andean markets on Monday were defined by a sharp divergence between FX and rates. Peru's sol bore the brunt of the regional selloff, with USD/PEN surging 3.28% to 3.41 — an outsized move for a currency that typically trades in narrow ranges — even as the Peru 10Y government yield eased 2 bp to 6.59%, suggesting the bond market is pricing the BCRP's Nov 12 +25bp hike to 4.50% as a credible inflation-fighting step rather than a growth threat. Chile fared little better on the currency side, USD/CLP climbing 2.01% to 994.68, with MSCI Chile down 1.38% to 35.06 as copper's modest -0.19% dip to $5.99/lb offered no support.
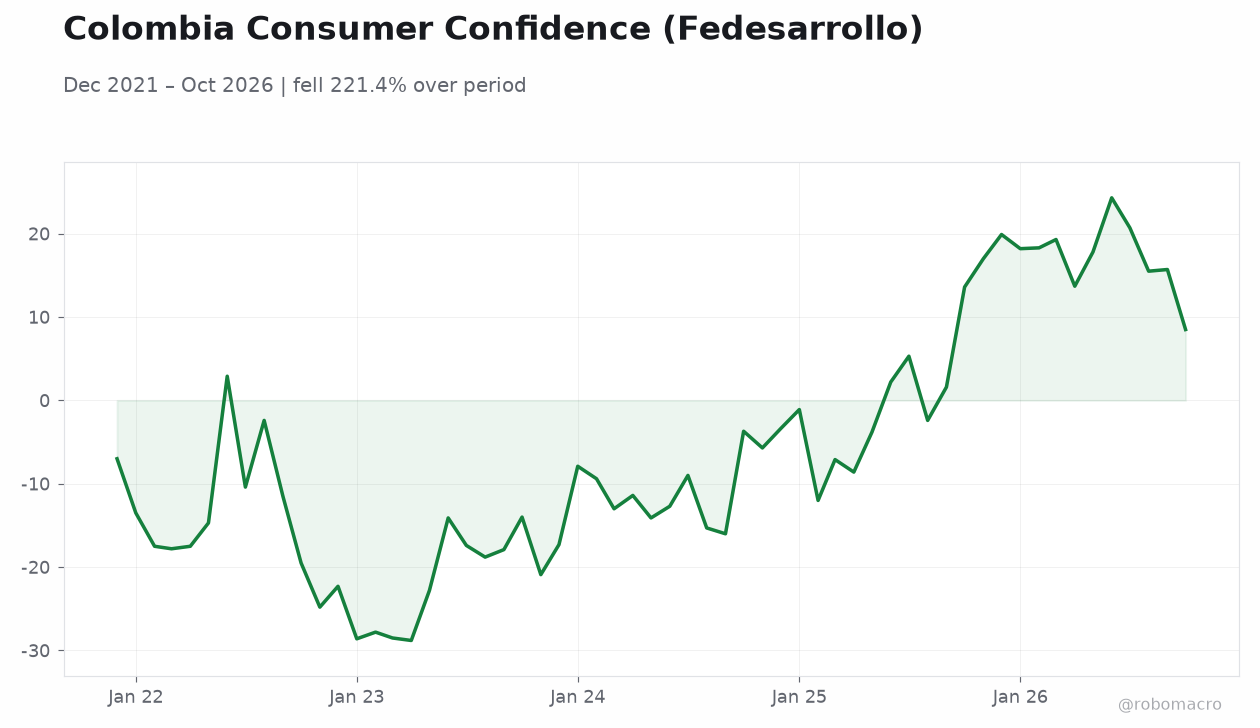
Colombia was the relative outlier: USD/COP essentially unchanged at 3,319.42 (+0.04%) and MSCI Colombia flat at 9.02, insulating the bloc's most hawkish central bank from the worst of the risk-off. The common thread was external: Brazil's IBC-Br activity proxy fell 0.2% in September and the real hit a 19-month low, triggering a broad LatAm de-risking that spilled into Andean credit and equity proxies. No scheduled Andean macro prints landed on the calendar, so price action was purely flow- and sentiment-driven.
The Day Ahead
The Andean calendar is empty for Tuesday, November 17, leaving markets to trade off external cues and positioning ahead of a dense December central bank schedule. Attention will center on whether the sol's 3.28% slide extends or stabilizes, given the BCRP's freshly tightened 4.50% policy rate and its next decision on December 10. Chile watchers will monitor CLP around the 995 level and copper's hold near $6.00/lb, with the BCCh's December 15 meeting the next policy catalyst.
Colombia's comparatively calm COP will be tested by oil — Brent at $92.72 (+0.30%) — and by positioning into BanRep's December 18 decision. With no domestic data to anchor sentiment, Andean desks will take their tone from Brazil and global risk appetite.
Other Economic Notes
The Andean bloc's inflation picture remains uneven and constrains policy optionality. Peru's CPI at 5.25% YoY (October) sits well above target, justifying the BCRP's Nov 12 hike to 4.50%; Chile's 4.52% (October) is elevated but consistent with the BCCh's extended hold at 4.50%; Colombia's 6.29% (September) is the region's stickiest and underpins BanRep's 12.25% stance. ↓ p.2