Andeans Macro Daily(Beta Mode)
Chile GDP Plunges, Andean FX Under Pressure
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MSCI Colombia | 9.02 | +0.00% |
| MSCI Chile | 34.24 | -2.73% |
| MSCI Peru | 75.03 | -4.42% |
| USD/COP | 3,341.98 | +1.05% |
| USD/CLP | 1,005.88 | +1.21% |
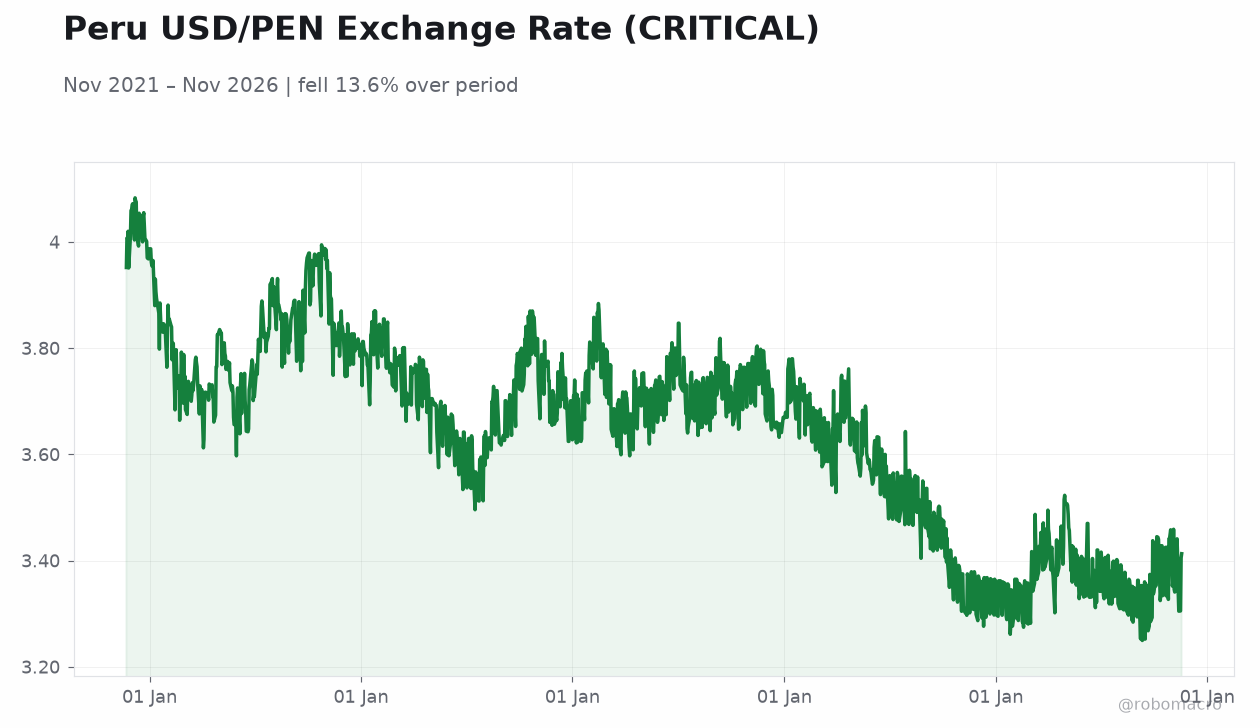
| USD/PEN | 3.41 | +0.23% |
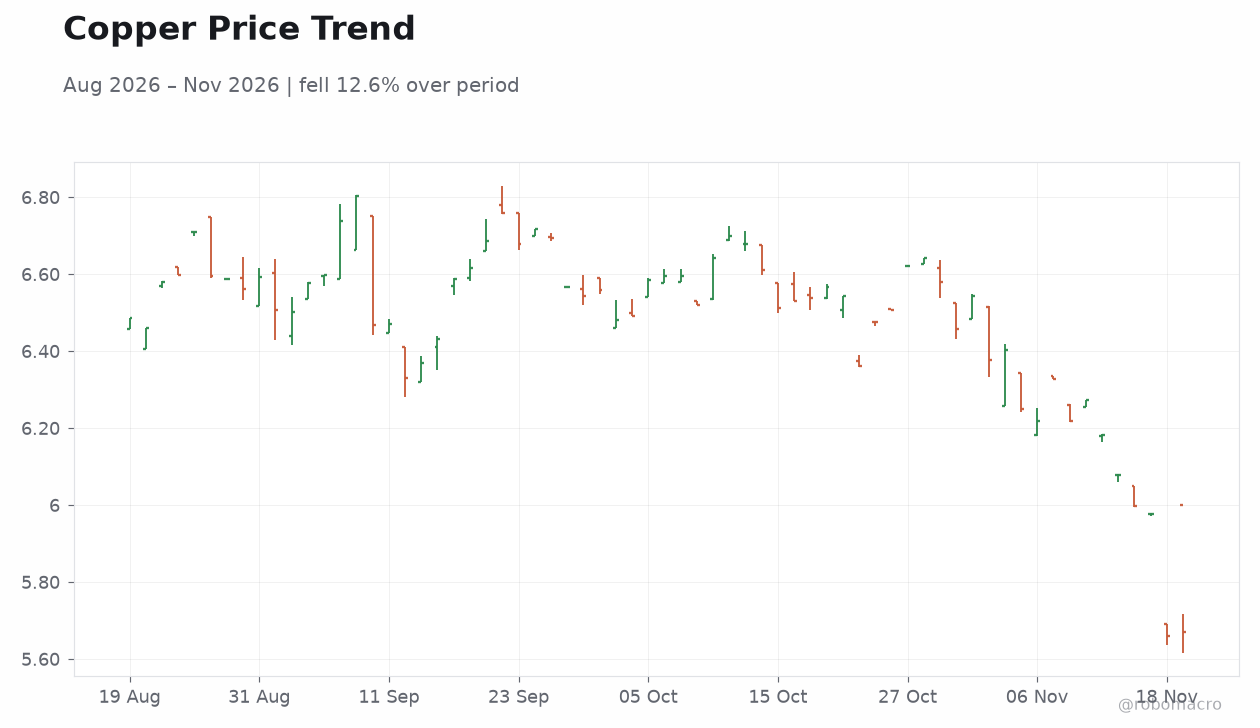
| Copper | 5.67 | +0.27% |
| Gold | 3,733.20 | -0.23% |
| Brent Crude | 88.74 | -3.49% |
| Bitcoin | 63,911.76 | +1.47% |
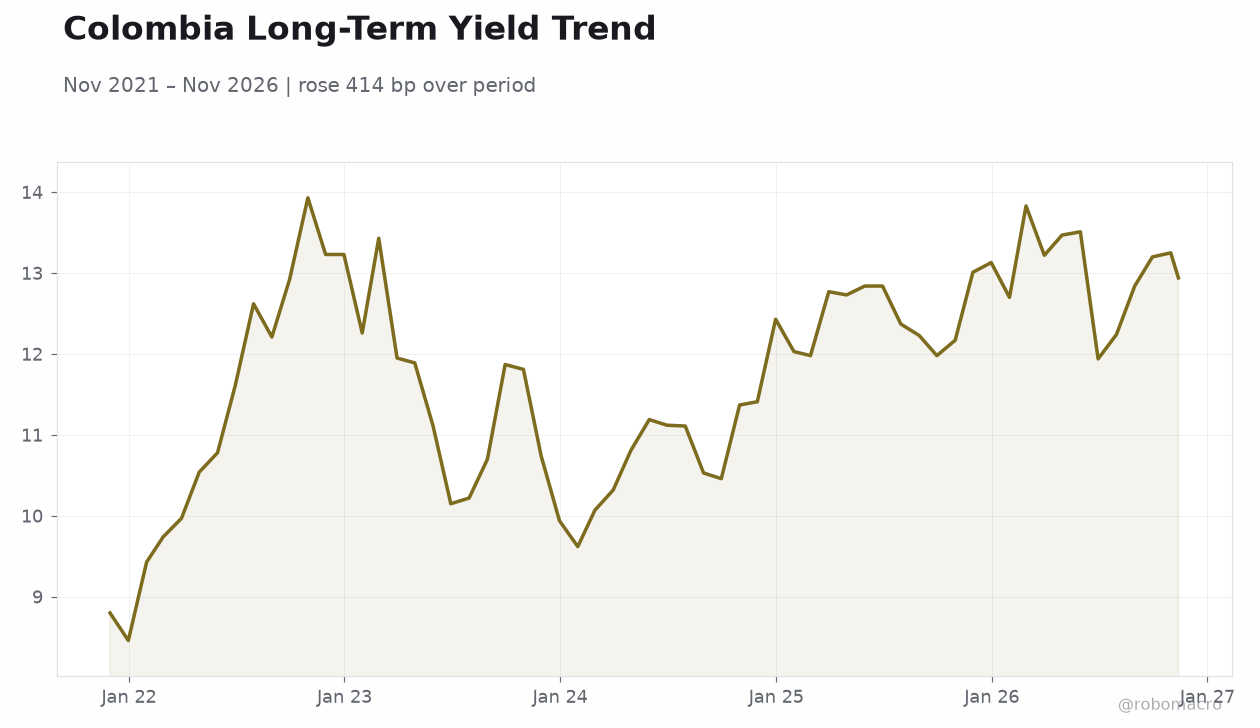
| Colombia 10Y Govt Yield | 12.94% | +4 bp |
| Peru 10Y Govt Yield | 6.68% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
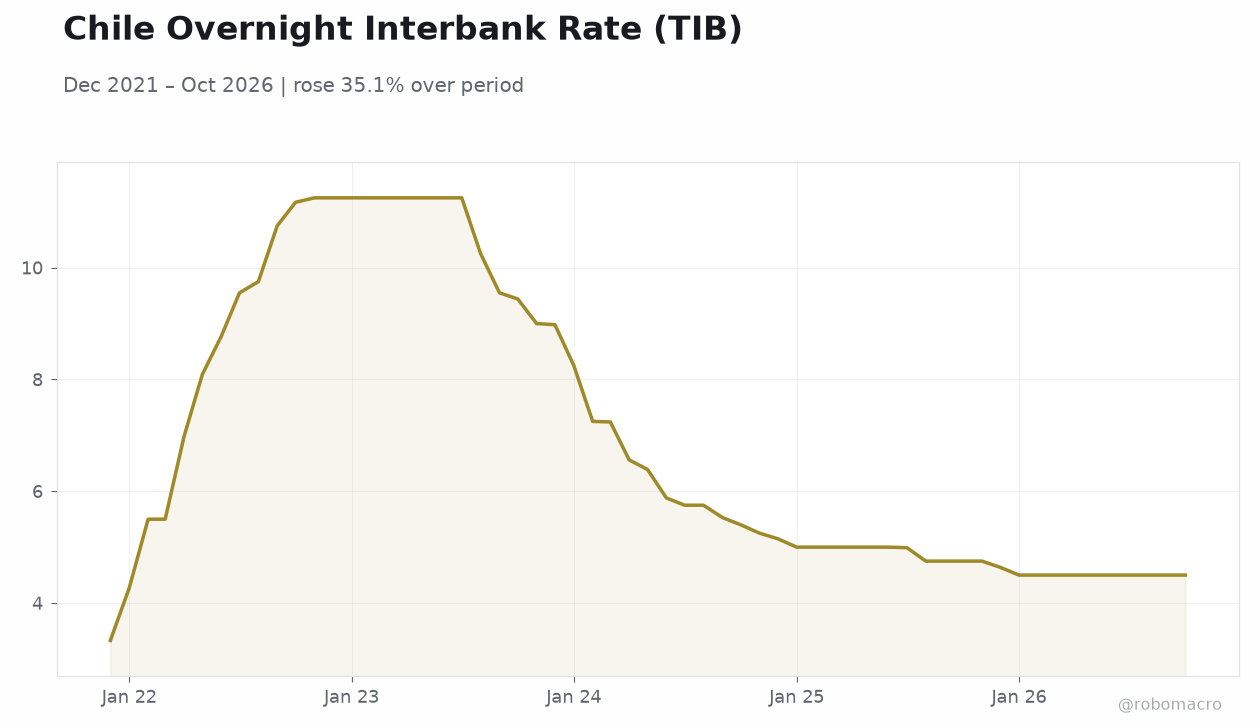 Chile Overnight Interbank Rate (TIB) | Type: macro_line | Overnight Interbank Rate (TIB): 4.5 (2026-10-01) | Range: 3.33–11.25 | Trend(5pt): 3.33,11.25,6.56,5,4.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Chile's economy contracted 1.8% in Q3, the sharpest quarterly decline since 2020, driven by a mining slump
- Andean currencies weakened broadly; USD/CLP rose 1.21% to 1,005.88 and USD/COP climbed 1.05% to 3,341.98
- Peru's 10-year yield added 5 bp to 6.68% while Colombia's 10-year rose 4 bp to 12.94%
Yesterday's Recap
Chile's economy contracted 1.8% in the third quarter, the biggest quarterly drop since 2020, as a mining slump weighed heavily on activity. The print underscores the fragility of Chile's recovery and complicates the BCCh's policy trajectory. Andean equity markets sold off sharply, with MSCI Peru down 4.42% and MSCI Chile off 2.73%, while MSCI Colombia was flat.
Currency markets reflected the risk-off tone: USD/CLP rose 1.21% to 1,005.88, USD/COP gained 1.05% to 3,341.98, and USD/PEN edged up 0.23% to 3.41. In fixed income, Colombia's 10-year yield added 4 bp to 12.94% and Peru's 10-year rose 5 bp to 6.68%. Copper gained just 0.27% to 5.67, offering little support to Chile and Peru, while Brent crude fell 3.49% to 88.74, a headwind for Colombia's fiscal outlook.
The Day Ahead
The Andean calendar is light, with no major scheduled releases across Colombia, Chile, or Peru. Market attention will center on follow-through from Chile's weak Q3 GDP print and its implications for the BCCh's December 15 meeting. Traders will monitor copper and oil price action for directional cues, given copper's importance to Chile and Peru and oil's relevance to Colombia.
Regional FX will likely take their lead from broader dollar dynamics and global risk sentiment. Any commentary from Andean policymakers on the growth outlook could move local rates.
Other Economic Notes
Chile's mining slump is the dominant regional theme, with output weakness raising questions about the durability of the country's fiscal and external accounts. Peru's equity market underperformance alongside a 5 bp yield increase suggests investors are pricing slower activity and political uncertainty. Colombia's flat equity market masks persistent pressure from elevated yields at 12.94%, which continue to crowd out private investment.
The divergence between copper's modest gain and Chile's GDP collapse highlights that price levels alone cannot offset volume declines in the mining sector. Oil's 3.49% drop is a reminder that Colombia's fiscal revenue remains highly sensitive to crude prices.
Global Macro News
Global markets are digesting a mixed risk backdrop, with Bitcoin up 1.47% to 63,911.76 signaling resilient appetite for risk assets even as Andean equities sold off. ↓ p.2