RoboMacro ResearchAlso todaySee the Commodities Daily

Argentina Macro Daily(Beta Mode)

November 03, 2026 robomacro.com

Peso Slides as Recession Fears Mount

MERVAL2,848,945.00-0.35%
USD/ARS1,545.00+0.61%
EUR/ARS1,728.39+0.89%
Gold3,905.20-1.62%

Market Snapshot

AssetLevelChange
MERVAL2,848,945.00-0.35%
USD/ARS1,545.00+0.61%
EUR/ARS1,728.39+0.89%
Gold3,905.20-1.62%
Brent Crude106.88+2.01%
Soybean1,220.25+1.29%
Bitcoin76,707.06+0.04%
Argentina 10Y--

Prior Economic Events

Data Prior Cons Actual
No events available
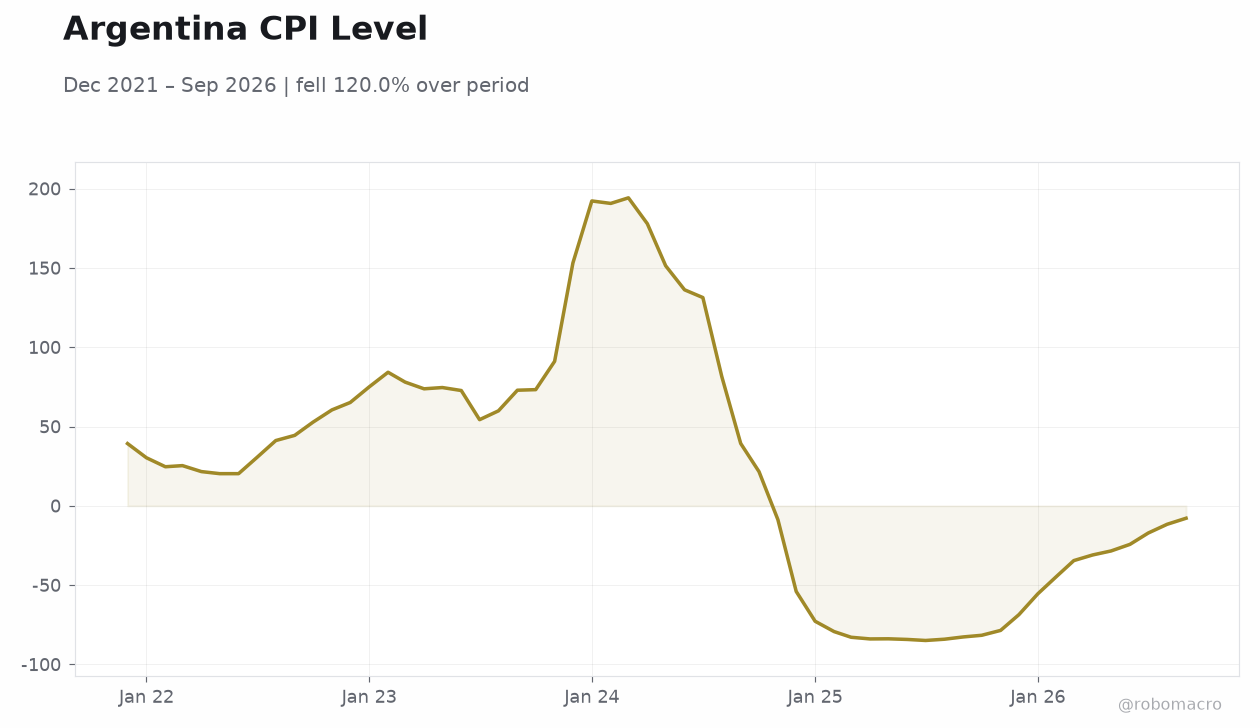
Argentina CPI LevelArgentina CPI Level | Type: macro_line | CPI Index: -7.835 (2026-09-01) | Range: -84.92–194.2 | Trend(6pt): 39.25,84.21,177.9,-84.27,-11.64,-7.835

Today's Economic Events

Data Prior Cons Time
No events available
  • USD/ARS rose 0.61% to 1,545 as austerity-driven contraction tests Milei's political capital ahead of 2027
  • MERVAL slipped 0.35% to 2,848,945; Brent jumped 2.01% to $106.88, complicating the disinflation path
  • CPI at 33.4% YoY keeps real rates deeply negative, sustaining peso pressure despite tight fiscal stance

Yesterday's Recap

Argentina's austerity-hit economy continues to reel toward recession, with Reuters highlighting the political risk building ahead of the 2027 vote as Milei's adjustment program bites into activity. The peso weakened 0.61% against the dollar to 1,545, extending a gradual crawl higher, while the EUR/ARS cross rose 0.89% to 1,728.39. The MERVAL equity benchmark edged down 0.35% to 2,848,945, reflecting cautious positioning amid thin liquidity.

In commodities, Brent crude surged 2.01% to $106.88 — a headwind for Argentina's energy import bill — while soybean prices gained 1.29% to $1,220.25, offering marginal support to the key export complex. Gold fell 1.62% to $3,905.20, and Bitcoin was essentially flat at 76,707. The 10-year sovereign yield was not quoted in the data feed, leaving bond-market direction unclear for the session.

No official Argentine data releases were scheduled, so price action reflected positioning and external drivers rather than domestic prints.

The Day Ahead

The calendar is empty for Wednesday, November 4, with no scheduled Argentine data releases, leaving markets to trade on external cues and BCRA reserve dynamics. Attention will center on the parallel FX gap and whether the official crawl continues at its recent pace. Soybean and Brent moves overnight will feed directly into export-dollar expectations and the energy trade balance.

Traders will also watch for any BCRA communication on reserve accumulation targets under the IMF program. With no domestic catalysts, peso and MERVAL direction will likely track global risk appetite and commodity swings.

Other Economic Notes

The Reuters narrative of an economy reeling toward recession underscores the tension between fiscal consolidation and growth: the primary-balance anchor is holding, but activity is contracting, and the political calendar ahead of 2027 is becoming a market variable. CPI at 33.4% YoY remains elevated, and with the crawl in place, real appreciation risk builds if inflation decelerates faster than the FX band. Soybean strength is a welcome offset for export settlements, but the Brent rally raises energy import costs and pressures the trade surplus that underpins reserve accumulation.

↓ p.2
Page 1

Argentina Macro Daily(Beta Mode)

November 03, 2026 robomacro.com
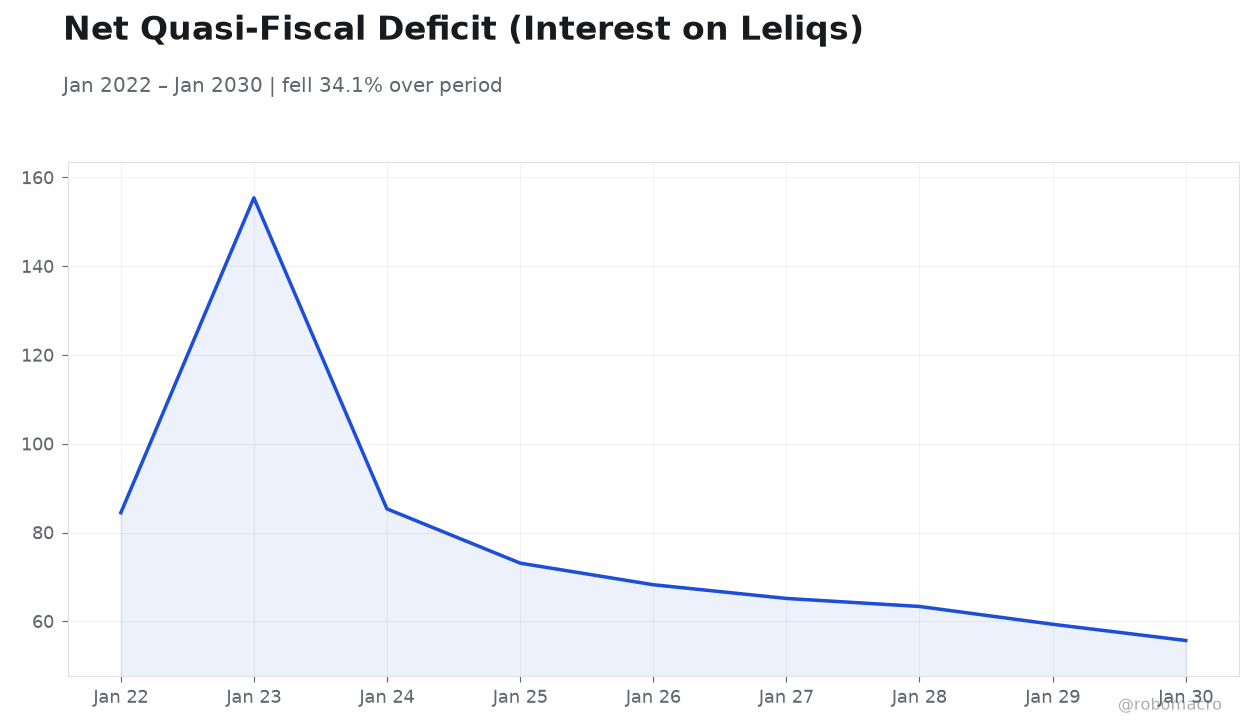
Net Quasi-Fiscal Deficit (Interest on Leliqs) Net Quasi-Fiscal Deficit (Interest on Leliqs) | Type: macro_line | Net Quasi-Fiscal Deficit (Interest on Leliqs): 55.67 (2030-01-01) | Range: 55.67–155.4 | Trend(5pt): 84.46,85.33,68.23,63.34,55.67
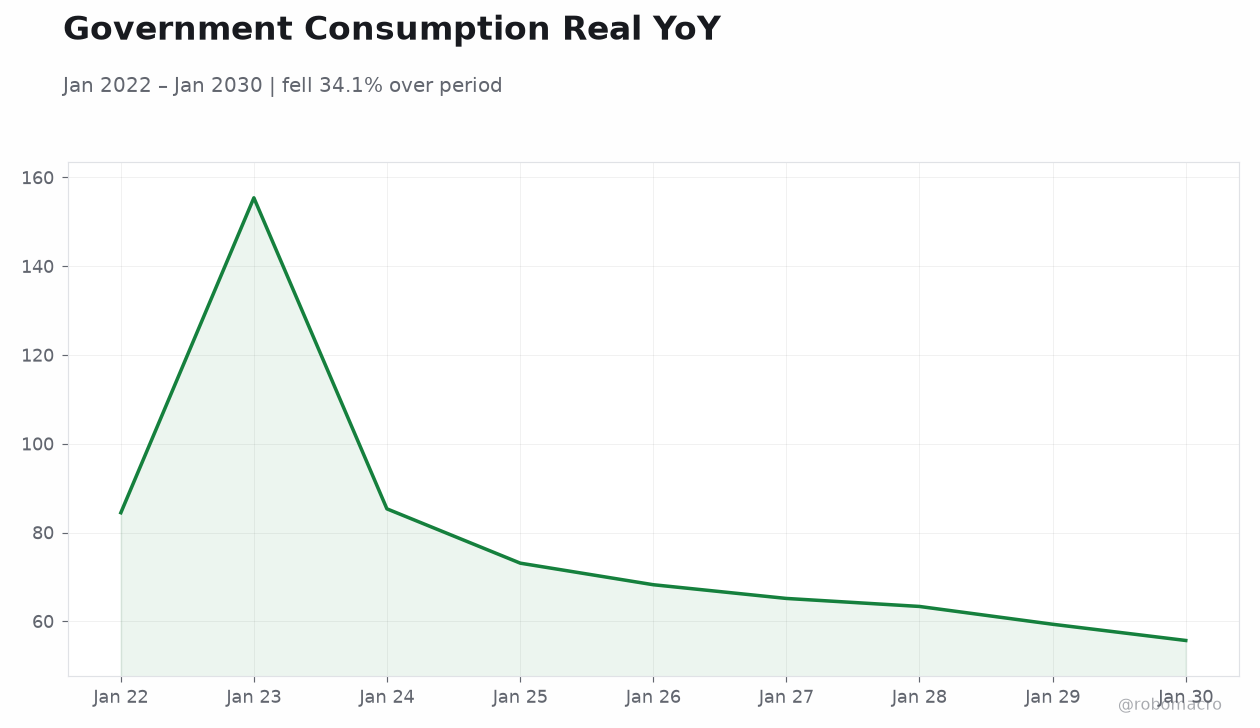
Government Consumption Real YoY Government Consumption Real YoY | Type: macro_line | Government Consumption Real YoY: 55.67 (2030-01-01) | Range: 55.67–155.4 | Trend(5pt): 84.46,85.33,68.23,63.34,55.67
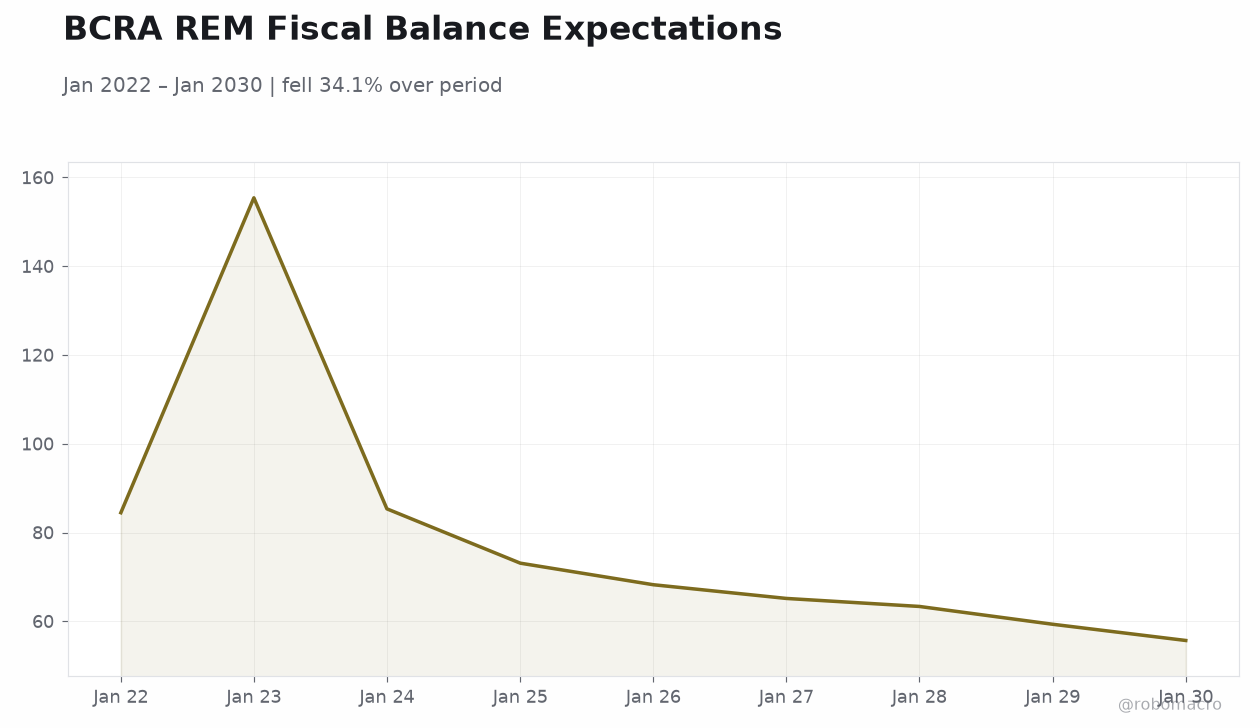
BCRA REM Fiscal Balance Expectations BCRA REM Fiscal Balance Expectations | Type: macro_line | BCRA REM Fiscal Balance Expectations: 55.67 (2030-01-01) | Range: 55.67–155.4 | Trend(5pt): 84.46,85.33,68.23,63.34,55.67
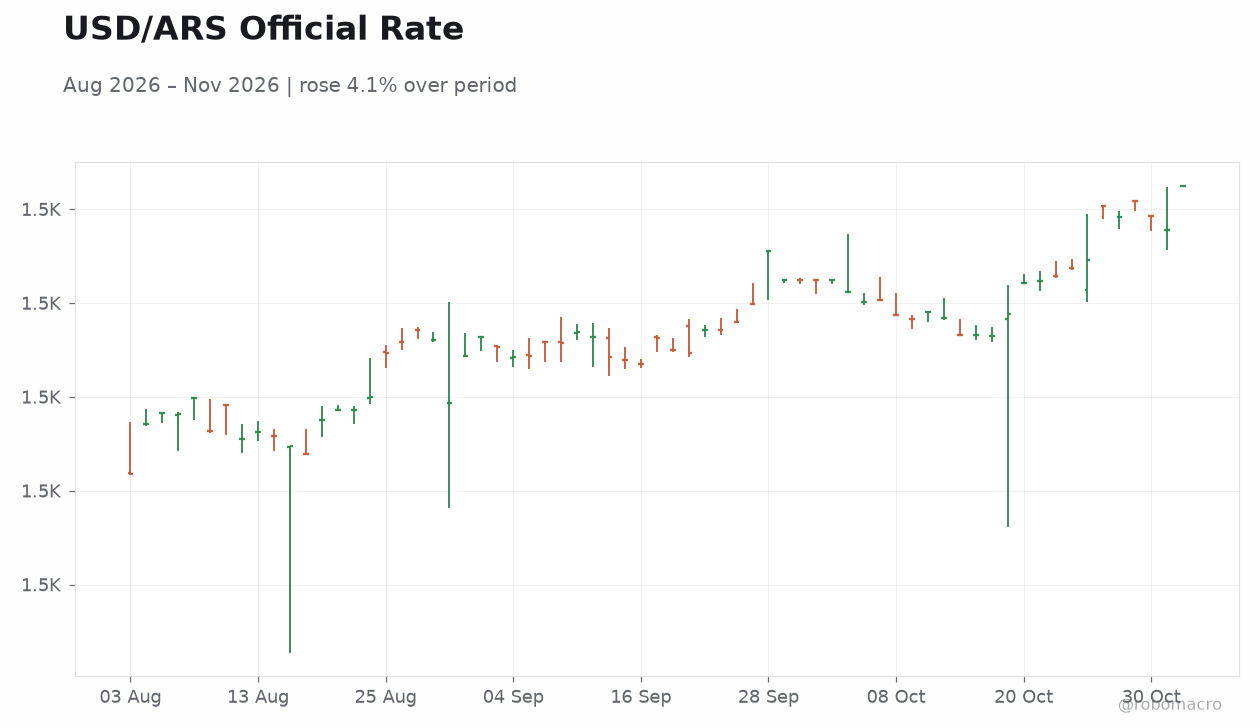
USD/ARS Official Rate USD/ARS Official Rate | Type: market_hloc | USD/ARS: 1545 (2026-11-03) | Range: 1484–1545 | Trend(6pt): 1484,1509,1507,1518,1538,1545

Other Economic Notes (continued)

Fiscal discipline remains the program's cornerstone, yet the social cost is mounting, and any slippage would quickly register in sovereign spreads.

Global Macro News

Australia's central bank lifted its cash rate to an 18-year high, its fifth hike of the year, with the RBA's tightening reinforcing the global "higher-for-longer" theme that keeps EM risk premia elevated. Asian equities traded mostly lower on a tech drag, and UK stocks were set to avoid the worst of the equities selloff, suggesting uneven risk appetite across regions. The Bank of Korea flagged persistent inflationary pressure in personal services and durable goods, while China's central bank shifted its policy-rate anchor to the overnight tenor — a technical change with signaling value for Asian liquidity.

The Irish Examiner's read that central banks are not finished hiking frames the backdrop: tighter global financial conditions raise Argentina's external funding cost and complicate BCRA reserve building. A firmer dollar globally, echoed in Nigerian and Philippine FX commentary, adds to peso pressure. Commodity divergence — Brent up, gold down — shapes Argentina's terms of trade unevenly.

BCRA Watch

The BCRA has not delivered a fresh rate decision in the current window, so markets are operating on the standing guidance embedded in the crawling-peg and reserve-accumulation framework. ↓ p.3

Sponsored by Arbitrage Search
Page 2

Argentina Macro Daily(Beta Mode)

November 03, 2026 robomacro.com

Continuation

BCRA Watch (continued)

With CPI at 33.4% YoY, the policy stance remains restrictive in nominal terms but the crawl continues to deliver gradual nominal peso weakness, which the BCRA has tolerated to preserve competitiveness and support reserve accumulation under the IMF program. The central bank's communication has emphasized fiscal anchor credibility and reserve targets rather than rate signaling, implying the FX path — not the policy rate — is the primary tool for now. For markets, this means the peso's daily crawl is the key observable: a faster crawl signals reserve stress, a slower one signals confidence.

Any shift in reserve targets or intervention language would be the trigger for a repricing in the front end and sovereign curve. Absent new BCRA statements, positioning will stay anchored to the crawl and to IMF program milestones.

Sponsored by Arbitrage Search
Page 3