Argentina Macro Daily(Beta Mode)
Peso Firms as Soy Rally Offsets AI Selloff
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MERVAL | 2,848,945.00 | -0.35% |
| USD/ARS | 1,544.50 | -0.20% |
| EUR/ARS | 1,730.38 | -0.47% |
| Gold | 4,088.20 | -0.62% |
| Brent Crude | 97.87 | -0.43% |
| Soybean | 1,190.25 | +0.78% |
| Bitcoin | 75,997.93 | +0.07% |
| Argentina 10Y | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
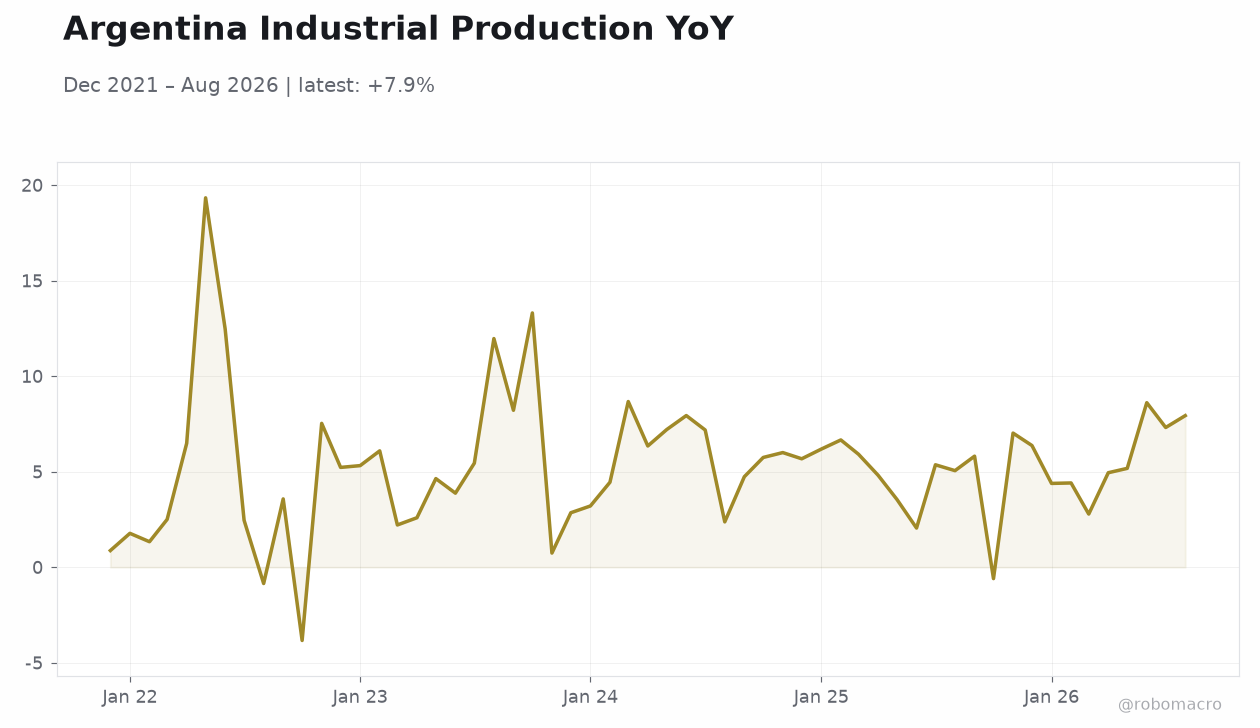 Argentina Industrial Production YoY | Type: macro_line | IP YoY (%): 7.935 (2026-08-01) | Range: -3.835–19.33 | Trend(5pt): 0.8722,6.091,6.346,2.051,7.935
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
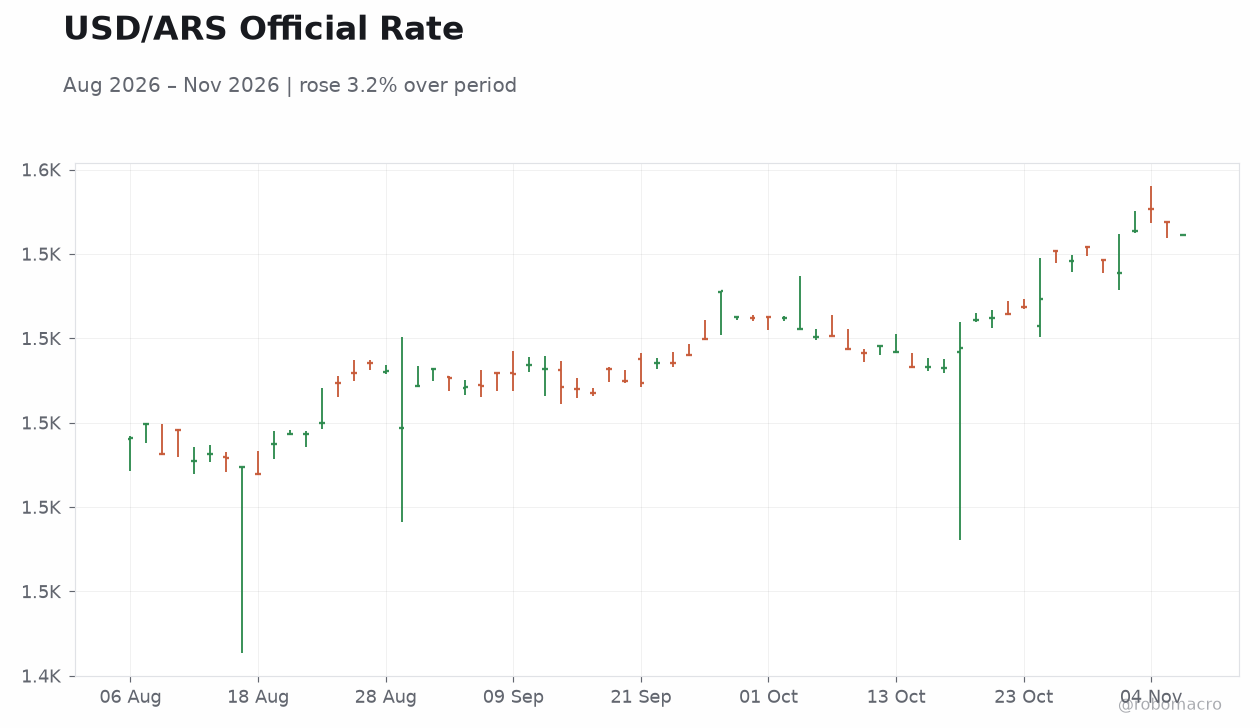
- USD/ARS slipped 0.20% to 1,544.50 while EUR/ARS fell 0.47%, a firmer peso tone despite the global risk-off backdrop.
- Soybeans gained 0.78% to $1,190.25/bu, a supportive signal for Argentina's key export complex and BCRA reserve accumulation.
- MERVAL eased 0.35% to 2,848,945 as the AI-driven equity selloff in Asia and abroad capped local risk appetite.
Yesterday's Recap
Argentina's calendar was empty on November 5, leaving price action to carry the narrative. The peso strengthened modestly, with USD/ARS down 0.20% to 1,544.50 and EUR/ARS off 0.47% to 1,730.38, suggesting steady official-market intervention and export-side supply. Equities lagged, with the MERVAL shedding 0.35% to 2,848,945 as global tech weakness bled into local risk sentiment.
Soybeans rose 0.78% to $1,190.25/bu, a constructive marginal input for the agro-export complex that anchors BCRA reserve builds. Brent crude fell 0.43% to $97.87, trimming imported-energy costs at the margin. Gold dropped 0.62% to $4,088.20, and Bitcoin was essentially flat at 75,997.93.
The Argentina 10Y line showed no quoted level, so no yield move can be reported.
The Day Ahead
No scheduled Argentine data releases appear on the calendar for November 6 or November 7, so the session will be driven by flows and secondary-market pricing. Traders will watch the official FX market for signs of BCRA smoothing and any shift in the crawl, alongside parallel-market spreads. Local equity and bond desks will take direction from the global AI selloff and any stabilization in US risk assets.
Soybean follow-through matters for exporter liquidation and reserve accumulation. With no domestic prints, positioning into next week's data cycle will likely dominate.
Other Economic Notes
Argentina's disinflation path remains the anchor of the macro story, with CPI at 33.4% year-on-year as of September 30, a marked improvement from prior years though still elevated. Fiscal consolidation under the current program continues to underpin the primary-balance target and market credibility. Soybean export receipts are the swing variable for reserve accumulation, and the 0.78% gain offers a modest tailwind.
The peso's firming bias, if sustained, supports the disinflation and reserve objectives simultaneously. Energy import costs remain sensitive to Brent near $98.