Argentina Macro Daily(Beta Mode)
Pope Rebukes Milei as Peso Holds Steady
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| MERVAL | 2,848,945.00 | -0.35% |
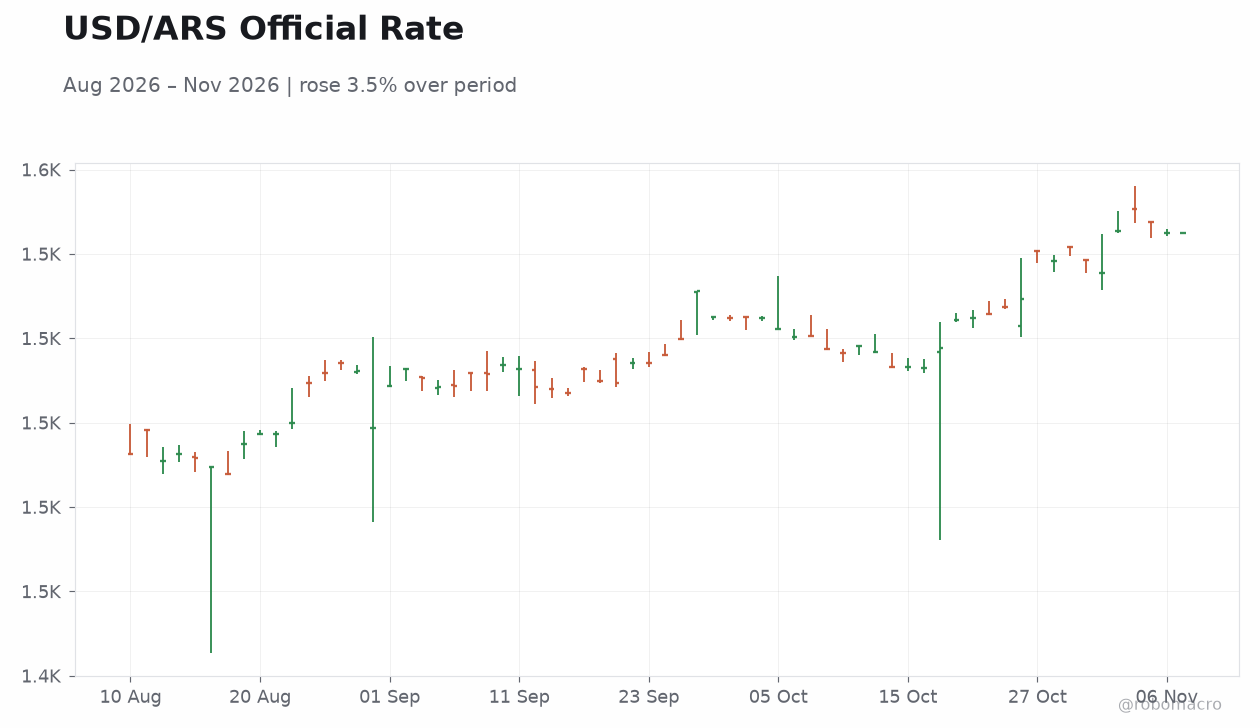
| USD/ARS | 1,545.00 | -0.00% |
| EUR/ARS | 1,723.84 | -0.63% |
| Gold | 4,105.00 | +0.74% |
| Brent Crude | 96.65 | -1.70% |
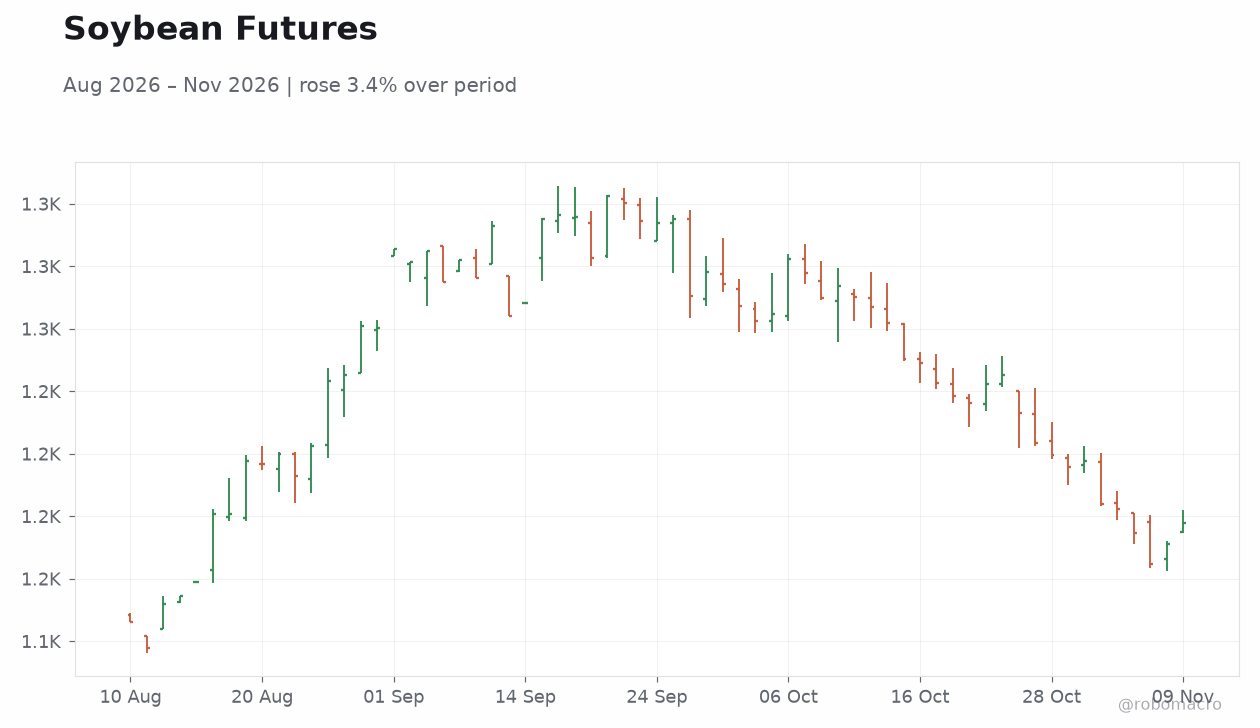
| Soybean | 1,198.00 | +0.76% |
| Bitcoin | 74,356.17 | -0.31% |
| Argentina 10Y | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
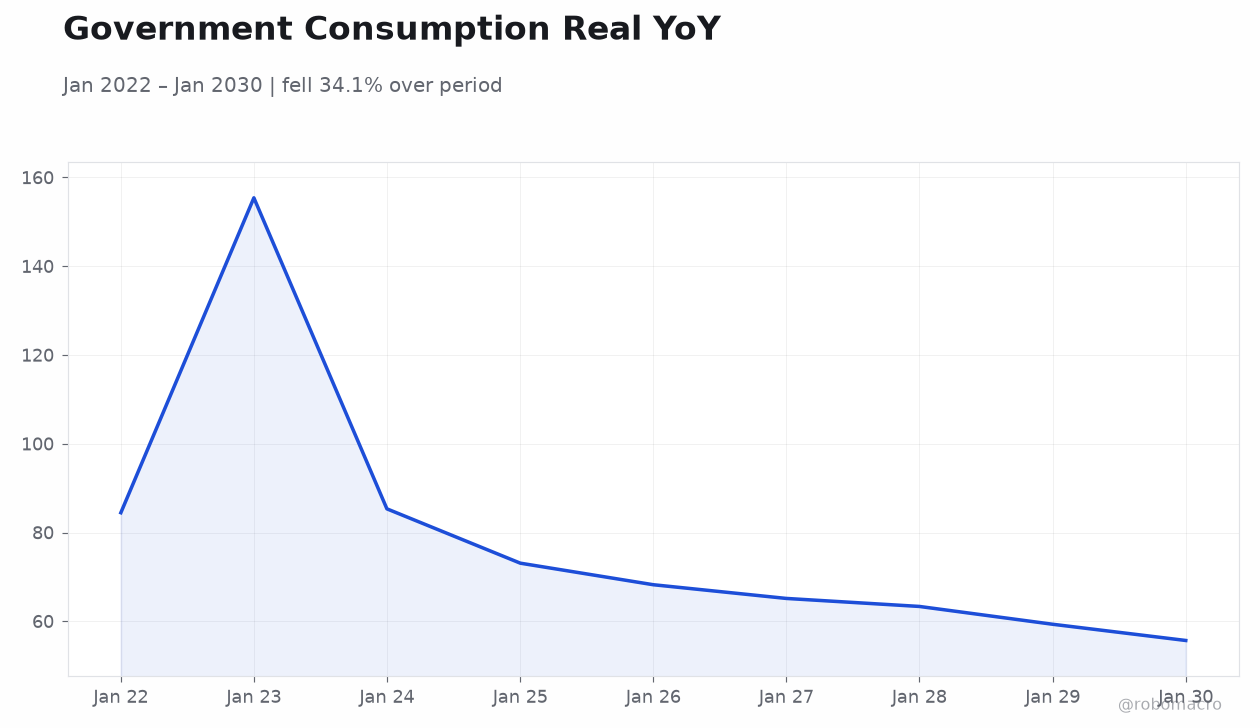
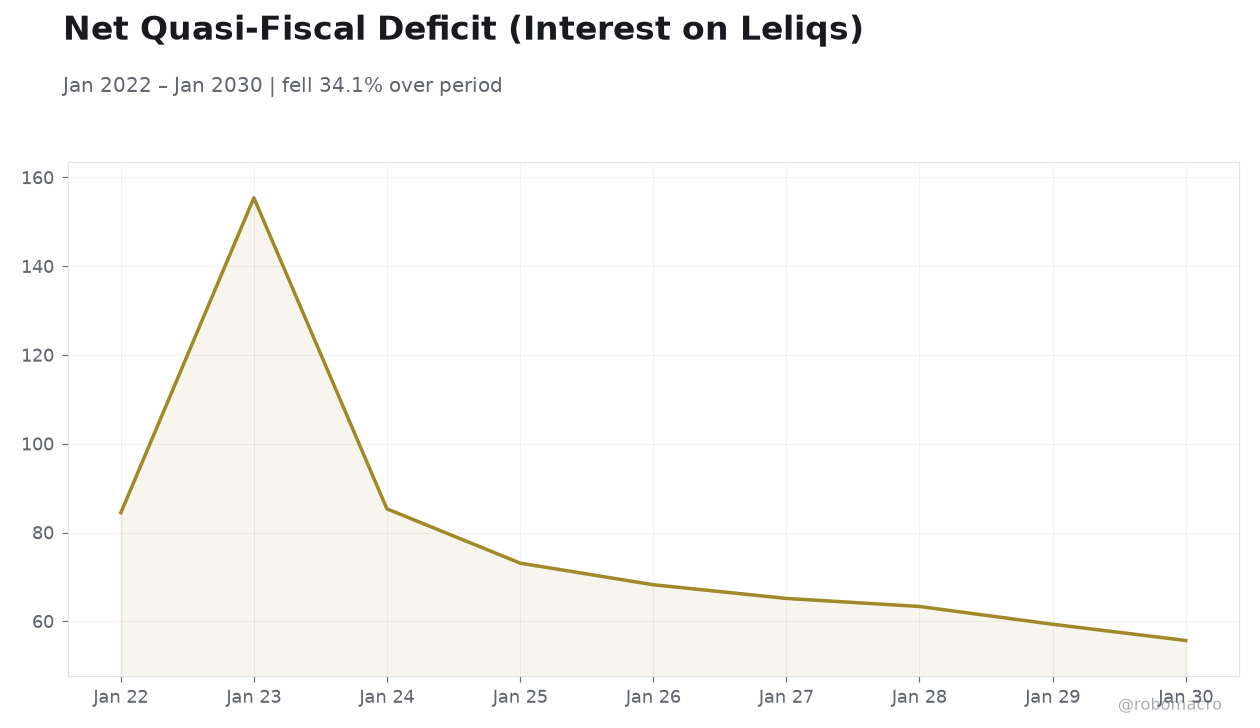 Net Quasi-Fiscal Deficit (Interest on Leliqs) | Type: macro_line | Net Quasi-Fiscal Deficit (Interest on Leliqs): 55.67 (2030-01-01) | Range: 55.67–155.4 | Trend(5pt): 84.46,85.33,68.23,63.34,55.67
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Pope Leo XIV publicly rebukes Milei's austerity program during Argentina visit, injecting political risk into the fiscal consolidation narrative.
- USD/ARS effectively flat at 1,545 while the MERVAL slips 0.35%; hard-currency sovereign curve marks time with no fresh 10Y print.
- BCRA holds a steady hand as regional central banks diverge — Banxico cuts unexpectedly, Chile flags a possible hike.
Yesterday's Recap
Argentina's domestic calendar was empty on Sunday, leaving markets to digest political rather than macroeconomic news. The MERVAL closed at 2,848,945, down 0.35%, a modest risk-off move consistent with the Pope's public criticism of the government's austerity stance. The peso was essentially unchanged, with USD/ARS at 1,545.00 and EUR/ARS easing 0.63% to 1,723.84, suggesting no meaningful official-market pressure.
The Argentina 10Y did not print a fresh level, so the sovereign curve offered no incremental signal. In commodities, soybean gained 0.76% to 1,198.00, a supportive backdrop for the export complex that underpins FX settlement. Brent fell 1.70% to 96.65, trimming some of the energy-import bill but signaling softer global demand expectations.
Gold rose 0.74% to 4,105.00, a reminder that hard-asset demand remains firm even as Argentine local assets tread water.
The Day Ahead
Monday's Argentine calendar is empty, with no scheduled domestic data releases, so price action will be driven by the political narrative around the papal visit and by offshore risk sentiment. Traders will watch the official FX market for any widening of the crawl or intervention signals, and the parallel-market spread for signs of stress. Local equity flows may react to headlines from the Pope's tour, particularly any further commentary on social spending and the pace of adjustment.
With no BCRA communication scheduled, the market will lean on last week's guidance and on the weekly reserve and deposit prints later in the week. Expect thin liquidity and headline-driven volatility rather than data-driven direction.
Other Economic Notes
The disinflation trajectory remains the anchor of the macro story, with CPI at 33.4% year-on-year as of September, a level that keeps real-rate math tight and complicates any premature easing. Fiscal consolidation continues to be the government's central credibility asset, but the Pope's intervention highlights the social durability question that investors increasingly price. Soybean strength is a quiet positive for the export complex and reserve accumulation, though India's oilmeal imports fell 28.5% as soymeal demand shifts toward Brazil and Argentina — a reminder that trade flows are reallocating.
↓ p.2