Brazil Macro Daily(Beta Mode)
Services Stall Precedes COPOM Hold
Market Snapshot
| Asset | Level | Change |
|---|---|---|
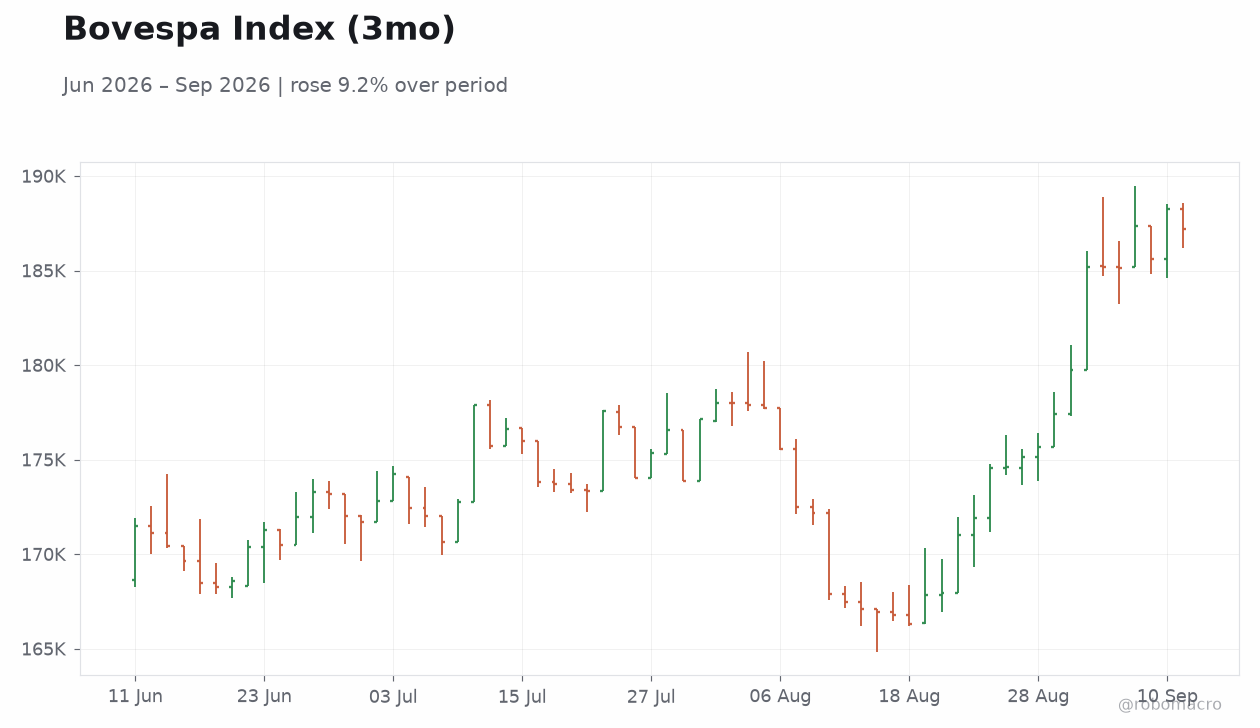
| Bovespa | 187,207.00 | -0.56% |
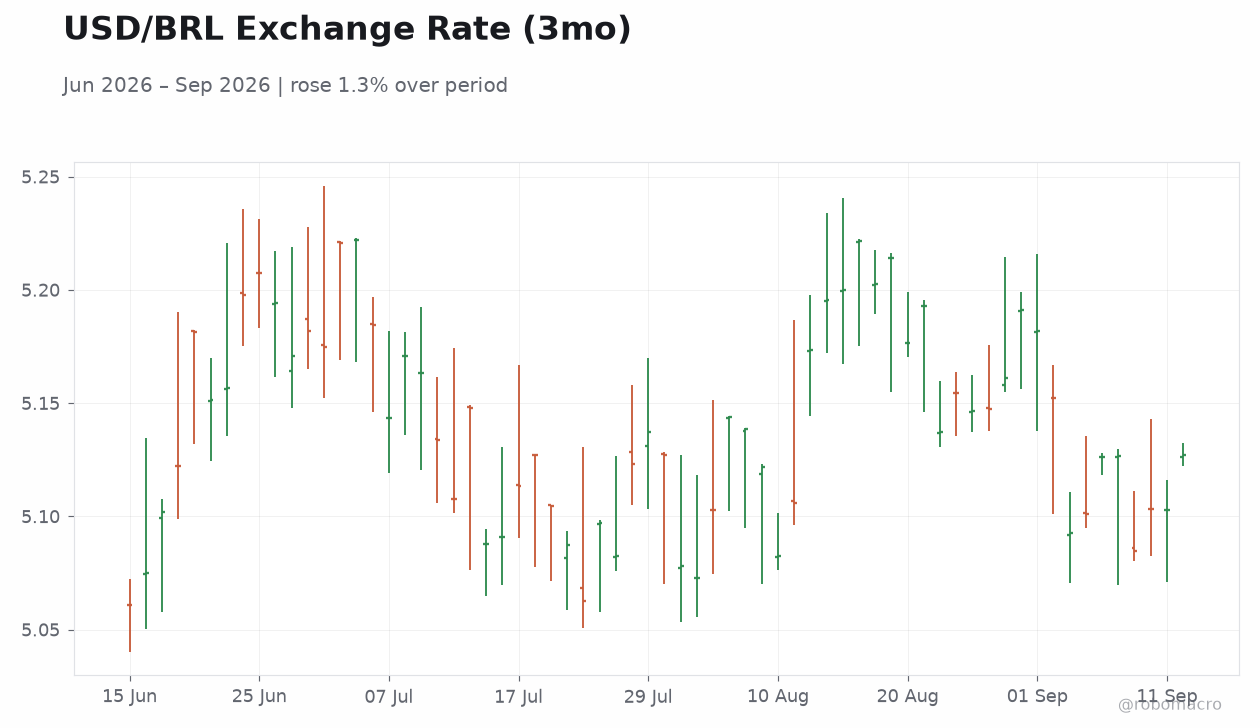
| USD/BRL | 5.13 | +0.47% |
| EUR/BRL | 5.92 | +0.02% |
| Vale | 15.23 | -0.33% |
| Petrobras | 21.20 | -0.84% |
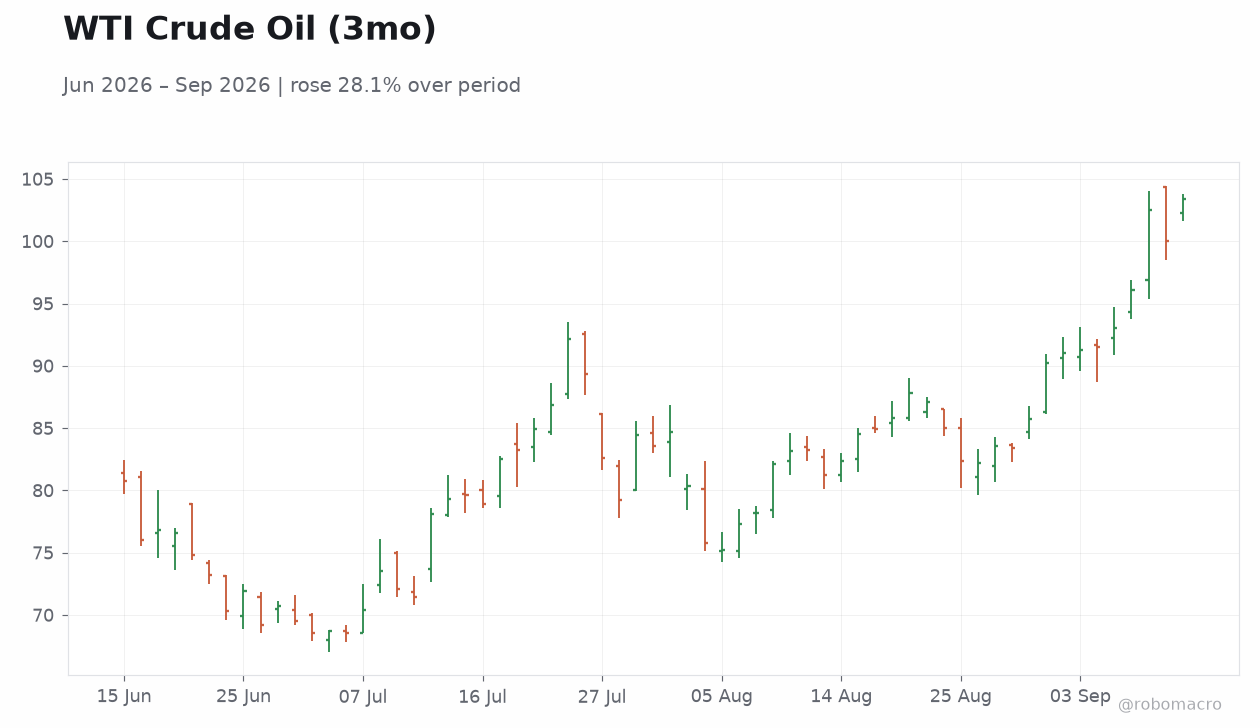
| WTI Crude | 103.27 | +3.22% |
| Gold | 4,347.40 | -0.43% |
| Bitcoin | 77,705.04 | +1.13% |
| Brazil Short-term Rate | 14.39% | -0.76% |
| Brazil Long-term Rate | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
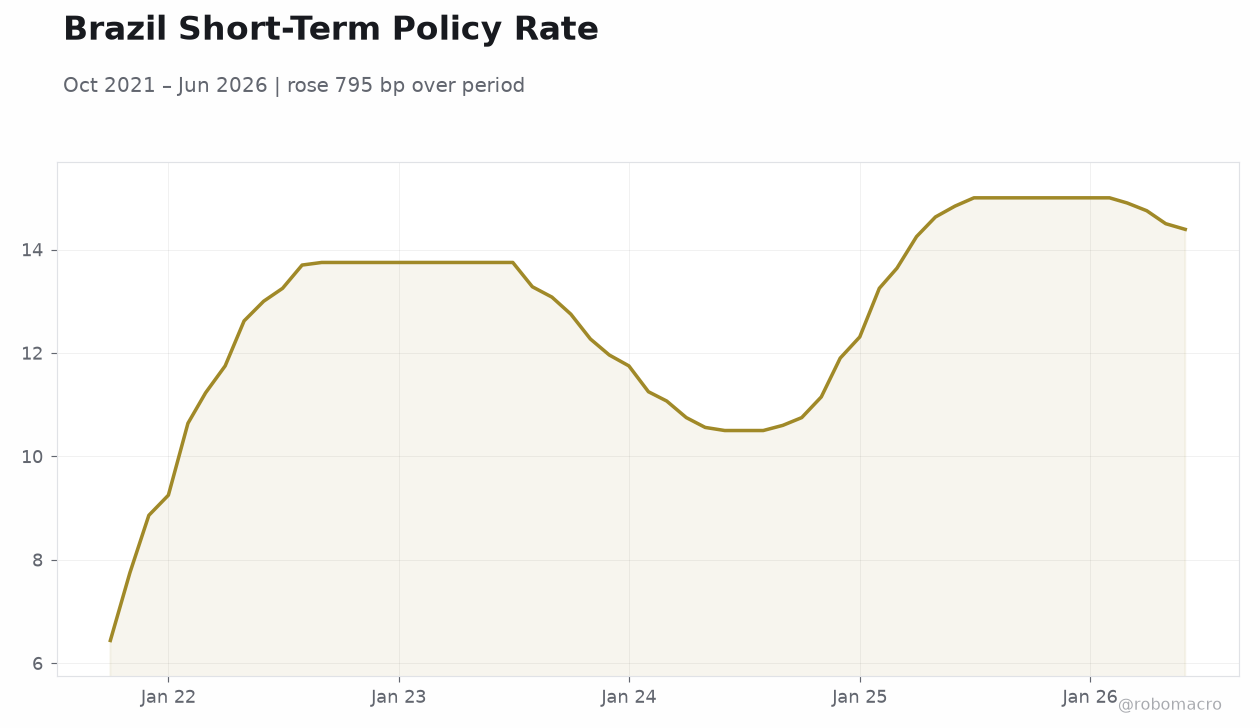 Brazil Short-Term Policy Rate | Type: macro_line | Policy Rate %: 14.39 (2026-06-01) | Range: 6.44–15 | Trend(5pt): 6.44,13.75,11.25,14.25,14.39
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Business Confidence | 46.30 | - | 10:00 |
| Tuesday (2026-09-15) | |||
| Retail Sales Month-over-Month | 0.50 | - | 08:00 |
| Wednesday (2026-09-16) | |||
| Central Bank Interest Rate Decision | 14 | - | 17:30 |
- Brazil services sector stalled in July, signaling gradual slowdown ahead of key policy meeting.
- Bovespa fell 0.56% to 187,207 while USD/BRL rose 0.47% to 5.13 on commodity volatility.
- COPOM set to hold Selic at 14.00% Wednesday after Business Confidence release today.
Yesterday's Recap
No economic data releases occurred on September 13. Bovespa closed at 187,207.00, down 0.56 percent, with Vale falling 0.33 percent to 15.23 and Petrobras declining 0.84 percent to 21.20. USD/BRL climbed 0.47 percent to 5.13 while EUR/BRL edged up 0.02 percent to 5.92.
WTI Crude surged 3.22 percent to 103.27, supporting energy names, yet gold slipped 0.43 percent to 4,347.40. Bitcoin rose 1.13 percent to 77,705.04. Brazil short-term rate eased 0.76 percent to 14.39 percent.
The services sector stall headline from July data weighed on sentiment without triggering sharp moves in equities or FX.
The Day Ahead
Business Confidence prints at 10:00 ET today with the prior reading at 46.3, offering an early gauge of corporate sentiment before the COPOM decision. Retail Sales MoM data arrive tomorrow at 08:00 ET against a 0.5 percent prior. The September 16 COPOM meeting at 17:30 ET carries the highest market impact, with the committee expected to hold the Selic rate at the 14.00 percent level established in August.
Markets will parse any fresh forward guidance on inflation targeting and fiscal risks. Iron ore and oil price swings will continue to influence Vale and Petrobras performance.
Other Economic Notes
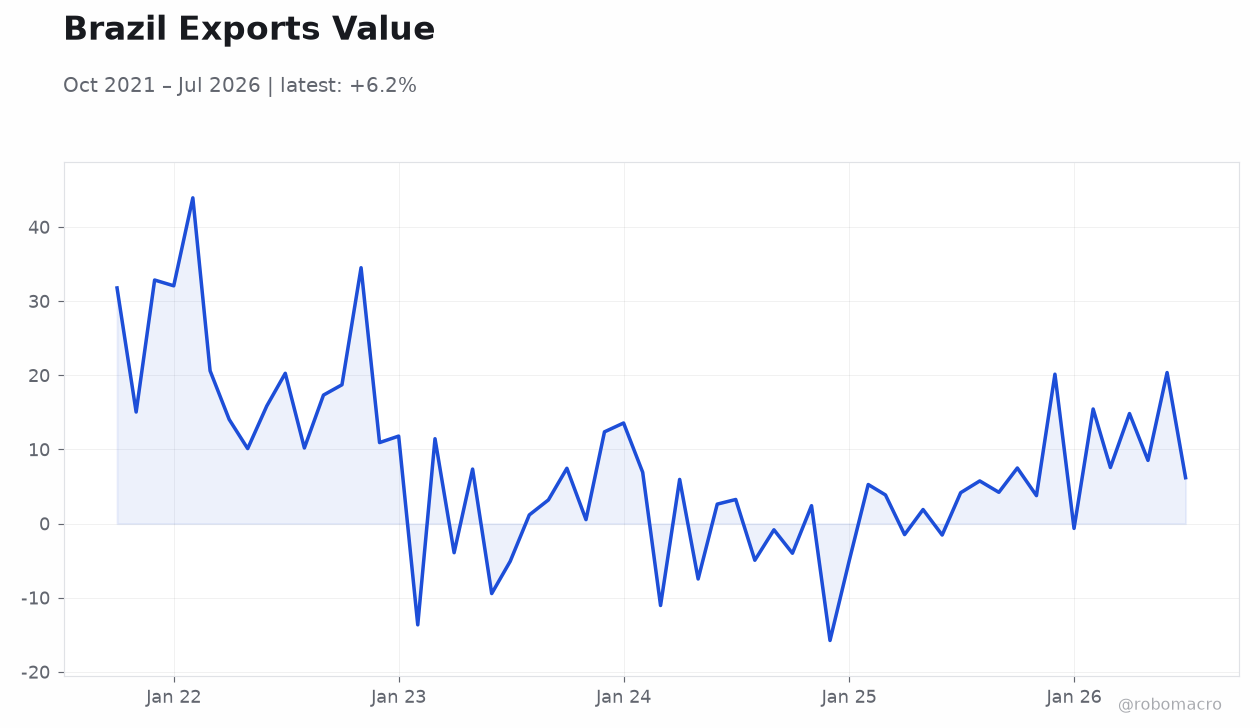
July services data point to a cooling expansion that aligns with slower domestic demand and tighter financial conditions. A domestic financial scandal has added political uncertainty, potentially complicating fiscal consolidation efforts ahead of the 2026 election cycle. Commodity export revenues remain supported by elevated WTI prices above 100 dollars, yet iron ore margins face pressure from weak Chinese steel output.
Fiscal sustainability concerns persist as policymakers balance social spending with debt stabilization targets. These themes will shape investor positioning around the upcoming COPOM decision.
Global Macro News
G7 central banks are advancing toward synchronized rate hikes, with the Federal Reserve decision on Wednesday setting the tone for global yields and emerging-market flows. ↓ p.2