Brazil Macro Daily(Beta Mode)
COPOM Poised for 25bp Cut as Confidence Slips
Market Snapshot
| Asset | Level | Change |
|---|---|---|
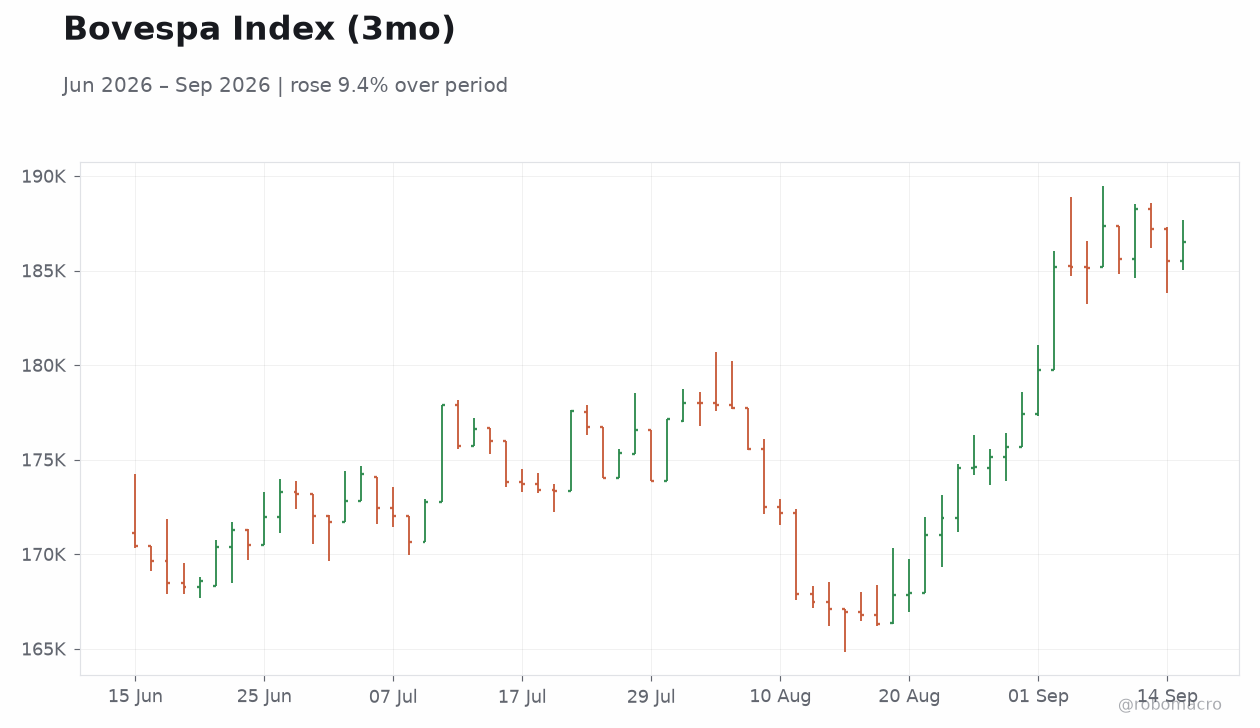
| Bovespa | 186,503.00 | +0.54% |
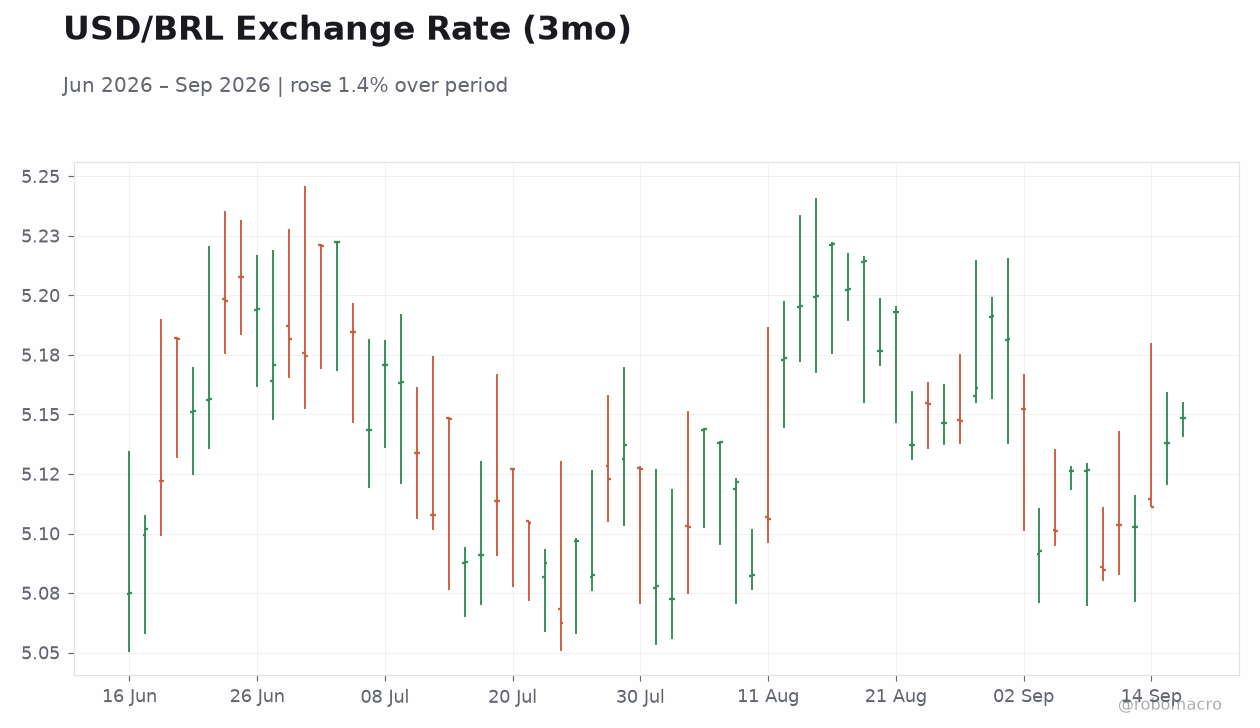
| USD/BRL | 5.15 | +0.21% |
| EUR/BRL | 5.94 | +0.29% |
| Vale | 14.47 | -0.96% |
| Petrobras | 21.77 | +2.93% |
| WTI Crude | 104.51 | -1.25% |
| Gold | 4,368.80 | +0.83% |
| Bitcoin | 75,779.99 | +0.22% |
| Brazil 5Y Govt Yield | 14.25% | +3 bp |
| Brazil 10Y Govt Yield | 14.38% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Business Confidence | 46.30 | - | 44.90 |
| Retail Sales Month-over-Month | 0.50 | -0.20 | - |
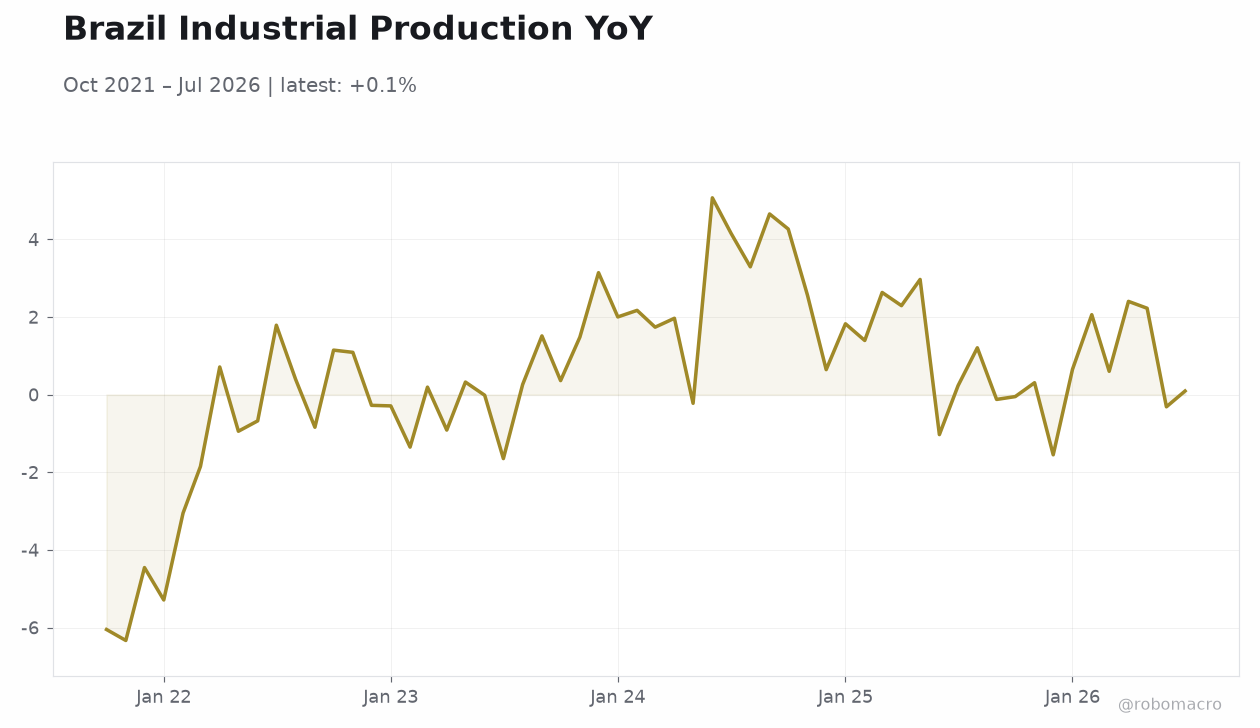 Brazil Industrial Production YoY | Type: macro_line | IP YoY %: 0.09432 (2026-07-01) | Range: -6.332–5.071 | Trend(6pt): -6.05,-0.2749,2.172,2.293,-0.3129,0.09432
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-16) | |||
| Central Bank Interest Rate Decision | 14 | 13.75 | 13:30 |
- Business confidence fell to 44.9 in September, extending the prior decline.
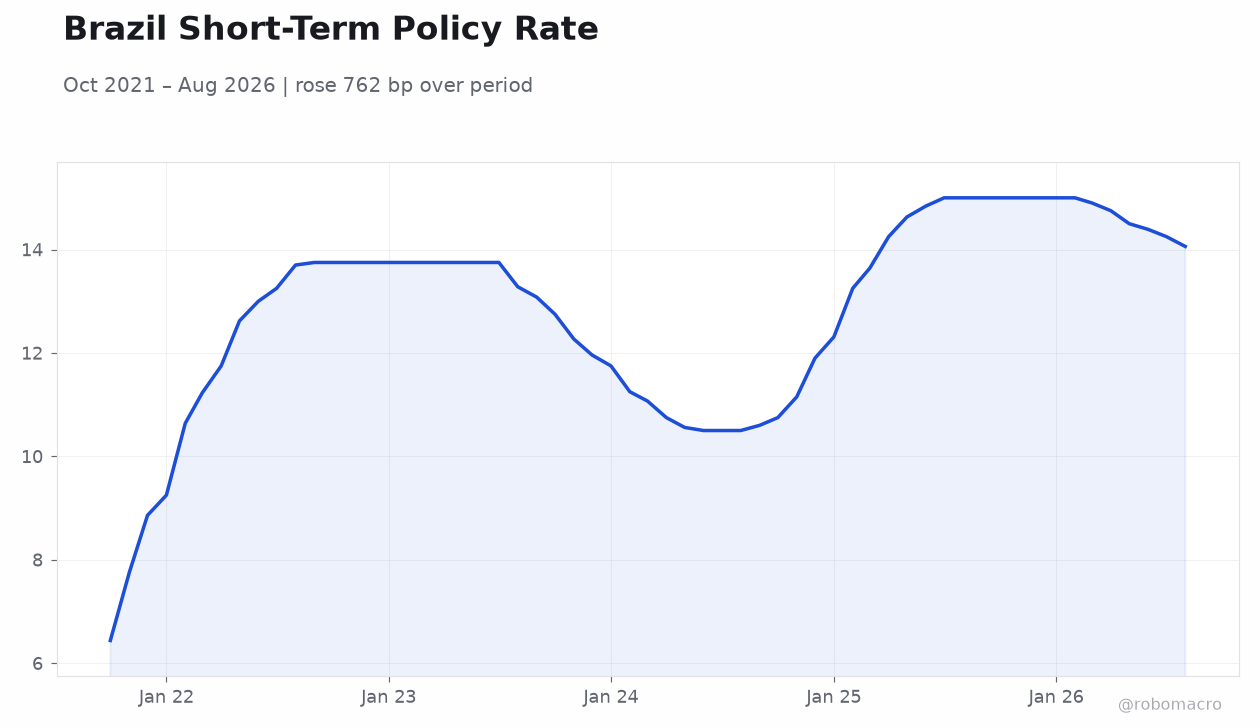
- COPOM is expected to lower the Selic rate by 25 bp to 13.75% today.
- Bovespa rose 0.54% while the real weakened and yields climbed modestly.
Yesterday's Recap
Brazilian business confidence dropped to 44.9 from 46.3, signaling softer sentiment ahead of the policy meeting. Retail sales month-over-month data were not released, leaving the prior 0.5% gain as the last benchmark. Equity markets closed higher, with the Bovespa advancing 0.54% to 186,503.
Petrobras shares gained 2.93% to 21.77 while Vale fell 0.96% to 14.47. The real depreciated, with USD/BRL rising 0.21% to 5.15 and EUR/BRL up 0.29% to 5.94. Government yields increased, the 5-year rising 3 bp to 14.25% and the 10-year adding 5 bp to 14.38%.
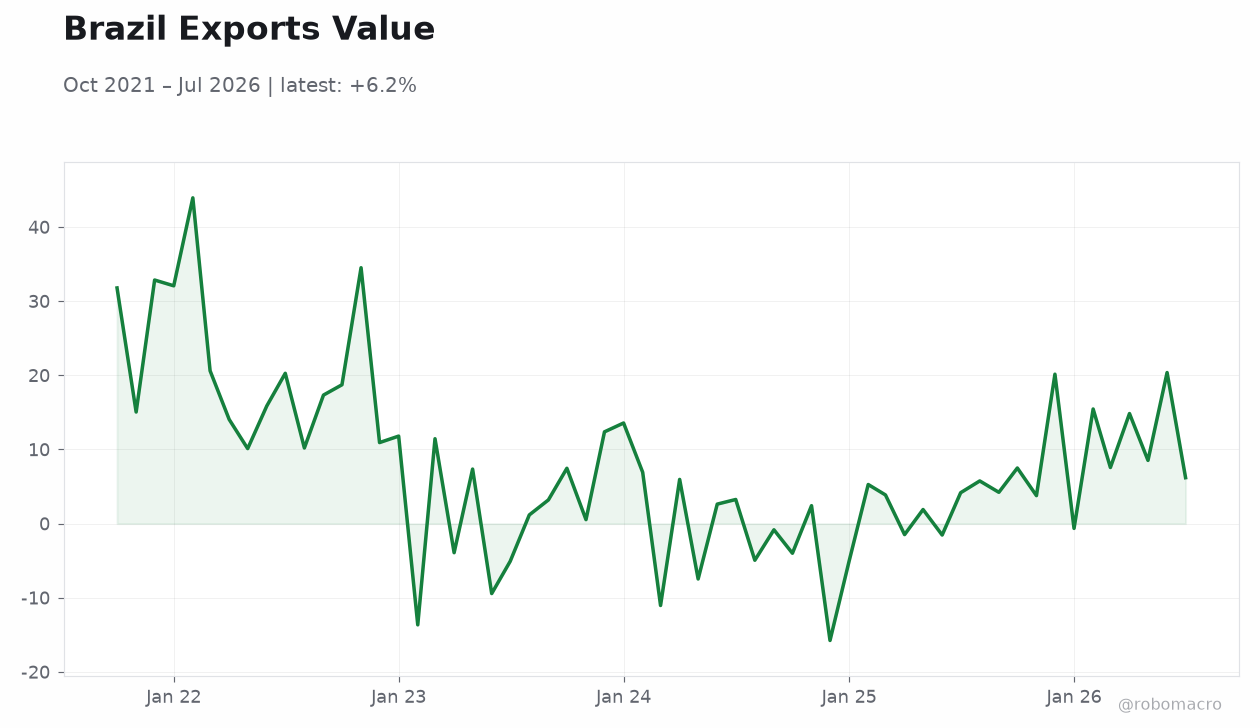
Coffee export volumes jumped in early September according to official figures, providing a modest positive for trade data.
The Day Ahead
Markets will focus on the COPOM interest-rate decision scheduled for 13:30 ET. Consensus forecasts a 25 bp reduction that would bring the Selic rate to 13.75% from the current 14.00%. No other high-impact Brazilian releases are listed for the session.
Attention will center on the accompanying statement for any signals on the pace of subsequent easing. Currency and fixed-income markets are likely to react immediately to the size of the cut and forward guidance. Equity trading may remain sensitive to commodity price moves given the weight of resource names in the Bovespa.
Other Economic Notes
Brazil’s main opposition candidate has signaled interest in adopting elements of Argentina’s Milei reform agenda, raising the prospect of sharper fiscal and regulatory changes if the political landscape shifts. A tight presidential race between Lula and Bolsonaro continues to dominate headlines, with polls showing a near dead-heat and a supreme court dispute adding legal uncertainty. Fiscal sustainability remains under scrutiny as debt-service costs stay elevated at current yield levels.
Commodity export strength, particularly coffee and iron ore, continues to support the external accounts despite softer domestic confidence readings.