RoboMacro Research

Brazil Macro Daily(Beta Mode)

September 18, 2026 robomacro.com

Selic Cut to 13.75% as Retail Sales Contract

44.90 Business Confidence-0.80 Retail Sales13.75 Central Bank Interest
Bovespa185,992.00+0.24%
USD/BRL5.13-0.42%
EUR/BRL5.89-0.25%
Vale14.47+2.41%

Market Snapshot

AssetLevelChange
Bovespa185,992.00+0.24%
USD/BRL5.13-0.42%
EUR/BRL5.89-0.25%
Vale14.47+2.41%
Petrobras20.94+0.14%
WTI Crude95.51-6.28%
Gold4,430.10+0.69%
Bitcoin78,279.91+2.46%
Brazil 5Y Govt Yield14.20%+6 bp
Brazil 10Y Govt Yield14.37%+6 bp

Prior Economic Events

Data Prior Cons Actual
Business Confidence46.30-44.90
Retail Sales Month-over-Month0.50-0.20-0.80
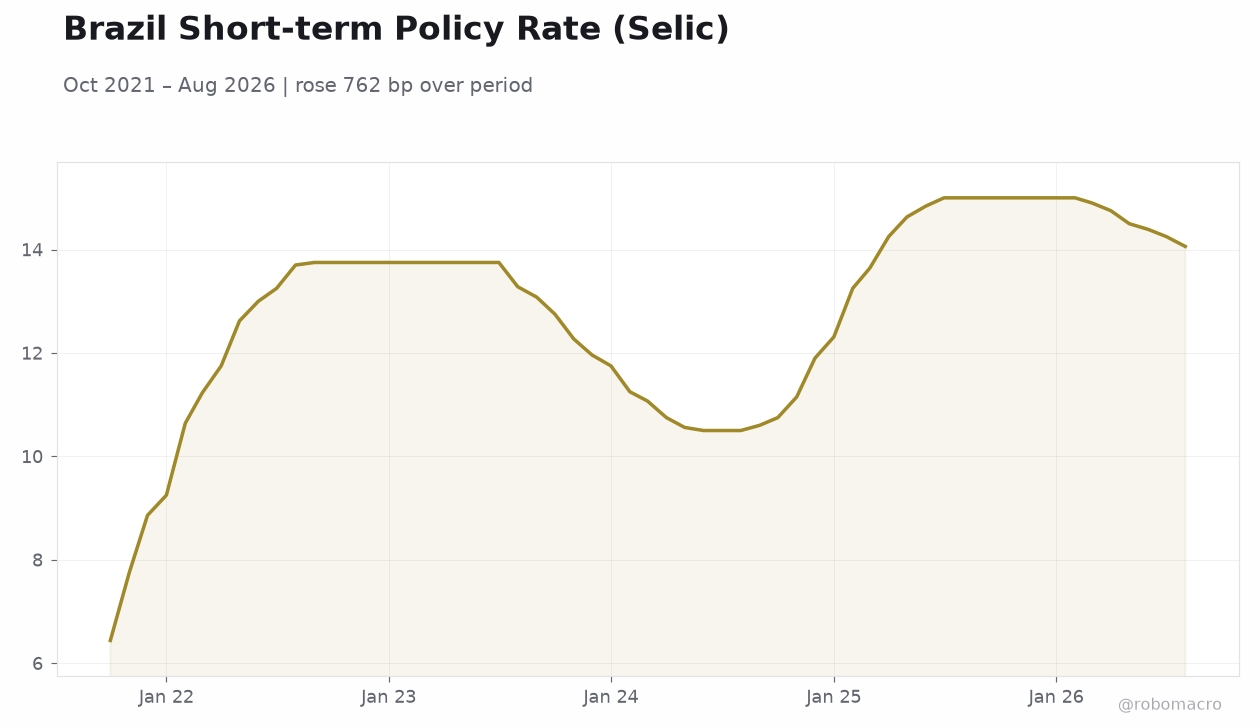
Central Bank Interest Rate Decision1413.7513.75
Brazil Short-term Policy Rate (Selic)Brazil Short-term Policy Rate (Selic) | Type: macro_line | Percent: 14.06 (2026-08-01) | Range: 6.44–15 | Trend(6pt): 6.44,13.75,11.25,14.25,14.39,14.06

Today's Economic Events

Data Prior Cons Time
No events available
  • BCB delivers expected 25 bp Selic cut to 13.75% while retail sales miss sharply
  • Business confidence falls to 44.9 and Bovespa edges up 0.24% with real strengthening
  • 5-year and 10-year yields each rise 6 bp to 14.20% and 14.37% post-decision

Yesterday's Recap

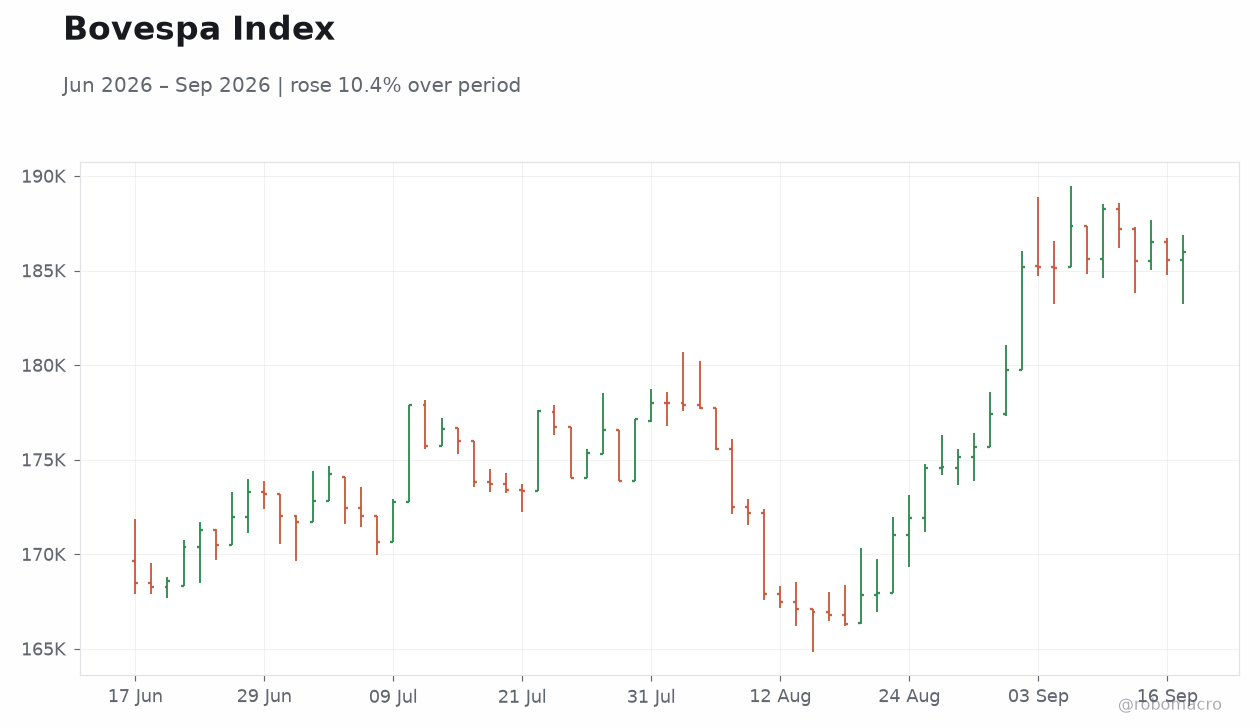
Brazil’s retail sales contracted 0.8% month-over-month in August, worse than the -0.2% consensus and reversing the prior 0.5% gain, while business confidence slipped to 44.9 from 46.3. The COPOM cut the Selic rate by 25 bp to 13.75%, matching the unanimous market expectation and the prior 14.00% level. Bovespa closed at 185,992, up 0.24%, led by Vale’s 2.41% gain to 14.47 on firmer iron-ore prices, while Petrobras added 0.14% to 20.94.

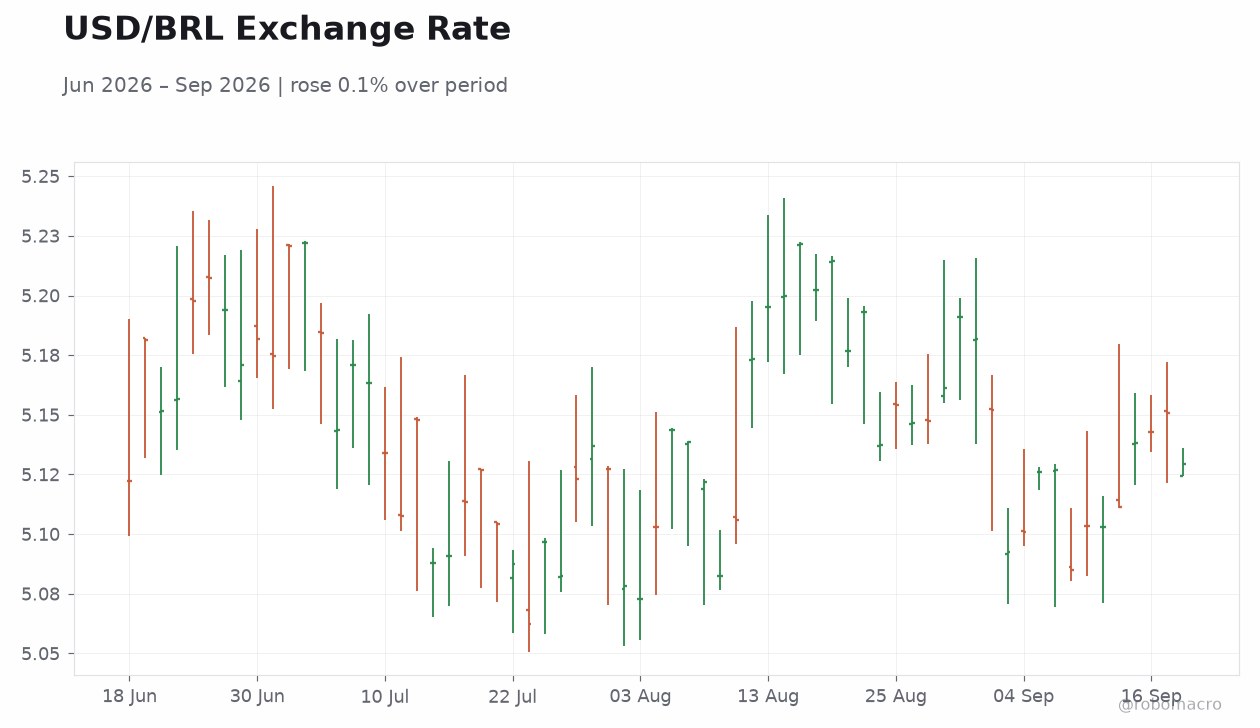
USD/BRL fell 0.42% to 5.13 and EUR/BRL declined 0.25% to 5.89, reflecting modest real appreciation after the policy decision. Brazil’s 5-year government yield rose 6 bp to 14.20% and the 10-year yield also added 6 bp to 14.37%, indicating markets priced the cut as the start of a measured easing cycle rather than an aggressive one. WTI crude dropped 6.28% to 95.51, weighing on energy-related names, while gold and Bitcoin posted modest gains.

The combination of weaker activity data and the anticipated rate cut left local assets mixed but supported by the predictable policy outcome.

The Day Ahead

No Brazilian economic releases or BCB events are scheduled for 18 September, leaving markets to digest yesterday’s data and the COPOM decision. Attention will turn to external drivers, including iron-ore and oil price movements that directly affect Vale and Petrobras earnings. Fiscal developments surrounding President Lula’s announced welfare increases may also draw scrutiny for their potential impact on the primary balance and debt trajectory.

With the Selic path now anchored at 13.75%, investors will monitor incoming inflation prints and activity indicators for signals on the pace of further cuts. The empty domestic calendar should keep volatility contained unless global risk sentiment shifts materially.

Other Economic Notes

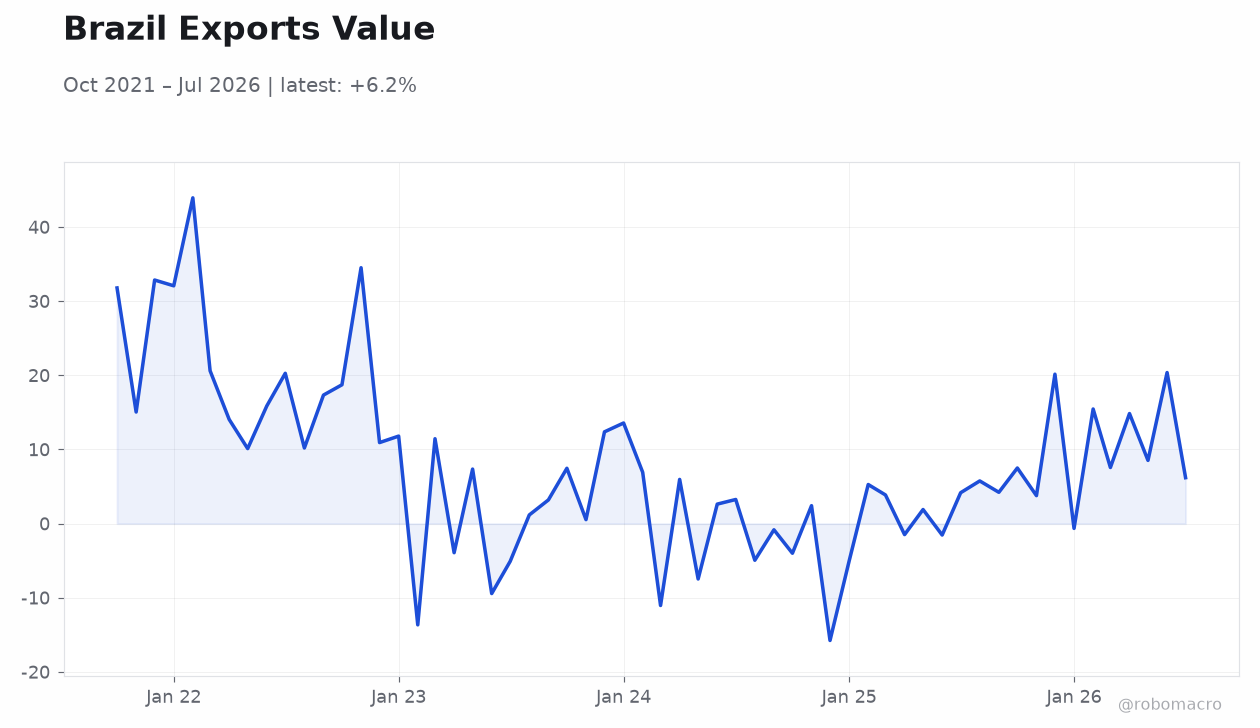
President Lula’s pre-election welfare increases add to already elevated fiscal spending, raising questions about medium-term debt sustainability at a time when yields remain above 14%. Commodity export revenues continue to anchor the external accounts, with iron ore and oil prices directly influencing both the trade balance and BRL valuation. ↓ p.2
Page 1

Brazil Macro Daily(Beta Mode)

September 18, 2026 robomacro.com
Brazil Exports Value Brazil Exports Value | Type: macro_line | USD Million: 6.195 (2026-07-01) | Range: -15.76–43.94 | Trend(6pt): 31.79,10.93,6.929,-1.479,20.38,6.195
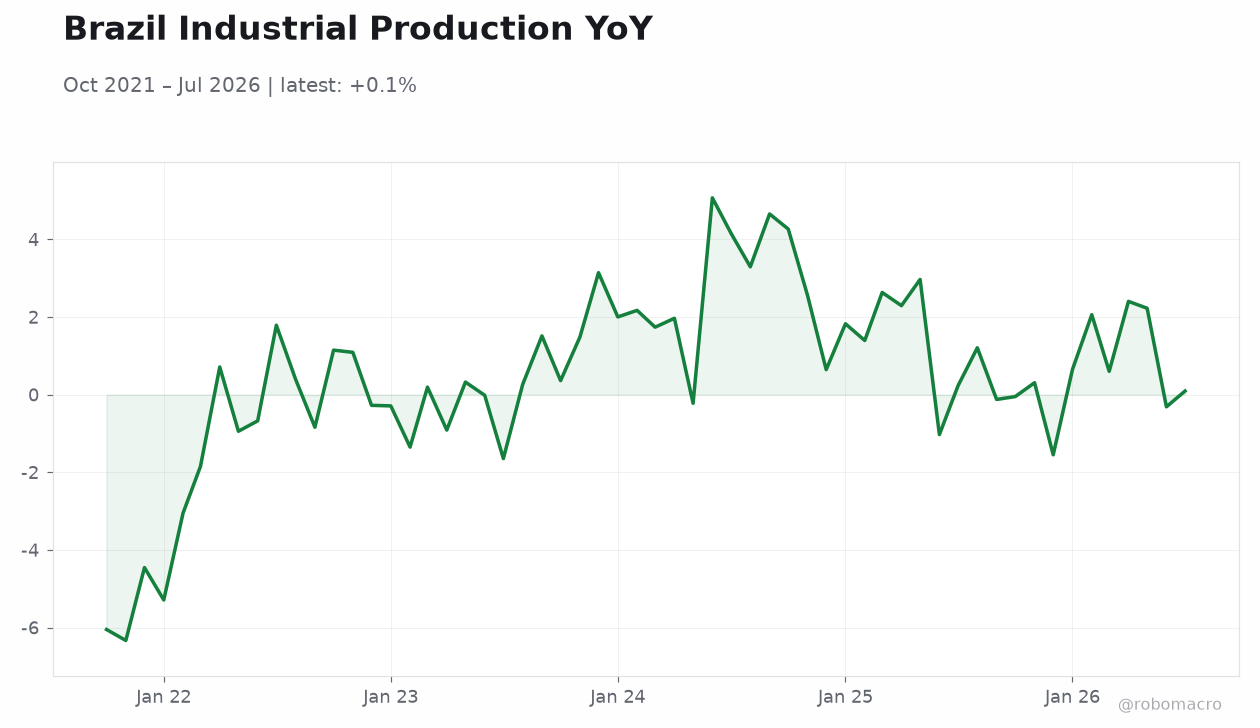
Brazil Industrial Production YoY Brazil Industrial Production YoY | Type: macro_line | YoY %: 0.09432 (2026-07-01) | Range: -6.332–5.071 | Trend(6pt): -6.05,-0.2749,2.172,2.293,-0.3129,0.09432
USD/BRL Exchange Rate USD/BRL Exchange Rate | Type: market_hloc | BRL per USD: 5.129 (2026-09-18) | Range: 5.062–5.222 | Trend(6pt): 5.122,5.134,5.073,5.154,5.143,5.129
Bovespa Index Bovespa Index | Type: market_hloc | Index Level: 1.86e+05 (2026-09-17) | Range: 1.663e+05–1.883e+05 | Trend(6pt): 1.685e+05,1.727e+05,1.78e+05,1.719e+05,1.855e+05,1.86e+05

Other Economic Notes (continued)

Lower Selic levels should gradually ease credit costs for households and firms, yet the weak retail sales print underscores that transmission to domestic demand may take several quarters. Fiscal slippage risks could limit the scope for deeper rate cuts if inflation expectations begin to reprice higher. Overall, the combination of easing monetary policy and rising social transfers points to a growth-supportive but fiscally looser policy mix through year-end.

Global Macro News

Iron ore futures posted a weekly gain despite subdued Chinese steel demand, supporting Brazilian mining revenues and Vale’s equity performance. BRICS-related commentary highlighted ongoing discussions around alternative payment mechanisms that could eventually reduce reliance on the USD for Brazilian commodity exports. Global carry-trade unwind pressures, flagged by Asian central banks, contributed to selective emerging-market currency strength, aiding the BRL’s 0.42% advance.

Oil-price weakness weighed on Petrobras but also tempered imported inflation risks for Brazil. Broader risk-on sentiment in equities, visible in Bitcoin’s 2.46% rise, spilled over modestly into Bovespa. US policy signals on Russian oil sanctions added volatility to energy markets, indirectly affecting Brazilian export pricing.

These external factors collectively reinforced a constructive backdrop for Brazilian assets following the Selic decision.

Sponsored by Arbitrage Search
Page 2

Brazil Macro Daily(Beta Mode)

September 18, 2026 robomacro.com

Continuation

BCB Watch

The COPOM reduced the Selic rate to 13.75% from 14.00%, aligning precisely with consensus and confirming the committee’s assessment that inflation dynamics permit gradual easing. Post-meeting, both the 5-year and 10-year yields rose 6 bp, signaling that markets interpreted the move as the beginning of a measured cycle rather than an aggressive front-loaded adjustment. The real appreciated against the dollar, consistent with a dovish-yet-predictable policy shift that reduced carry-trade unwind risks.

No vote split was disclosed, and no additional BCB speeches occurred to alter forward guidance. Future rate decisions will hinge on incoming inflation and activity data, with the weaker retail sales and confidence readings reinforcing the case for continued easing provided fiscal risks remain contained. The framework remains focused on the inflation target, and the initial 25 bp cut leaves room for further adjustments if price pressures continue to moderate.

Sponsored by Arbitrage Search
Page 3