Brazil Macro Daily(Beta Mode)
Copom Minutes in Focus as Yields Rise
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 186,596.00 | +0.74% |
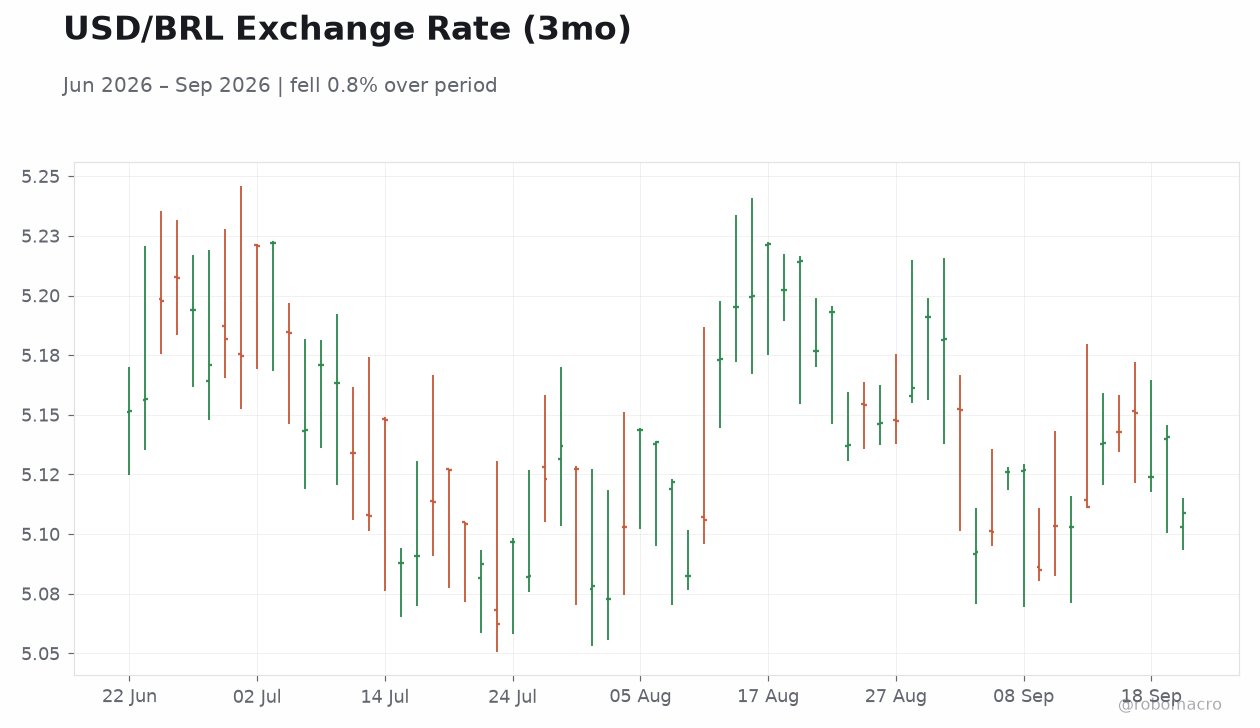
| USD/BRL | 5.11 | -0.62% |
| EUR/BRL | 5.85 | -0.80% |
| Vale | 14.15 | -0.42% |
| Petrobras | 20.63 | -0.82% |
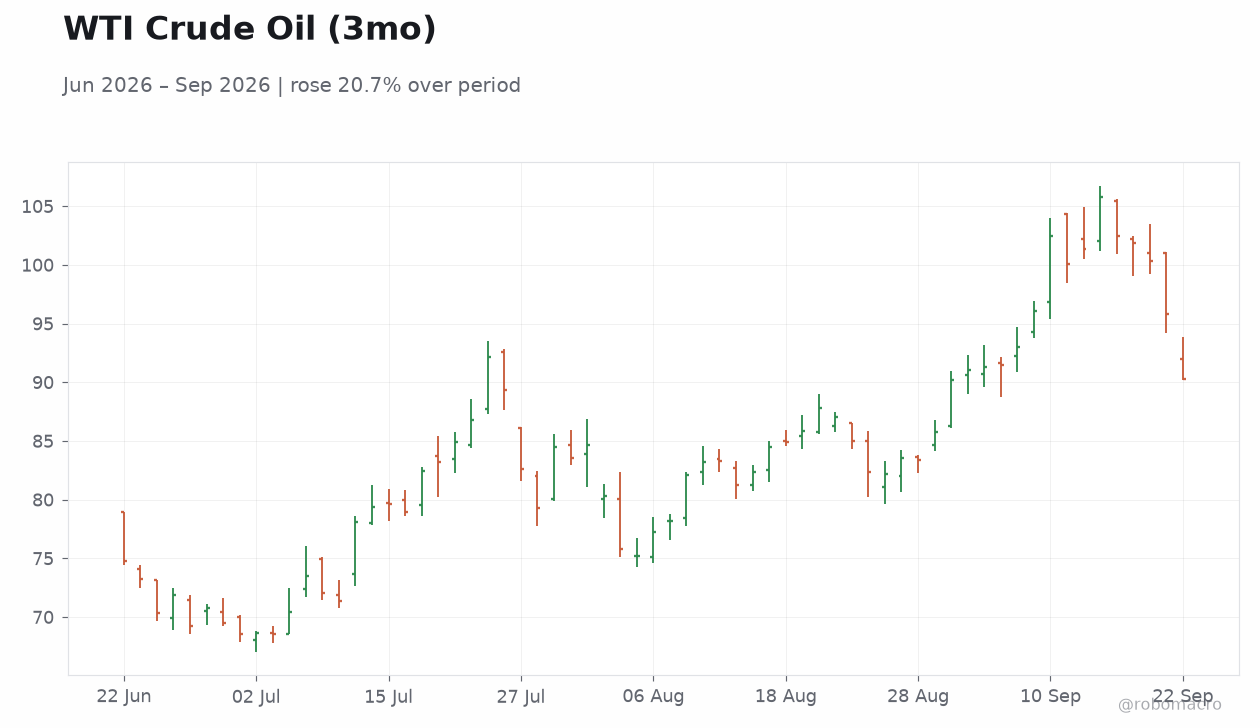
| WTI Crude | 90.49 | -5.52% |
| Gold | 4,369.90 | -0.32% |
| Bitcoin | 85,806.30 | -0.92% |
| Brazil 5Y Govt Yield | 14.11% | +3 bp |
| Brazil 10Y Govt Yield | 14.25% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
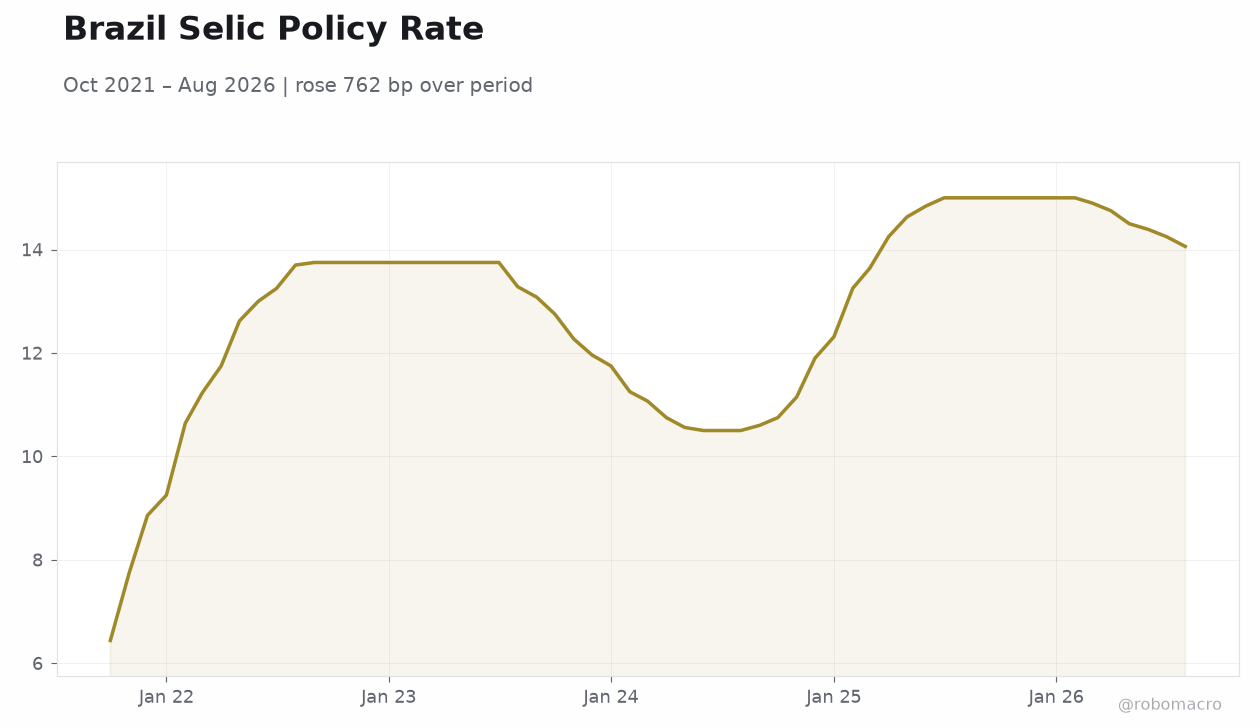 Brazil Selic Policy Rate | Type: macro_line | Policy Rate %: 14.06 (2026-08-01) | Range: 6.44–15 | Trend(6pt): 6.44,13.75,11.25,14.25,14.39,14.06
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BCB Copom Meeting Minutes | - | - | 03:00 |
- Bovespa gains 0.74% while BRL strengthens against USD
- Brazilian states projected to post R$37bn primary deficit in 2026
- BCB Copom minutes release today with Selic held at 14.00%
Yesterday's Recap
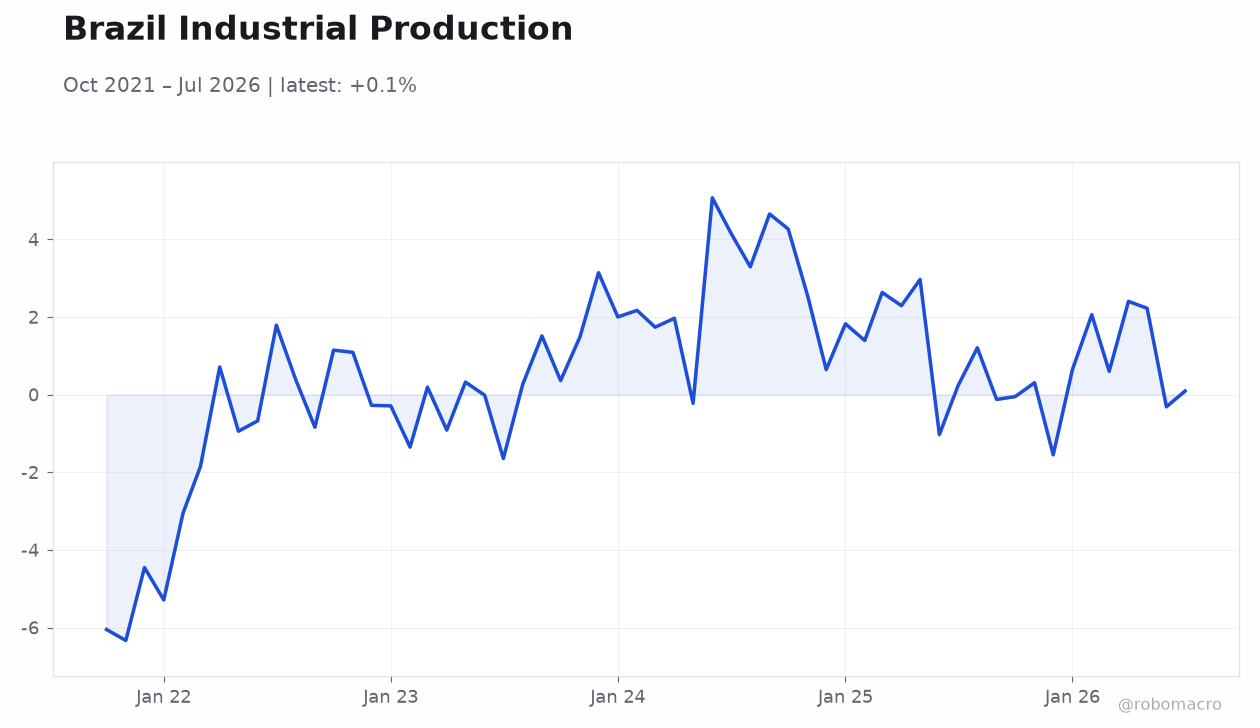
Equity and currency markets advanced on 21 September with no domestic data releases. Bovespa closed at 186,596, up 0.74%. USD/BRL fell 0.62% to 5.11 and EUR/BRL declined 0.80% to 5.85.
Vale finished 0.42% lower at 14.15 while Petrobras dropped 0.82% to 20.63. WTI Crude fell 5.52% to 90.49. Brazil 5-year government yields rose 3 bp to 14.11% and 10-year yields increased 6 bp to 14.25%.
The moves reflected modest positioning ahead of the Copom minutes with limited external drivers. Gold edged down 0.32% to 4,369.90 and Bitcoin fell 0.92% to 85,806.30, underscoring subdued risk appetite across asset classes.
The Day Ahead
Markets will focus on the BCB Copom Meeting Minutes scheduled for 03:00 ET. The release will provide fresh detail on the committee’s assessment of inflation at 4.22% and the Selic path at 14.00%. No other Brazilian data prints are due.
Traders will parse any signals on forward guidance and inflation-targeting tolerance. The minutes represent the primary catalyst for near-term rate expectations and BRL positioning. Attention will center on language around fiscal risks and external shocks rather than any immediate policy shift.
Other Economic Notes
Brazilian states are on track for a R$37bn primary deficit in 2026, adding pressure to fiscal accounts. Social-security claim denials remain near record levels, constraining household income support. President Lula announced Brazil will use Uruguay’s surplus beef-export quota to China, supporting agricultural shipments.
These developments underscore ongoing fiscal and external-sector challenges amid steady commodity prices. Broader regional debates on spending restraint continue to echo through policy circles without immediate domestic data to alter the picture.
Global Macro News
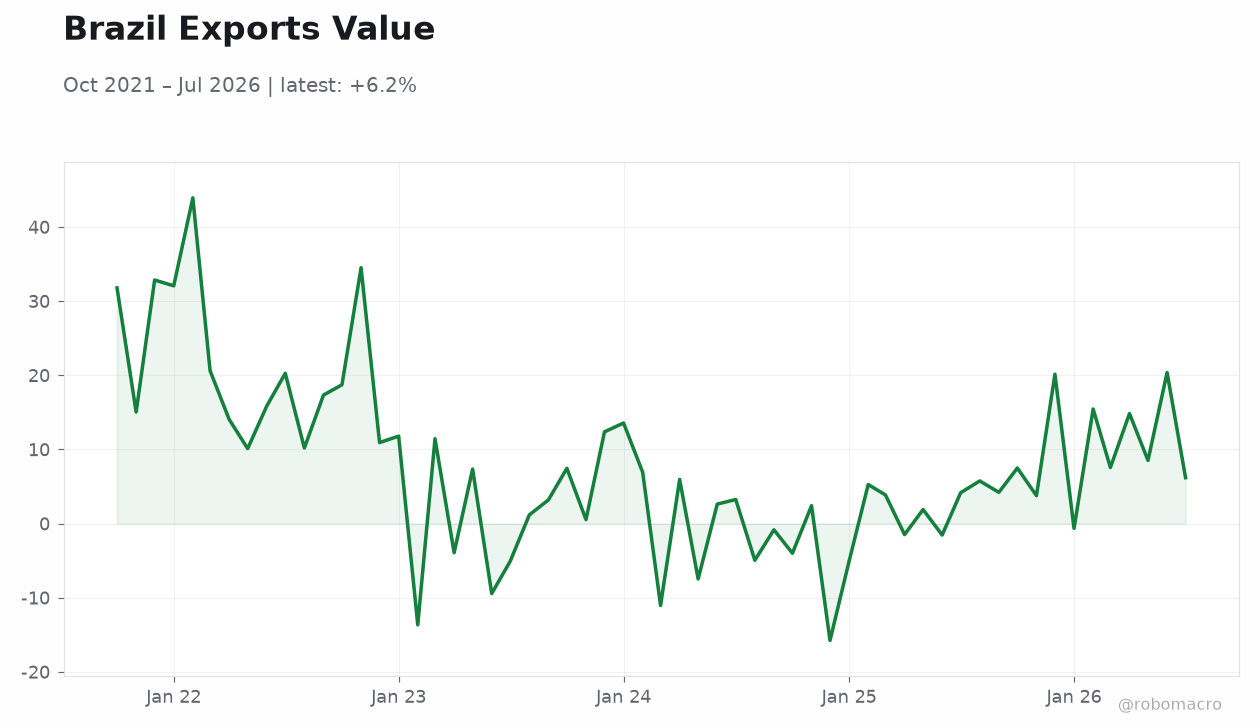
WTI Crude’s sharp 5.52% decline weighed on energy-linked assets and Brazil’s export outlook. The IDB projected AI could expand the Latin America and Caribbean economy by 5.1%, offering potential productivity gains for Brazil. IMF support for central-bank currency interventions may ease external shocks to the BRL.
↓ p.2