Brazil Macro Daily(Beta Mode)
Equities Advance Amid Election Uncertainty
Market Snapshot
| Asset | Level | Change |
|---|---|---|
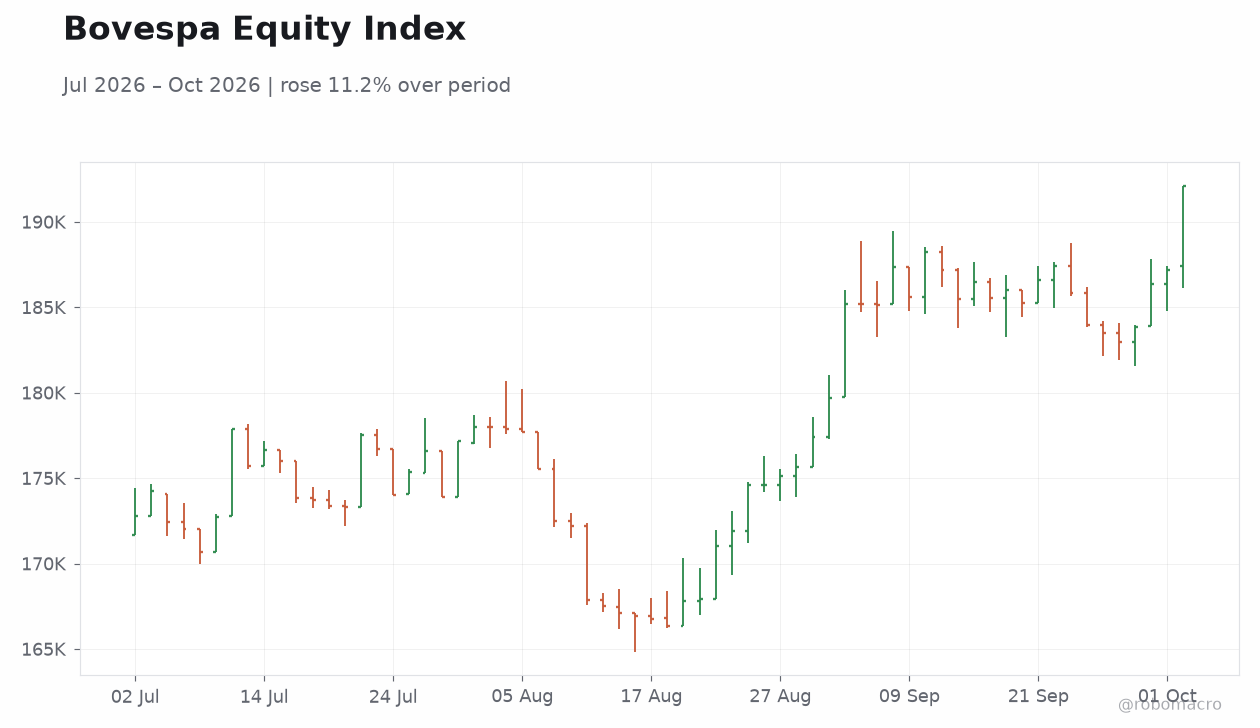
| Bovespa | 192,115.00 | +2.63% |
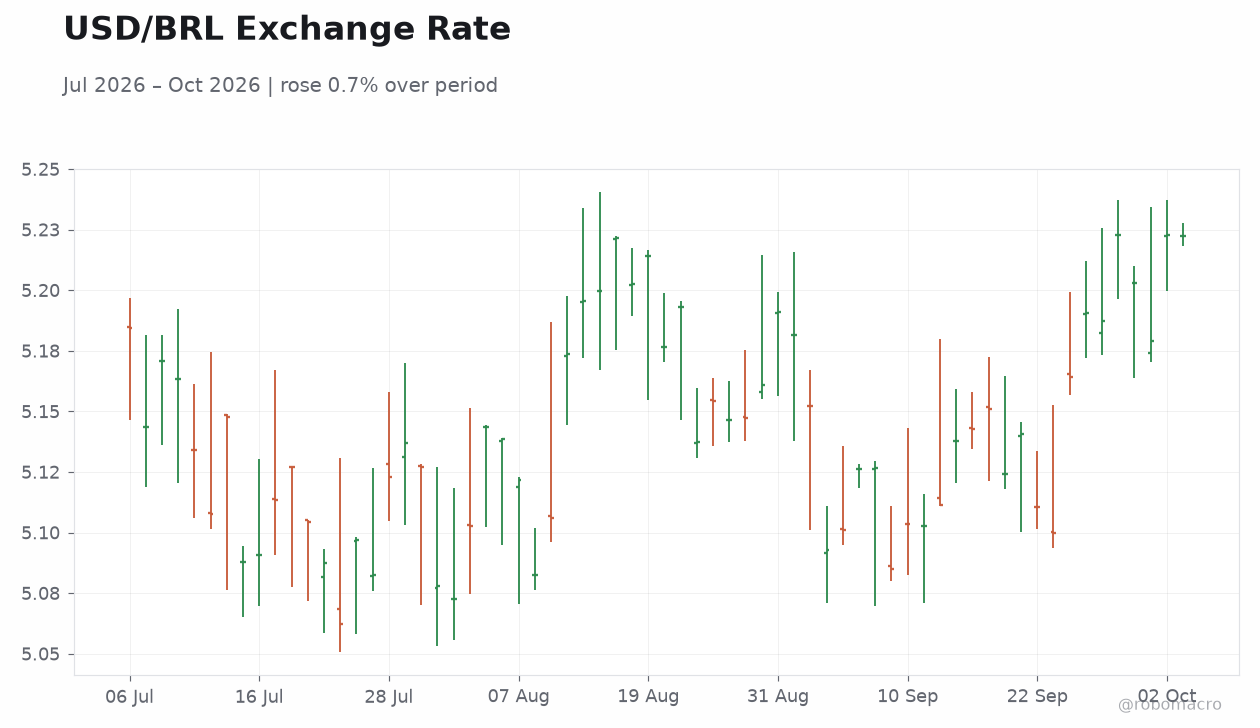
| USD/BRL | 5.22 | -0.01% |
| EUR/BRL | 5.86 | -0.27% |
| Vale | 13.76 | +2.30% |
| Petrobras | 21.65 | +3.19% |
| WTI Crude | 90.46 | -0.71% |
| Gold | 4,193.80 | +0.76% |
| Bitcoin | 86,107.09 | -0.43% |
| Brazil 5Y Govt Yield | 14.11% | +5 bp |
| Brazil 10Y Govt Yield | 14.17% | +15 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
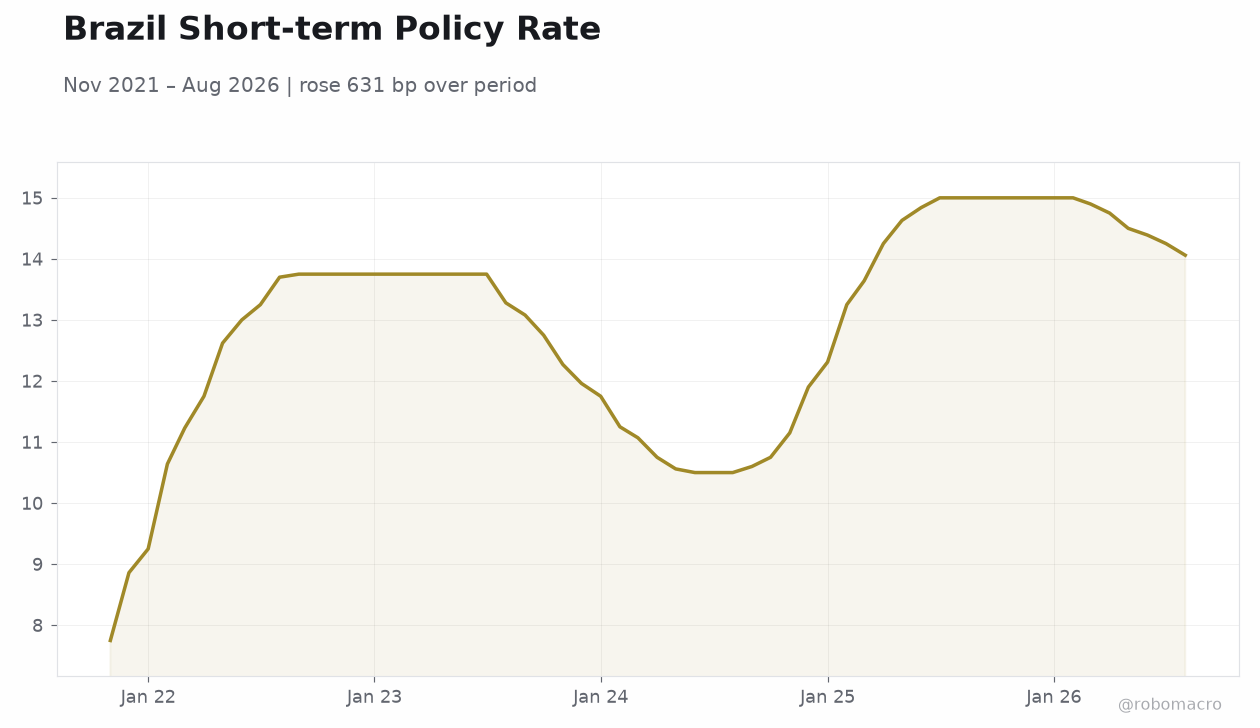 Brazil Short-term Policy Rate | Type: macro_line | Policy Rate %: 14.06 (2026-08-01) | Range: 7.75–15 | Trend(6pt): 7.75,13.75,11.07,14.63,14.25,14.06
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| S&P Global Services PMI | 50.50 | - | 09:00 |
| Tuesday (2026-10-06) | |||
| Trade Balance | 7,390m | - | 14:00 |
| Friday (2026-10-09) | |||
| Inflation Rate Month-over-Month | -0.32 | - | 08:00 |
| Inflation Rate Year-over-Year | 4.22 | - | 08:00 |
- Bovespa rose 2.63% to 192,115 as Vale and Petrobras gained on commodity support.
- Brazil 10-year yields climbed 15 bp to 14.17% while USD/BRL stayed near 5.22.
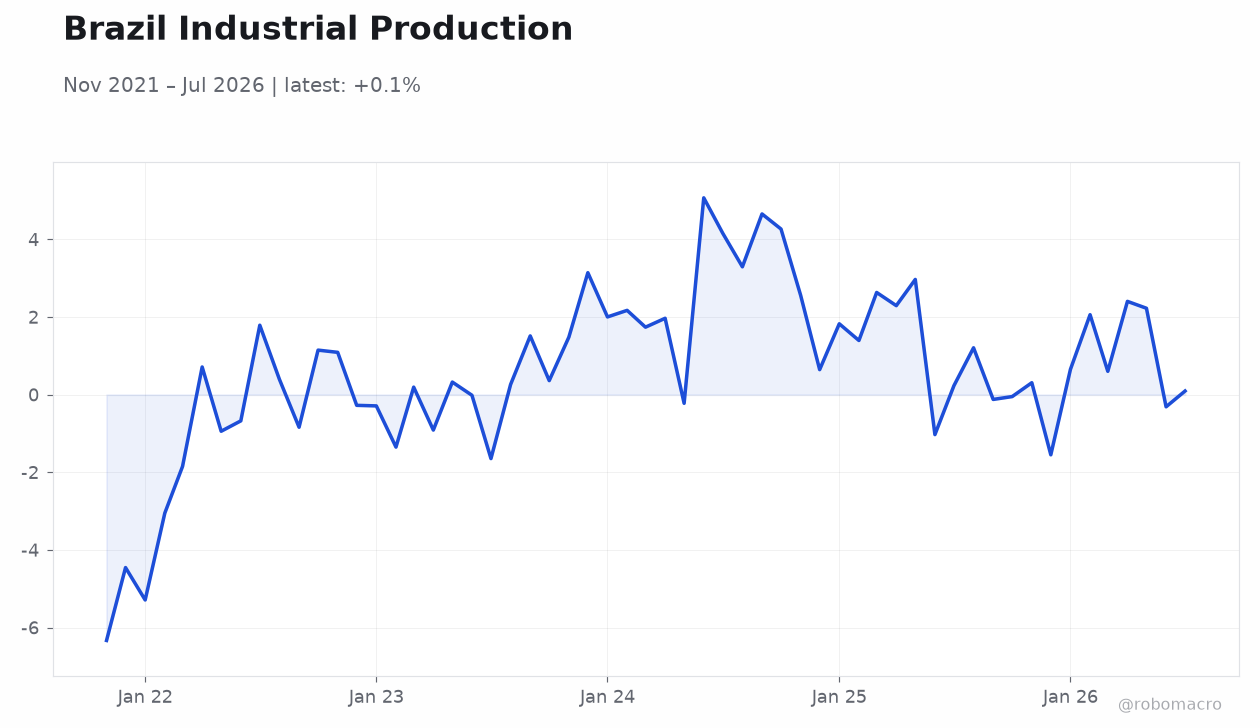
- Services PMI today offers first growth signal after August industrial output contraction.
Yesterday's Recap
Brazilian markets posted solid gains on October 4 despite the absence of any scheduled data releases. Bovespa advanced 2.63% to close at 192,115, led by Vale shares rising 2.30% to 13.76 and Petrobras climbing 3.19% to 21.65. The 5-year government yield increased 5 bp to 14.11% and the 10-year yield rose 15 bp to 14.17%.
USD/BRL edged 0.01% lower to 5.22 while EUR/BRL fell 0.27% to 5.86. News flow highlighted a surprise August industrial output decline that signaled slower economic momentum. Coverage also focused on the unresolved fiscal outlook ahead of the 2026 presidential runoff between incumbent Luiz Inácio Lula da Silva and Flávio Bolsonaro.
The Day Ahead
The S&P Global Services PMI for September prints at 09:00 ET today with the prior reading at 50.5. Markets will watch whether the index remains above the 50 threshold or confirms the recent industrial slowdown. Tomorrow brings the Trade Balance figure for September, previously reported at US$7.39 billion.
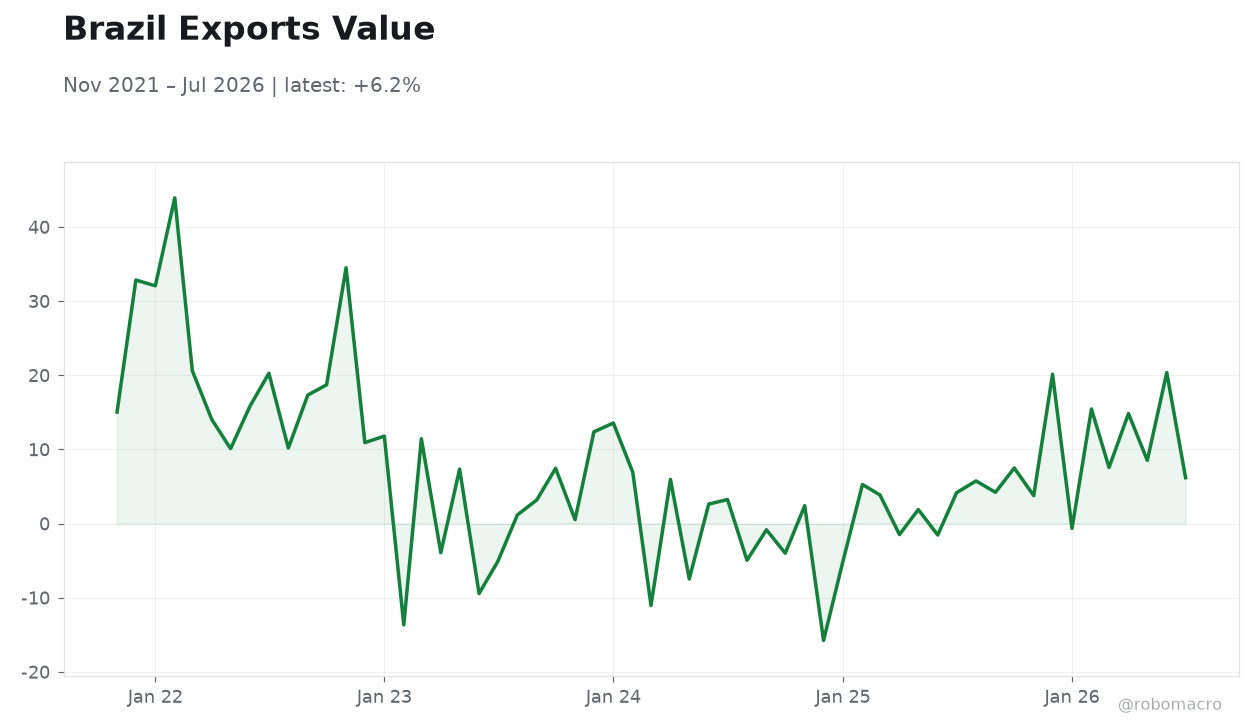
The release may influence BRL volatility given Brazil’s heavy reliance on commodity exports. Friday’s inflation prints will provide the next direct read on price pressures within the BCB’s targeting framework. Traders will also monitor any election-related statements that could affect fiscal expectations.
Other Economic Notes
August industrial output contracted unexpectedly, reinforcing evidence that domestic demand is cooling after earlier resilience. The fiscal trajectory remains a central concern as the presidential campaign intensifies, with both candidates facing pressure to outline credible consolidation plans. Commodity export revenues continue to underpin the external accounts, yet any sustained slowdown in China would weigh on iron ore and soybean prices.
Election-related policy uncertainty is already visible in longer-term yields, which trade well above the Selic rate. Markets await clearer signals on whether the next administration will prioritize spending restraint or expand targeted outlays.