Brazil Macro Daily(Beta Mode)
Brazil Assets Slip as Runoff Risk Builds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 206,495.00 | -0.86% |
| USD/BRL | 5.03 | +0.10% |
| EUR/BRL | 5.65 | +0.20% |
| Vale | 12.70 | -2.46% |
| Petrobras | 25.66 | -0.16% |
| WTI Crude | 99.87 | +2.80% |
| Gold | 4,100.20 | -1.20% |
| Bitcoin | 81,716.74 | -2.73% |
| Brazil 5Y Govt Yield | 12.79% | +14 bp |
| Brazil 10Y Govt Yield | 12.87% | +16 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
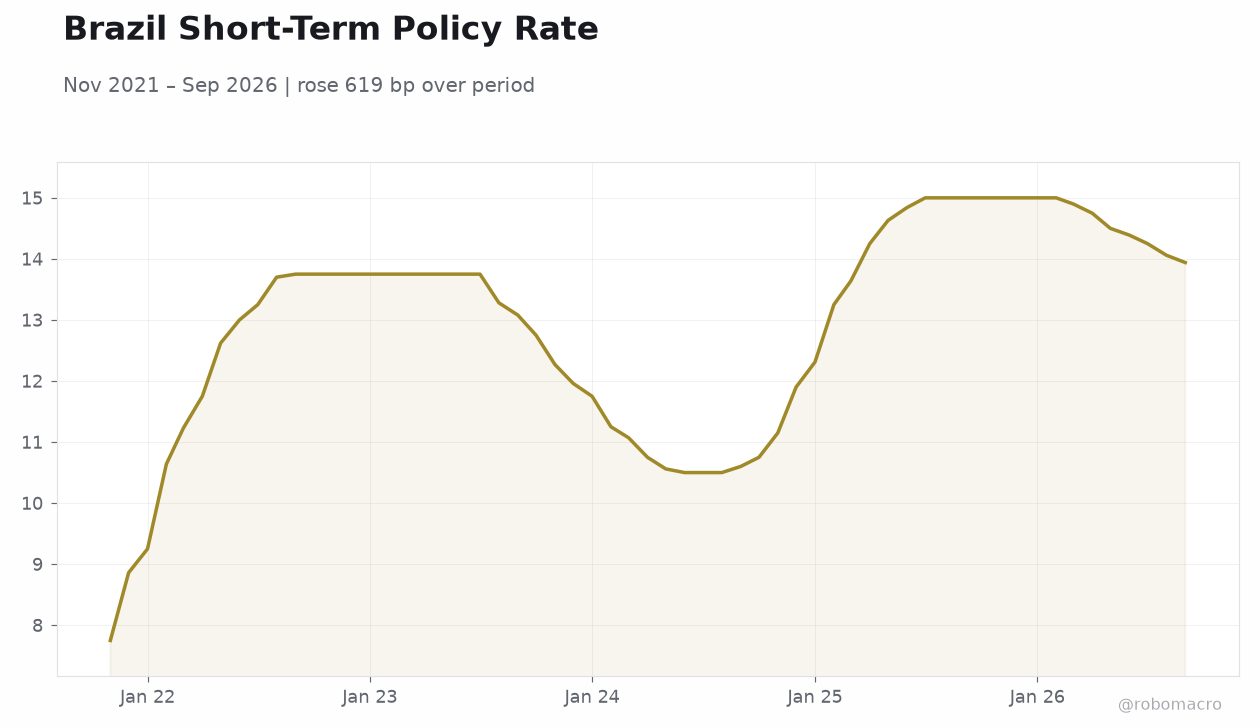 Brazil Short-Term Policy Rate | Type: macro_line | Short-term Rate %: 13.94 (2026-09-01) | Range: 7.75–15 | Trend(6pt): 7.75,13.75,11.07,14.63,14.25,13.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
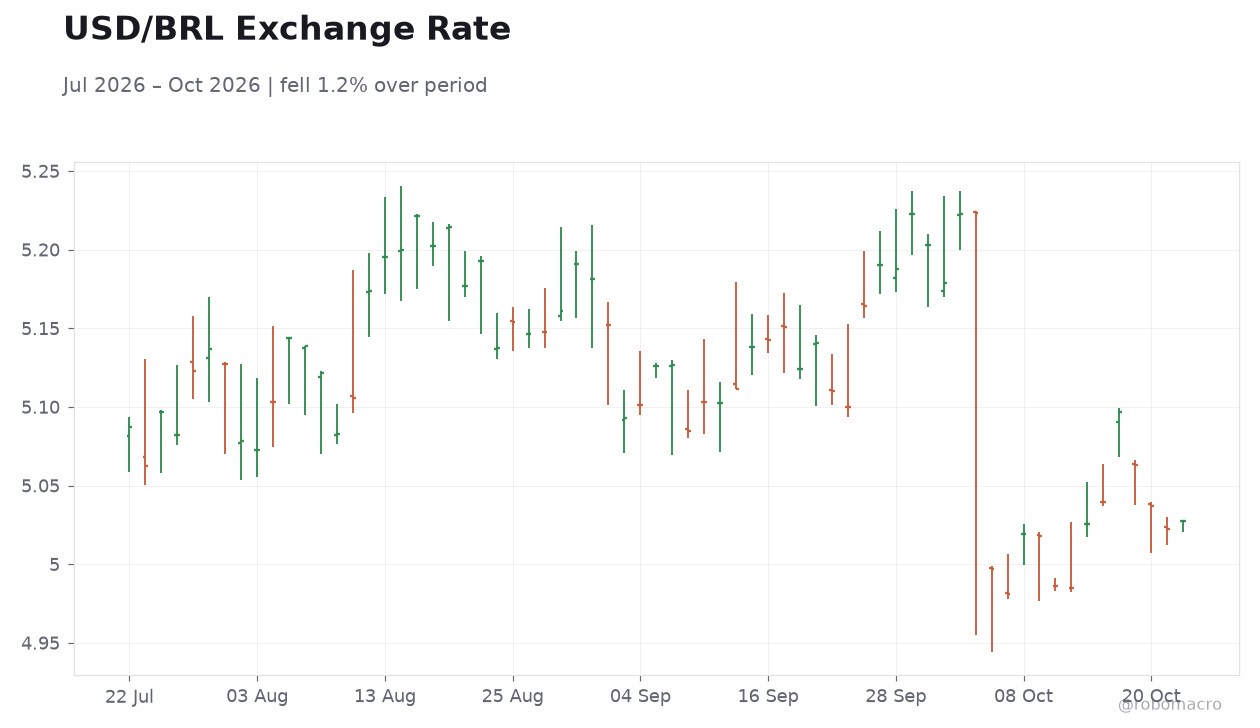
- Brazilian assets traded risk-off yesterday, with the Bovespa down 0.86% to 206,495 and USD/BRL up 0.10% to 5.03.
- Domestic yields rose sharply, with the 5-year up 14 bp to 12.79% and the 10-year up 16 bp to 12.87%.
- Political risk dominates ahead of the Oct. 25 runoff, with markets weighing Lula versus Flávio Bolsonaro.
Yesterday's Recap
Brazilian markets closed risk-off on Oct. 21, with the Bovespa shedding 0.86% to 206,495 and the real softening modestly, USD/BRL up 0.10% to 5.03 and EUR/BRL up 0.20% to 5.65. The fixed-income reaction was more pronounced: the 5-year government yield rose 14 bp to 12.79% and the 10-year climbed 16 bp to 12.87%, a clear repricing of domestic risk premia.
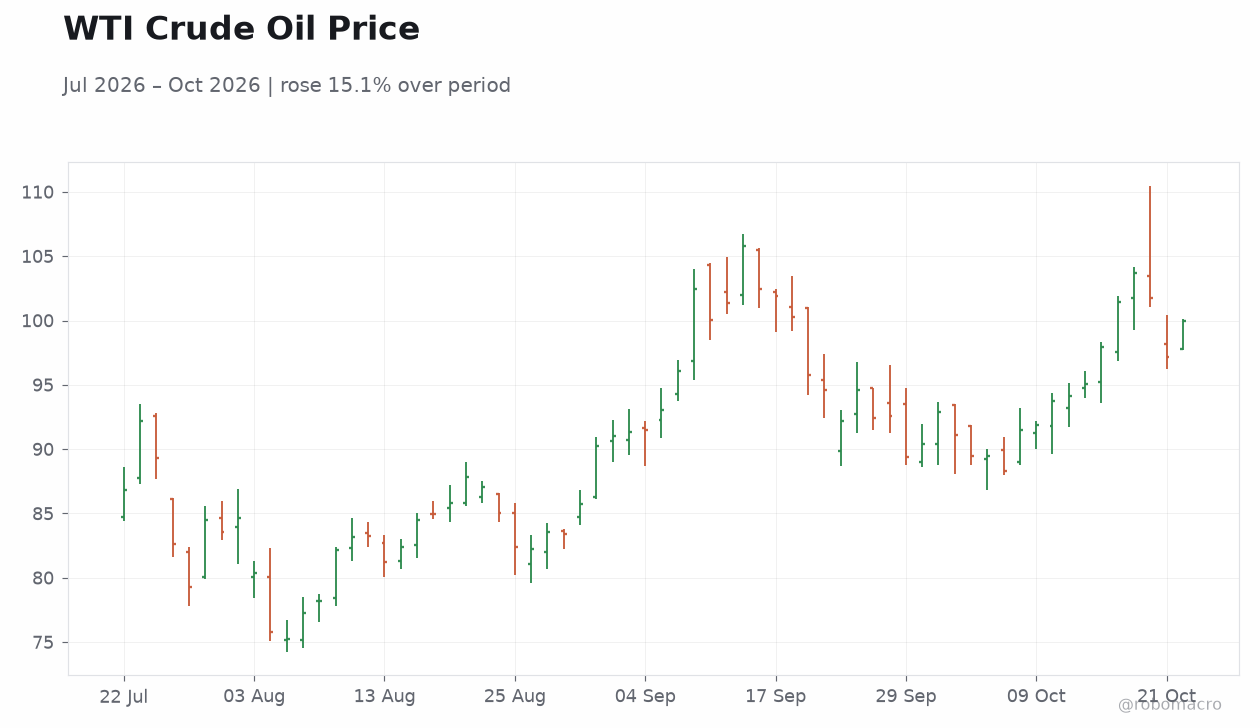
Equity leadership was weak, with Vale down 2.46% to 12.70 and Petrobras off 0.16% to 25.66, even as WTI crude jumped 2.80% to 99.87. Gold fell 1.20% to 4,100.20 and Bitcoin dropped 2.73% to 81,716.74, underscoring a broader de-risking tone. No official Brazilian data releases were scheduled, so price action was driven by positioning and politics rather than fundamentals.
The Day Ahead
The calendar is light again today, with no major Brazilian statistical releases scheduled, leaving markets to trade on political headlines and external cues. Attention stays fixed on the Oct. 25 presidential runoff between Lula and Flávio Bolsonaro, now just three days away, with polls and endorsement news likely to drive intraday volatility.
Investors will watch for any signals on the next administration's fiscal framework and Petrobras governance, following a Bolsonaro adviser's backing of a freer Petrobras while ruling out privatization. With WTI near $100, oil-linked names and the real's commodity terms of trade remain in focus. Absent domestic prints, global risk appetite and US rates will likely set the tone for the Bovespa and the curve.
Other Economic Notes
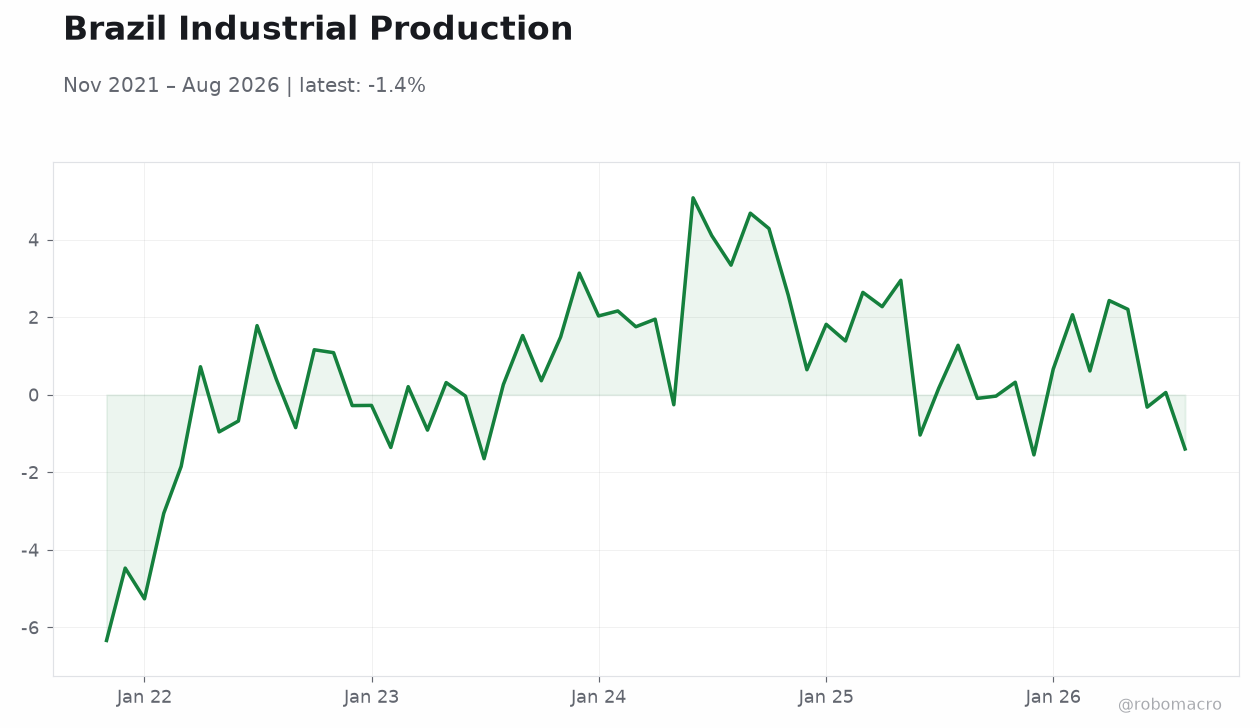
The fiscal outlook remains the central macro vulnerability, with the elevated 12.87% 10-year yield reflecting persistent doubts about debt sustainability and the credibility of the fiscal anchor. Inflation at 4.58% year-over-year sits close to target tolerances, limiting room for aggressive easing even as growth momentum cools. The Selic at 13.75% keeps real rates deeply restrictive, weighing on credit-sensitive sectors and investment.
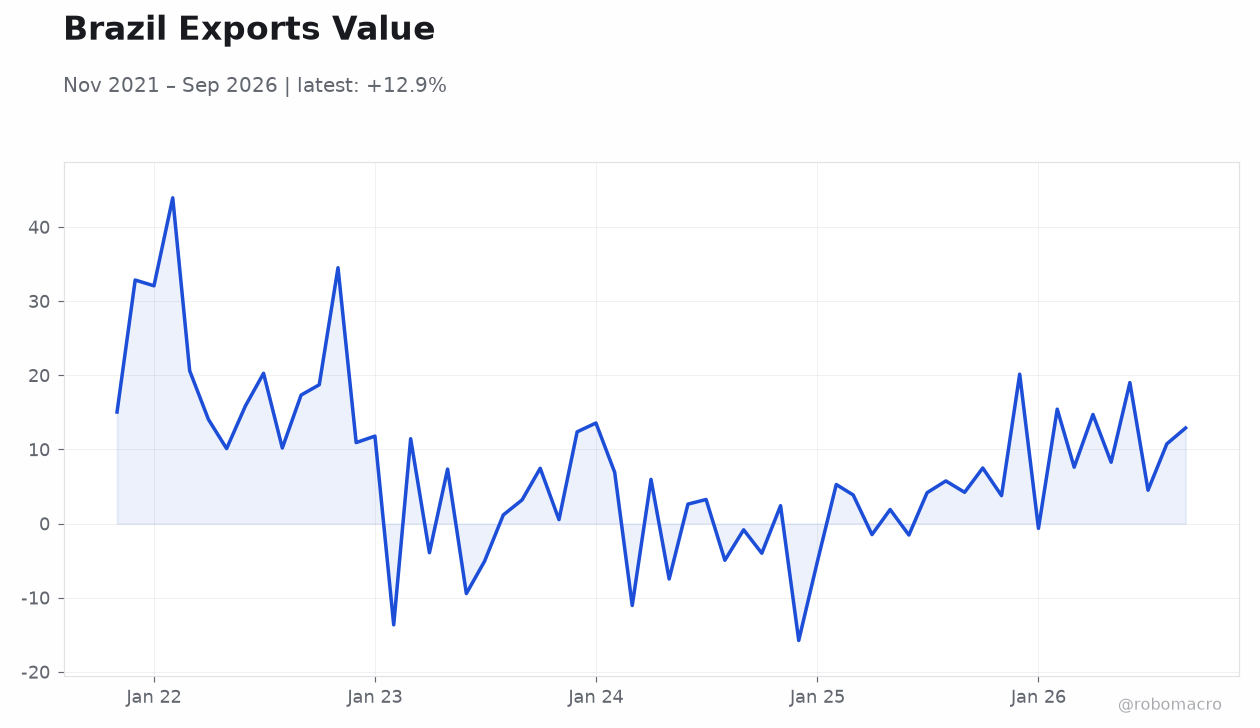
Commodity exports remain a buffer, but iron ore weakness is visible in Vale's 2.46% decline, while crude strength supports the oil complex. The runoff outcome will shape expectations for fiscal discipline, state-company governance and the broader reform agenda.