Brazil Macro Daily(Beta Mode)
BCB Halts Cuts, Petrobras Drags
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 167,564.00 | +1.23% |
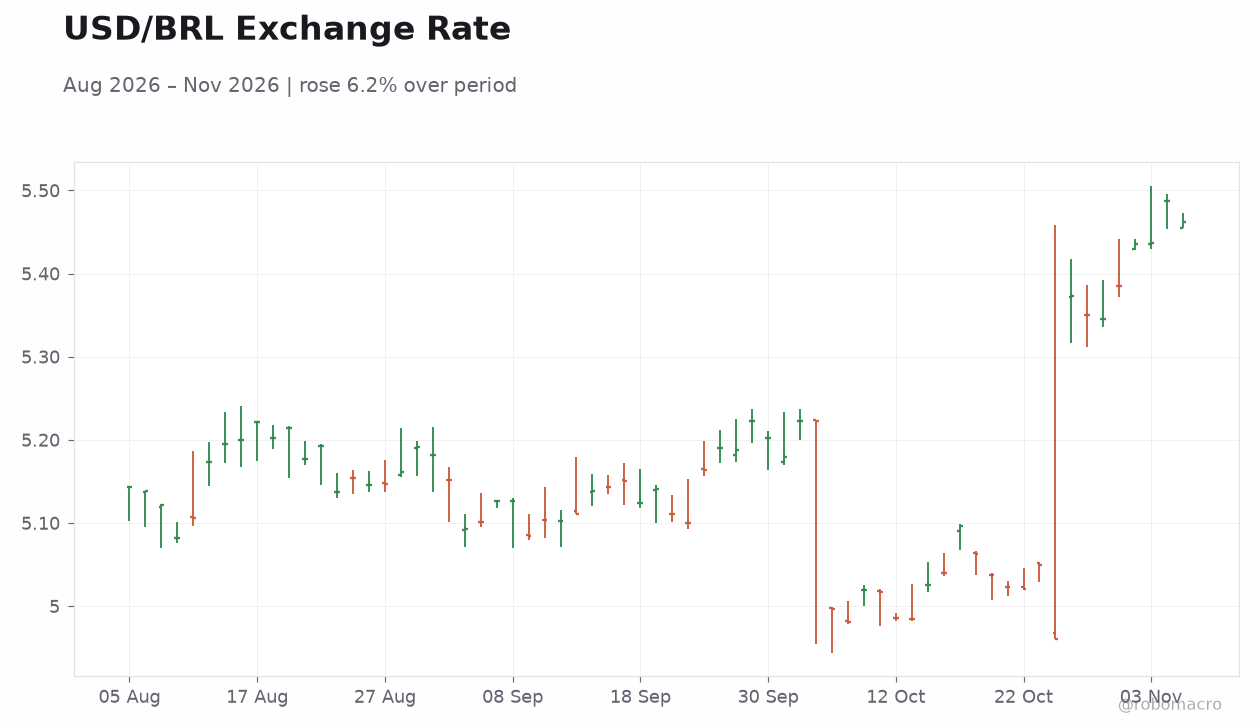
| USD/BRL | 5.46 | -0.44% |
| EUR/BRL | 6.14 | +0.00% |
| Vale | 11.43 | +4.10% |
| Petrobras | 19.61 | -6.97% |
| WTI Crude | 88.05 | -0.08% |
| Gold | 4,136.40 | +1.56% |
| Bitcoin | 80,393.04 | -0.02% |
| Brazil 5Y Govt Yield | 15.29% | +19 bp |
| Brazil 10Y Govt Yield | 15.23% | +23 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BCB Focus Market Readout | - | - | "" |
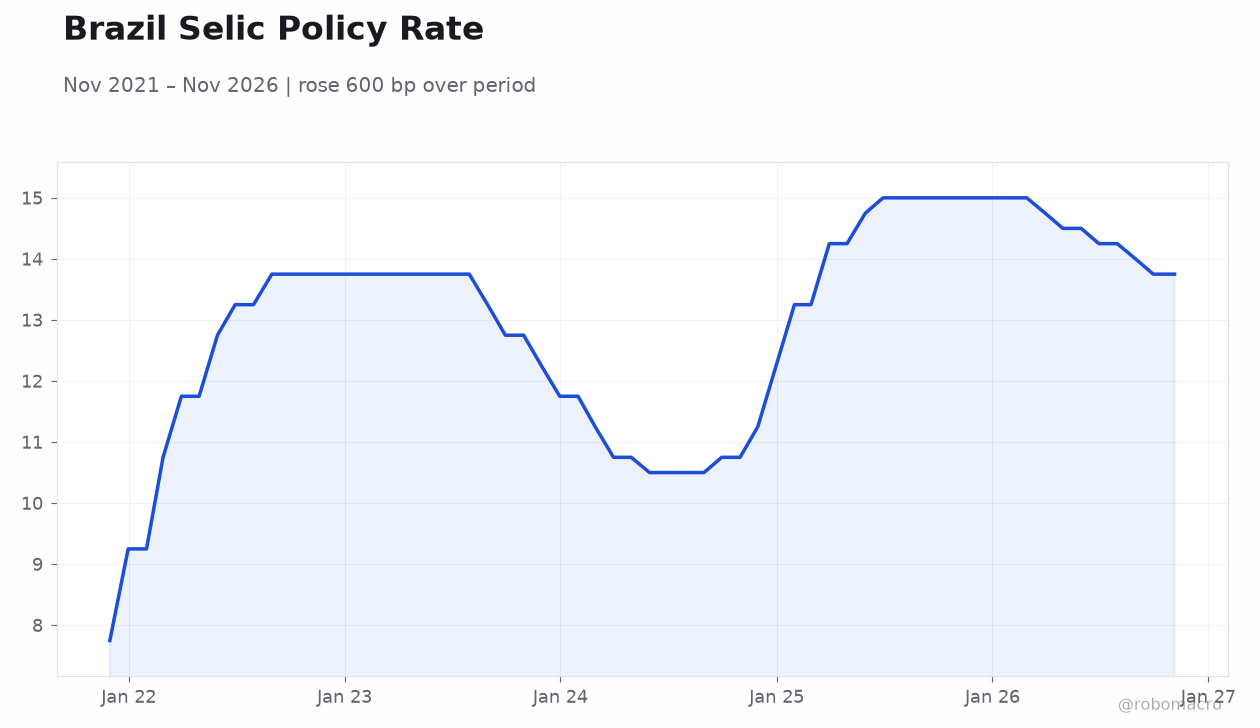
| Central Bank Interest Rate Decision | 13.75 | 13.75 | 13.75 |
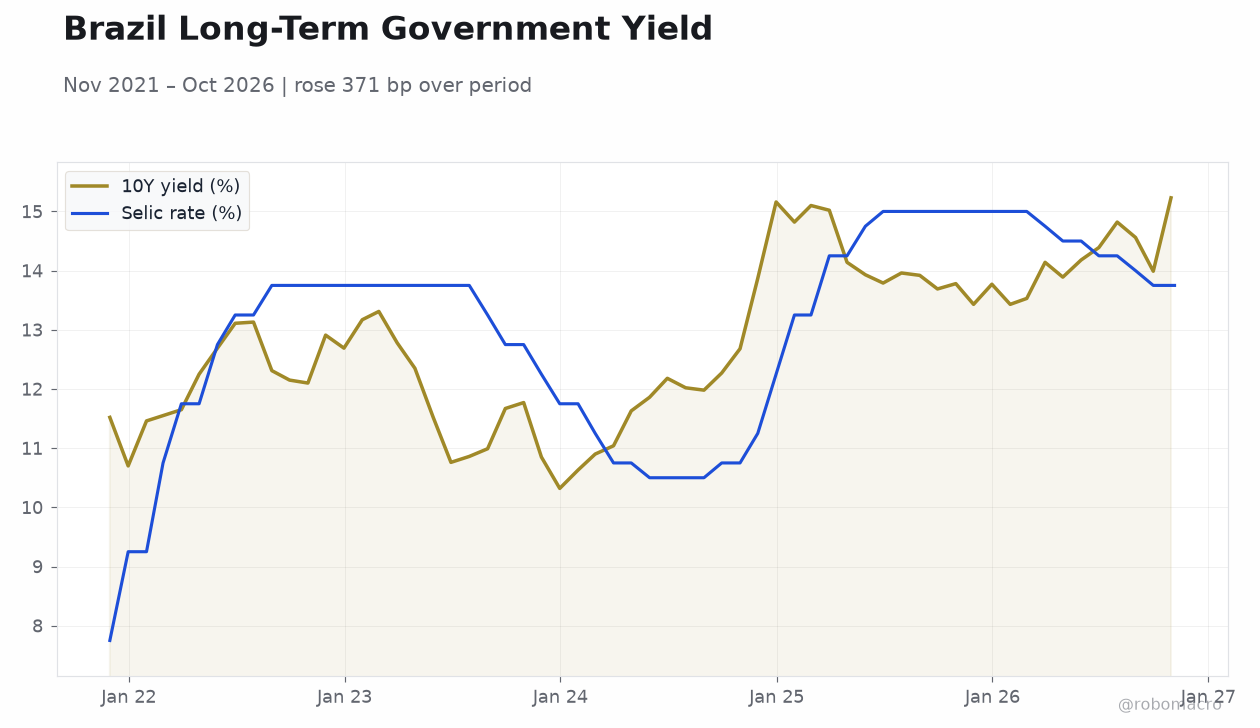 Brazil Long-Term Government Yield | Type: macro_line | 10Y yield (%): 15.23 (2026-10-30) | Range: 10.32–15.23 | Trend(5pt): 11.52,13.31,11.86,13.92,15.23 | Selic rate (%): 13.75 (2026-11-05) | Range: 7.75–15 | Trend(5pt): 7.75,13.75,10.5,15,13.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Industrial Production Month-over-Month | -0.60 | -0.20 | 07:00 |
| S&P Global Services PMI | 49.20 | - | 08:00 |
| Friday (2026-11-06) | |||
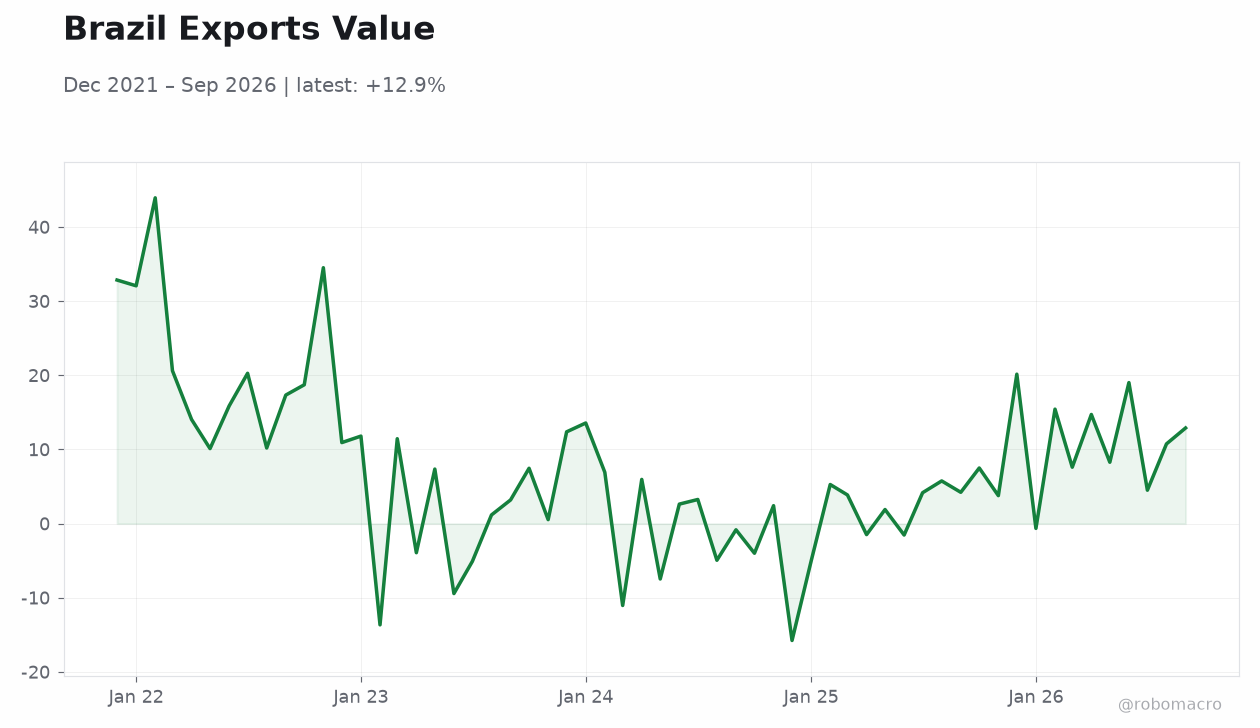
| Trade Balance | 7,740m | 9,000m | 13:00 |
- COPOM held Selic at 13.75%, ending a five-meeting easing cycle as inflation projections worsened and the currency weakened.
- Brazilian assets diverged sharply: Bovespa rose 1.23% to 167,564 while Petrobras fell 6.97% and Vale gained 4.10%.
- The 10-year local yield jumped 23 bp to 15.23%, signaling markets price a higher-for-longer rate path amid fiscal concerns.
Yesterday's Recap
The Central Bank of Brazil's COPOM voted to hold the Selic rate at 13.75% on November 4, interrupting the cutting cycle initiated five meetings prior and matching consensus expectations. The committee voted to hold, according to local press, though no official vote split was disclosed in the calendar data. The BCB Focus Market Readout released earlier in the session showed deteriorating local projections, reinforcing the hawkish tone.
Equity markets were bifurcated: the Bovespa climbed 1.23% to 167,564 points, but Petrobras slumped 6.97% to 19.61 while Vale surged 4.10% to 11.43 on iron ore strength. The real strengthened modestly, with USD/BRL falling 0.44% to 5.46. Local rates bore the brunt of the hawkish hold, with the 5-year yield rising 19 bp to 15.29% and the 10-year adding 23 bp to 15.23%.
The Day Ahead
Attention turns to the morning data slate, with Industrial Production month-over-month for September due at 07:00 ET, where consensus points to a -0.2% print following the prior -0.6% contraction. The S&P Global Services PMI for October follows at 08:00 ET, with the prior reading of 49.2 sitting just below the expansion threshold. Friday brings the November 6 Trade Balance release at 13:00 ET, with consensus at $9.0 billion versus the prior $7.74 billion.
Markets will also digest the full COPOM statement language for forward guidance on the pace and timing of any resumption in easing.
Other Economic Notes
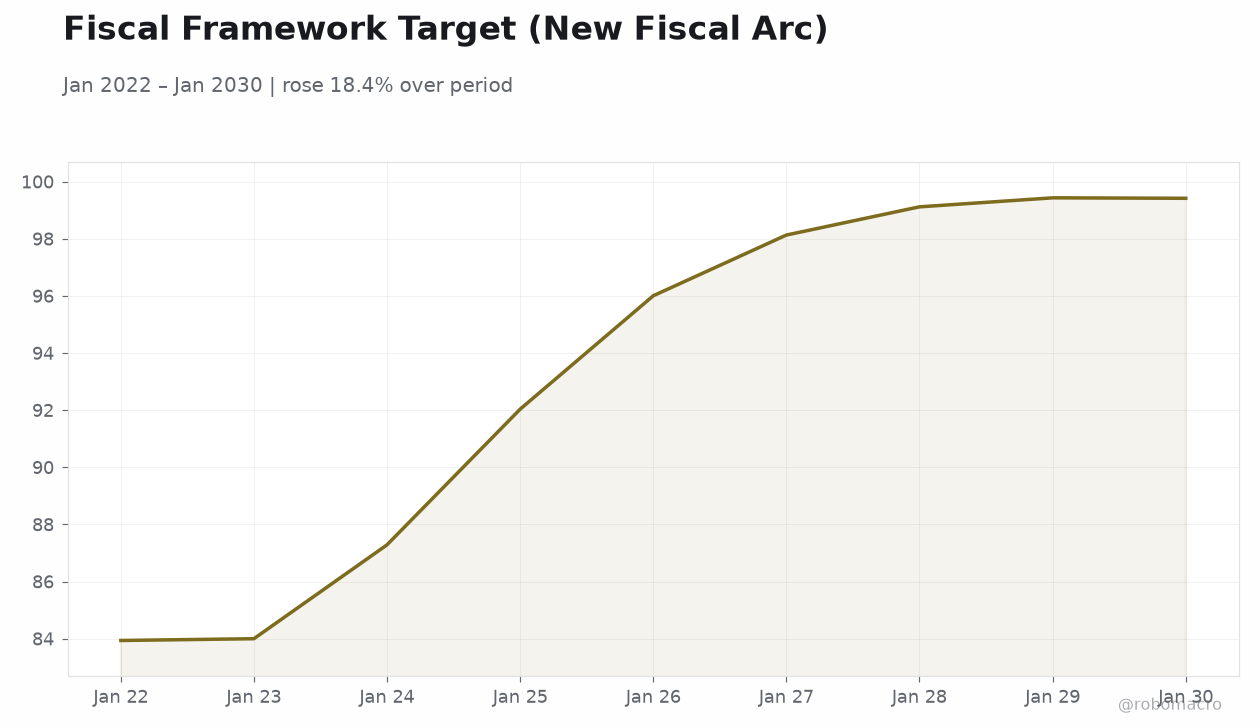
The hold reflects a deteriorating inflation trajectory, with CPI running at 4.58% year-over-year as of September 30, still above the 3% target midpoint. Business federations publicly criticized the decision, arguing that the 13.75% rate punishes industry and consumers while calling for stricter fiscal discipline to relieve pressure on monetary policy. Analysts warn that without fiscal adjustment, elevated rates could constrain economic activity through 2027.
The divergence between Vale's rally and Petrobras' slump underscores commodity-specific dynamics rather than a broad risk-on move. Fiscal sustainability remains the central concern anchoring the elevated local yield curve.