Brazil Macro Daily(Beta Mode)
BCB Hold Meets Fiscal Pledge as Curve Flattens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Bovespa | 168,499.00 | +1.39% |
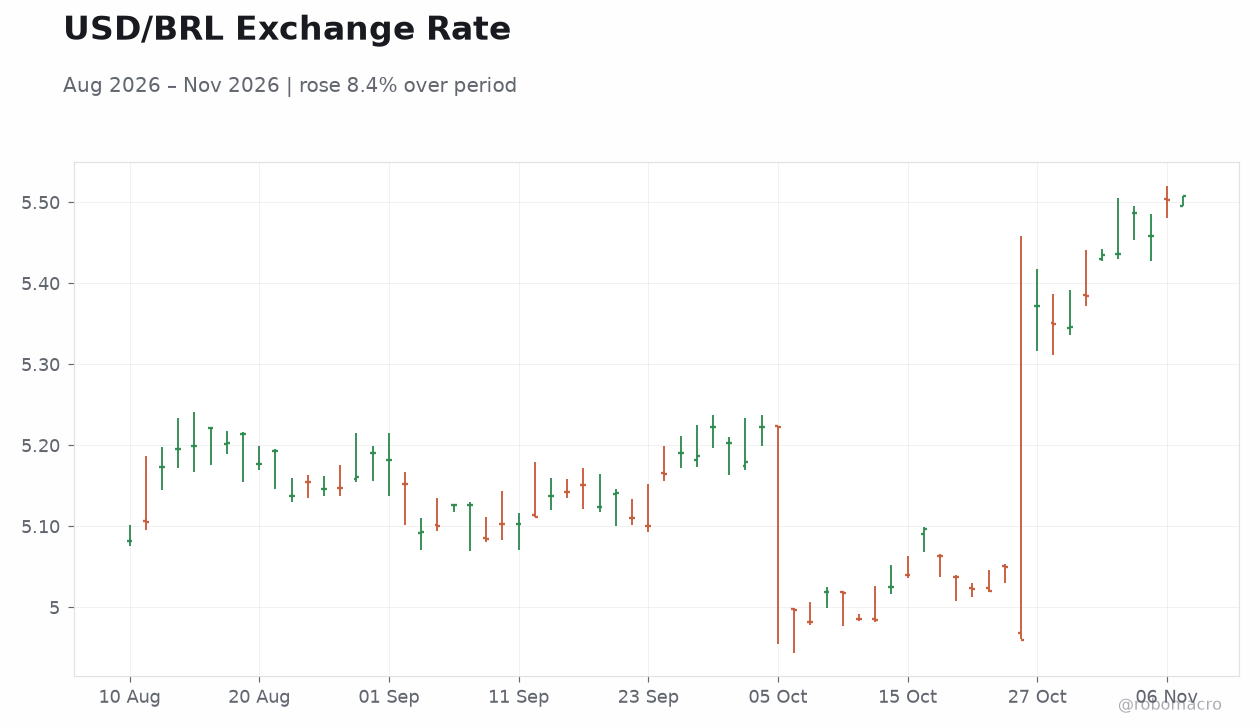
| USD/BRL | 5.51 | +0.07% |
| EUR/BRL | 6.15 | -0.32% |
| Vale | 11.59 | +1.22% |
| Petrobras | 18.53 | -1.44% |
| WTI Crude | 89.65 | -1.30% |
| Gold | 4,103.00 | +0.69% |
| Bitcoin | 74,454.39 | -0.17% |
| Brazil 5Y Govt Yield | 15.08% | -18 bp |
| Brazil 10Y Govt Yield | 15.09% | -12 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
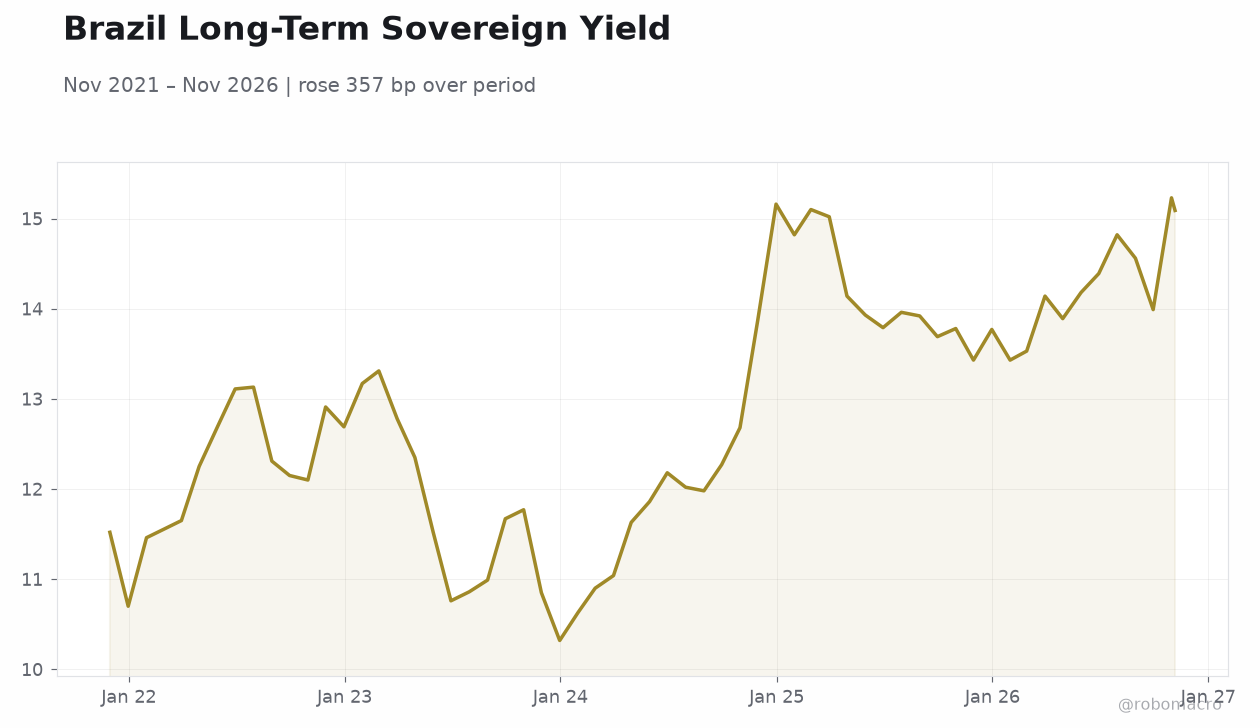 Brazil Long-Term Sovereign Yield | Type: macro_line | 10Y Yield (%): 15.09 (2026-11-06) | Range: 10.32–15.23 | Trend(5pt): 11.52,13.31,11.86,13.92,15.09
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BCB Focus Market Readout | - | - | 06:30 |
| Tuesday (2026-11-10) | |||
| BCB Copom Meeting Minutes | - | - | 06:00 |
| Thursday (2026-11-12) | |||
| Inflation Rate Month-over-Month | 0.82 | - | 07:00 |
| Inflation Rate Year-over-Year | 4.58 | - | 07:00 |
| Friday (2026-11-13) | |||
| Retail Sales Month-over-Month | 0.10 | - | 07:00 |
| Business Confidence Index | 46.20 | - | 09:00 |
- Bovespa closed at 168,499 (+1.39%) while the real held near 5.51/USD (+0.07%), with Petrobras (-1.44%) lagging a firmer tape led by Vale (+1.22%).
- The 5Y and 10Y sovereign yields fell 18 bp and 12 bp respectively, to 15.08% and 15.09%, keeping the curve effectively flat and deeply restrictive.
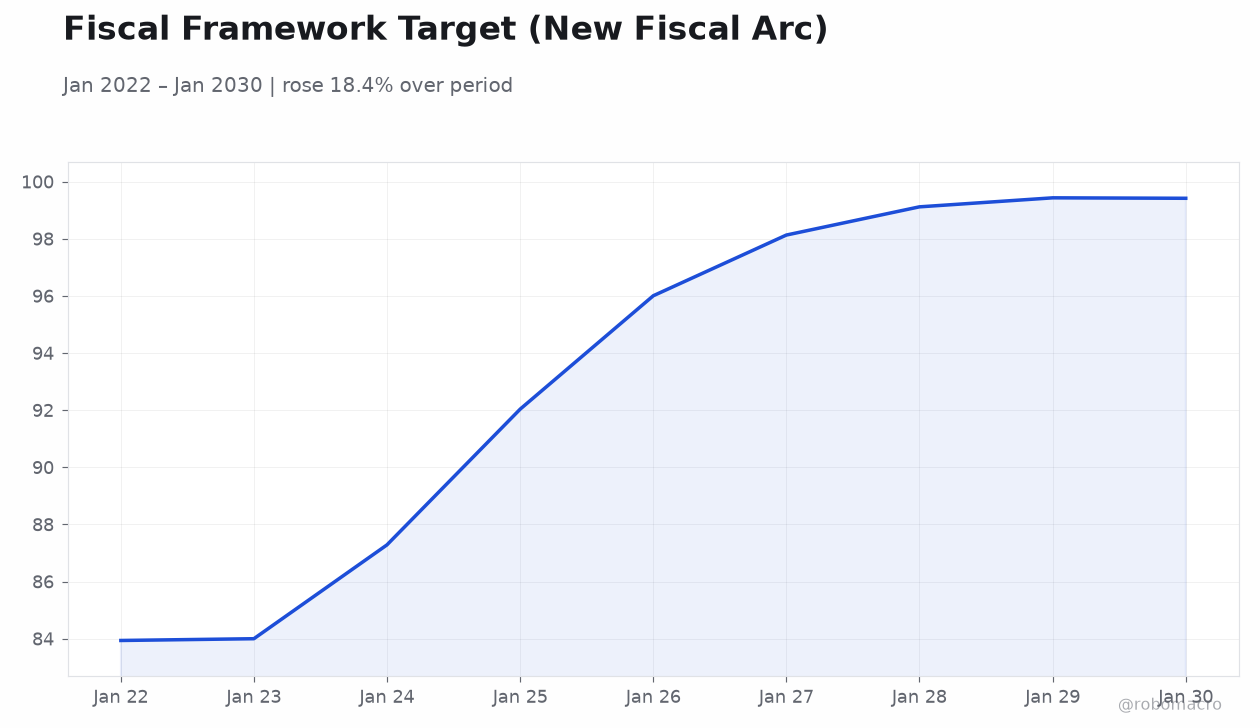
- Lula's first post-election address pledged fiscal responsibility without abandoning social programs; bank growth downgrades raise the fiscal stakes into the December COPOM.
Yesterday's Recap
Brazilian markets opened the week on a constructive footing, with the Bovespa adding 1.39% to 168,499 and the real essentially unchanged at 5.51 per dollar. The sovereign curve rallied, with the 5Y yield down 18 bp to 15.08% and the 10Y down 12 bp to 15.09%, leaving the curve flat-to-inverted and signaling front-loaded restrictive-policy expectations. Equity leadership was narrow: Vale gained 1.22% on iron ore strength, while Petrobras slipped 1.44% as WTI crude fell 1.30% to $89.65.
Gold rose 0.69% to $4,103, and Bitcoin eased 0.17% to $74,454. No official Brazilian data releases printed on the day, so price action was driven by positioning and political headlines. The BCB Focus survey published this morning at 06:30 ET is the first scheduled data point of the week.
The Day Ahead
The high-impact event is Tuesday's COPOM meeting minutes at 06:00 ET, which will be parsed for the committee's read on inflation persistence and the forward path after the November 4 hold at 13.75%. Thursday brings the IPCA inflation prints at 07:00 ET, with month-over-month prior at 0.82% and year-over-year prior at 4.58%, the key test of whether disinflation is stalling. Friday's retail sales release (prior +0.1% m/m) and the Business Confidence Index (prior 46.2, still in contraction territory) round out the week.
With the next COPOM decision set for December 9, this week's data and minutes will shape market pricing for the terminal rate.
Other Economic Notes
Brazilian banks have cut growth forecasts, a signal that credit conditions and the 13.75% Selic are biting into activity and raising the fiscal stakes for the Lula administration. The government has set priorities for 27 critical minerals, positioning Brazil in global supply chains for the energy transition. Car tax breaks have entered a new chapter, with fiscal cost implications for an already stretched budget.
The betting-sector ban debate is adding a further drag on services activity. ↓ p.2